Defined benefit pensions and transfers explained
A plain-English guide to defined benefit (final salary) pensions, transfer values and the advice process. It is general information, not advice about your own pension.
What is a defined benefit pension?
A defined benefit (DB) pension, often called a final salary or career average pension, pays you a guaranteed income for life. The amount depends on your salary and how long you were a member, not on how investments perform. Your scheme's trustees and your employer carry the investment risk.
A DB pension usually gives you:
- an income for life, however long you live
- yearly increases, often linked to inflation
- the option of a tax-free lump sum when you retire, in exchange for a lower income
- a pension for a spouse, civil partner or dependants after you die
- protection from the Pension Protection Fund if your employer becomes insolvent and the scheme can't pay
These guarantees are valuable and would cost a great deal to buy on the open market.
Final salary and career average schemes
There are two main types of defined benefit pension:
- Final salary schemes work out your pension from your salary at or near the time you leave or retire, and the number of years you were a member. For example, a scheme with an accrual rate of 1/60th would pay 30/60ths, or half, of your final pensionable salary after 30 years.
- Career average (CARE) schemes build up a slice of pension each year based on what you earned that year, which is then revalued each year until you retire.
Most private-sector final salary schemes have now closed to new members or to future build-up, but the pension you have already built up is protected. If you have left the scheme, your pension is "deferred" and is usually increased each year until it is paid. Our guide to final salary pensions explains how they work in more detail.
Contracted-out benefits: GMP and Section 9(2B) rights
If you were in a DB scheme between 1978 and 2016, part of your pension may come from being "contracted out" of the additional State Pension. These benefits have their own rules about how they increase and when they can be paid:
- A Guaranteed Minimum Pension (GMP) applies to service between April 1978 and April 1997.
- Section 9(2B) rights apply to contracted-out service from April 1997 to April 2016.
Schemes have also had to equalise benefits for the different GMP ages of men and women. Our article on the GMP equalisation ruling explains what this means.
What is a pension transfer?
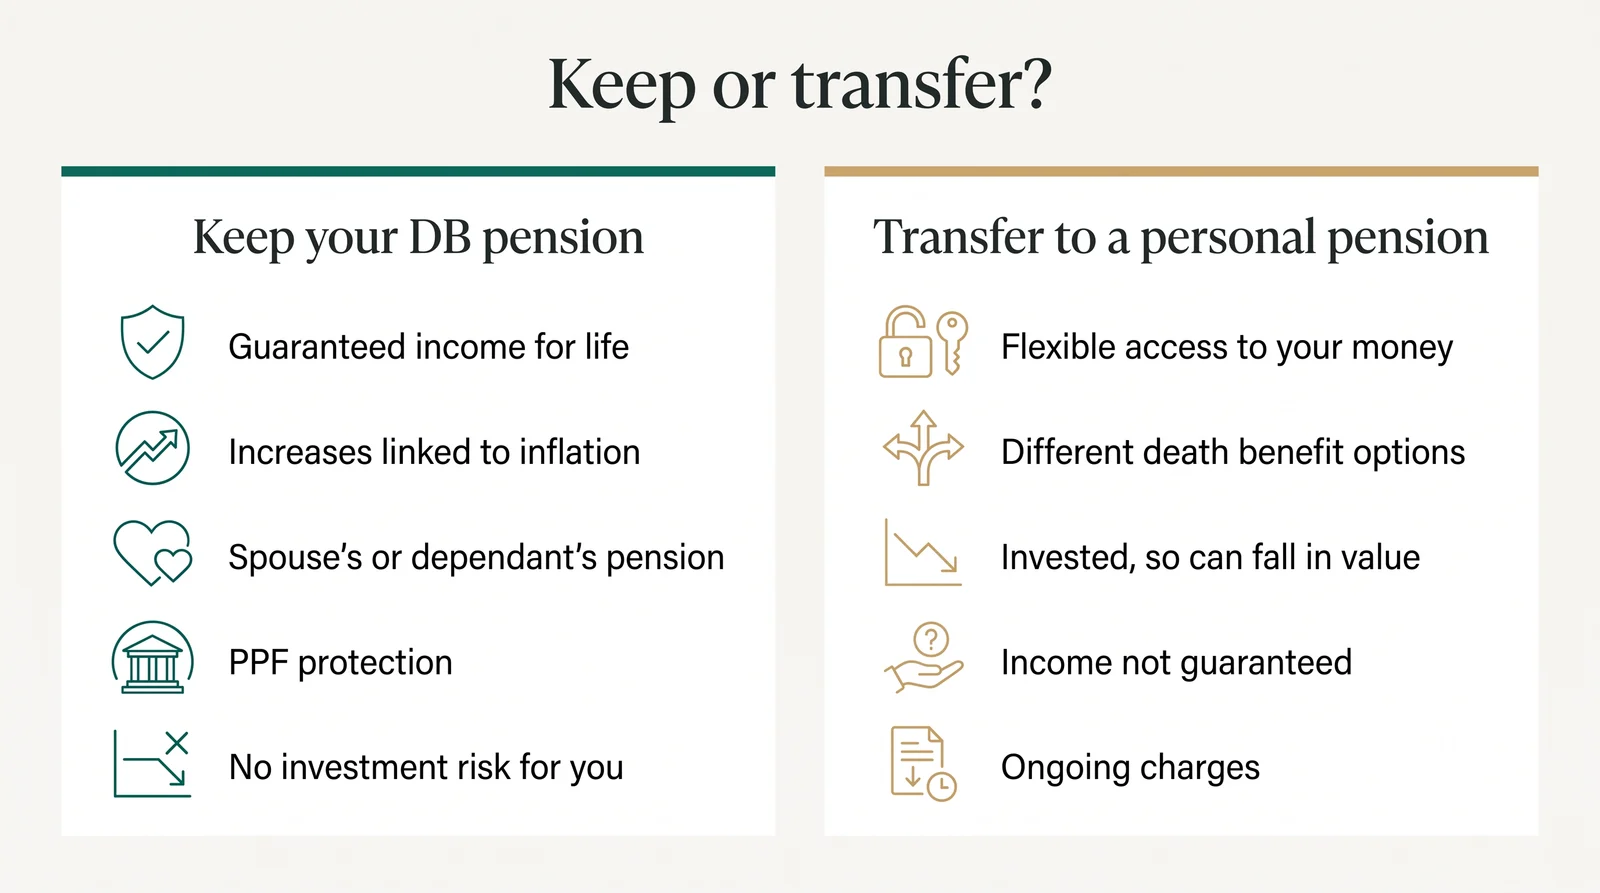
A transfer means giving up your guaranteed benefits in exchange for a cash sum, called a cash equivalent transfer value (CETV). That money is moved into a defined contribution pension, such as a personal pension or SIPP, where it is invested. What you get back then depends on how the investments perform, the charges you pay and how much you take out.
Your transfer value (CETV)
- You can ask your scheme for a CETV. You usually have a legal right to one if you have not started taking the pension and are more than a year from the scheme's normal pension age.
- Most schemes provide one free statement every 12 months.
- The value is guaranteed for three months from its guarantee date. If the transfer is not completed in that time, you may need to ask for a new one.
- Transfer values change over time, mainly with interest rates and gilt yields. A higher figure than you expected is not, on its own, a reason to transfer.
The FCA's starting assumption
The FCA requires advisers to start by assuming that transferring out of a defined benefit pension will not be suitable for you. A transfer should only be recommended where it can be clearly shown to be in your best interests. For most people, keeping a defined benefit pension is the better option.
If you transfer, you give up a guaranteed income for life that usually rises with inflation, and often a spouse's or dependant's pension too. Your new pension will be invested, and its value can fall as well as rise, so you could get back less than the value transferred and your income may not last as long as you need. Once a transfer has gone through it cannot usually be reversed.
The FCA explains more on its page about defined benefit pension transfers.
What affects your transfer value?
A CETV is the scheme's estimate of what your future pension is worth in today's money. It depends mainly on:
- interest rates and gilt yields: when yields fall, transfer values tend to rise, and when yields rise, transfer values tend to fall
- your age and the scheme's normal pension age
- the size of your pension and how it increases each year
- the scheme's assumptions about life expectancy and investment returns, set by the trustees
- the scheme's funding level: if a scheme is underfunded, the trustees may be allowed to reduce transfer values
Read more in what is the transfer value of a pension, what affects defined benefit transfer values and how gilt yields affect transfer values.
Enhanced transfer values and incentive exercises
Sometimes a scheme or employer offers an enhanced transfer value (ETV): a transfer value above the standard CETV, often as part of an exercise to reduce the scheme's long-term liabilities. An enhancement can look attractive, but it doesn't change the basic question of what you would be giving up.
The industry Code of Good Practice on Incentive Exercises sets out how these offers should be made, and the FCA's starting assumption still applies. An employer running an incentive exercise usually pays for independent advice for members. See our illustrative example of an enhanced transfer value.
Why people look into a transfer
People often get in touch because they want to understand:
- whether they could take money more flexibly, at different times
- how death benefits differ between a DB pension and a personal pension
- how a transfer value compares with the income they would give up
- what happens if their employer runs into financial difficulty
These are all reasonable questions. A regulated adviser will weigh them against everything you would lose, and the answer for most people is to keep their DB pension.
Advice is required by law over £30,000
If your safeguarded benefits are worth more than £30,000, the law requires you to take advice from an FCA-authorised firm with the pension transfer permission before you can transfer. Your scheme will check that you have done so before it releases the money.
We do not give this advice. If you would like it, and your transfer value is £50,000 or more, we can introduce you to an FCA-authorised firm that holds the pension transfer permission. You don't have to use the firm we introduce you to, and you can check any firm on the FCA Register.
What the advice process usually involves
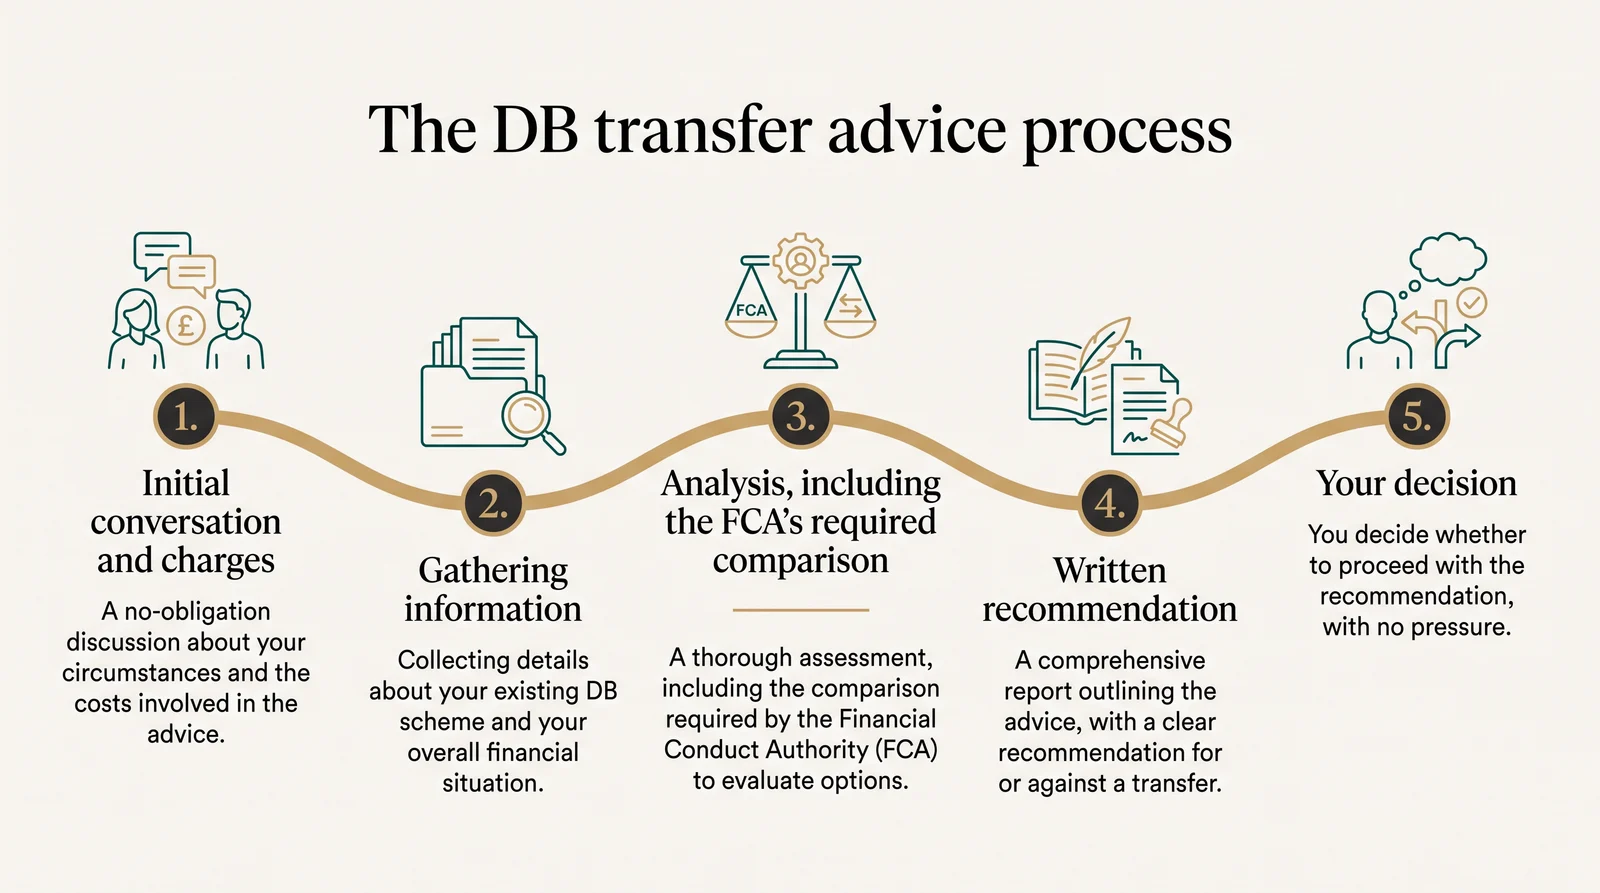
Every firm works slightly differently, but regulated advice on a DB transfer usually includes:
- An initial conversation about your circumstances and what the firm charges.
- Gathering information from you and from your scheme, including your scheme's benefits, your other pensions and savings, your income needs and your attitude to risk.
- Analysis by the adviser, comparing what you would give up with what a transfer could provide. This includes an analysis the FCA requires firms to carry out.
- A written recommendation explaining whether the adviser thinks you should transfer or stay, and why.
- Your decision. Even after advice, the choice is yours. If the recommendation is not to transfer, you could still ask to go ahead, but many firms and pension providers won't help with this, and you would be acting against professional advice.
How advice is charged
Since October 2020, firms advising on DB transfers must generally charge the same fee whether or not you go ahead with a transfer. This is known as the ban on contingent charging. There are limited exceptions for people in serious ill health or serious financial hardship.
The firm will give you details of its charges in writing before you agree to go ahead. Our initial chat is free. Arthur Browns may receive a fee from the firm we introduce you to if you become their client.
Scheme checks and pension scams
Pension scams can cost people their life savings. Before releasing a transfer, schemes must carry out checks. If they see warning signs, they may ask you to book a free pension safeguarding guidance appointment with MoneyHelper, or they may stop the transfer.
Be wary of:
- cold calls, texts or emails about your pension
- offers of a "free pension review"
- promises of high or guaranteed returns
- pressure to act quickly
- offers to release cash from your pension before age 55 (rising to 57 from 6 April 2028)
- overseas investments or unusual schemes
Check the FCA's ScamSmart site and the FCA Register before dealing with any firm.
Related guides
- Final salary pensions explained
- What is the transfer value of a pension?
- What happens to your DB pension if your employer goes bust
- Considering a partial defined benefit transfer
- Pension transfer checklist
- Public-sector pensions: who can and can't transfer
- Guaranteed annuity rates (GARs)
- Guaranteed Minimum Pension (GMP)
- Section 9(2B) rights
- Illustrative examples
Frequently asked questions
Can I transfer my final salary pension into drawdown?
Most private-sector schemes, and the Local Government Pension Scheme, allow transfers out to a defined contribution pension, which could then be used for drawdown. You first need a CETV from your scheme, and if your safeguarded benefits are worth more than £30,000 you must take regulated advice before the scheme will release the money. Members of unfunded public-sector schemes can't transfer to a defined contribution pension.
Can I transfer a pension I'm already being paid?
Usually not. Once a DB pension is in payment, it normally can't be transferred.
Is my transfer value fixed?
It is guaranteed for three months from its guarantee date. After that, the scheme may recalculate it, and it could go up or down.
What happens if I take benefits early?
Most schemes reduce your pension if you take it before the scheme's normal pension age, to reflect that it will be paid for longer. Your scheme can tell you the reduction that would apply.
Can I transfer only part of my pension?
Some schemes allow a partial transfer, but many don't. Your scheme administrator can confirm.
Do I have to pay for the free chat?
No. Our chat is free and there's no obligation. It is general information, not advice.
Where can I get free, impartial guidance?
MoneyHelper offers free, impartial help with pensions, and Pension Wise offers free guidance on your pension options from age 50.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Last reviewed 22 October 2026