Guide
Retirement Planning for Early Retirement

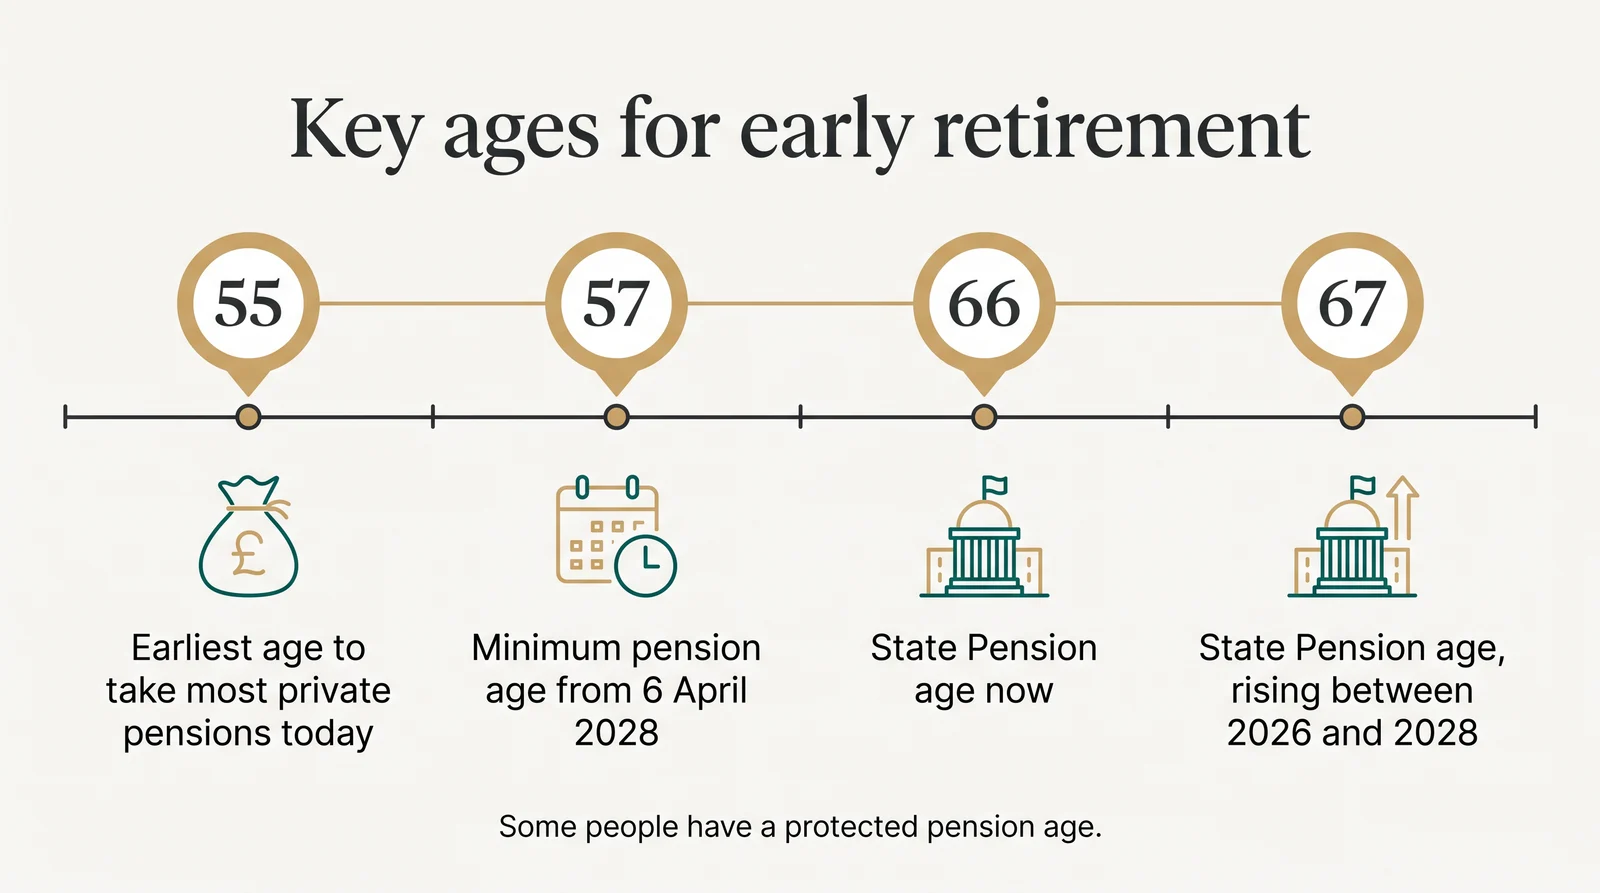
Planning for early retirement in the UK means working out a realistic budget, knowing when you can access each of your pensions, and making sure your money lasts until your State Pension starts and beyond. Most private pensions can be accessed from 55 today, rising to 57 on 6 April 2028, while the State Pension does not start until 66 or 67. If you have a defined benefit pension, taking it early usually means a reduced income, and transferring it is a major decision that needs regulated advice.
When considering early retirement, creating a detailed and realistic retirement budget is essential. That means looking at all your likely spending, including housing, everyday living costs, borrowing and travel. It also means taking stock of your savings, debts and the pensions you have, such as the State Pension, defined benefit pensions and personal pensions.
Long-term care costs are often overlooked, but they belong in the plan too. Understanding the rules on when and how you can take money from your pensions will help you make informed decisions about retiring early.
Early retirement planning involves some complex questions, such as inflation risk and the effect of changes to the rules. Free guidance from MoneyHelper is a good starting point, and a regulated financial adviser can help you build a sustainable income, manage debt and use tax-efficient savings well. They can also explain how taking pension money early might affect your income later.
Looking at all of this in one place gives you a much clearer picture of whether early retirement is realistic, and what you might need to change to get there.
Calculating your retirement budget
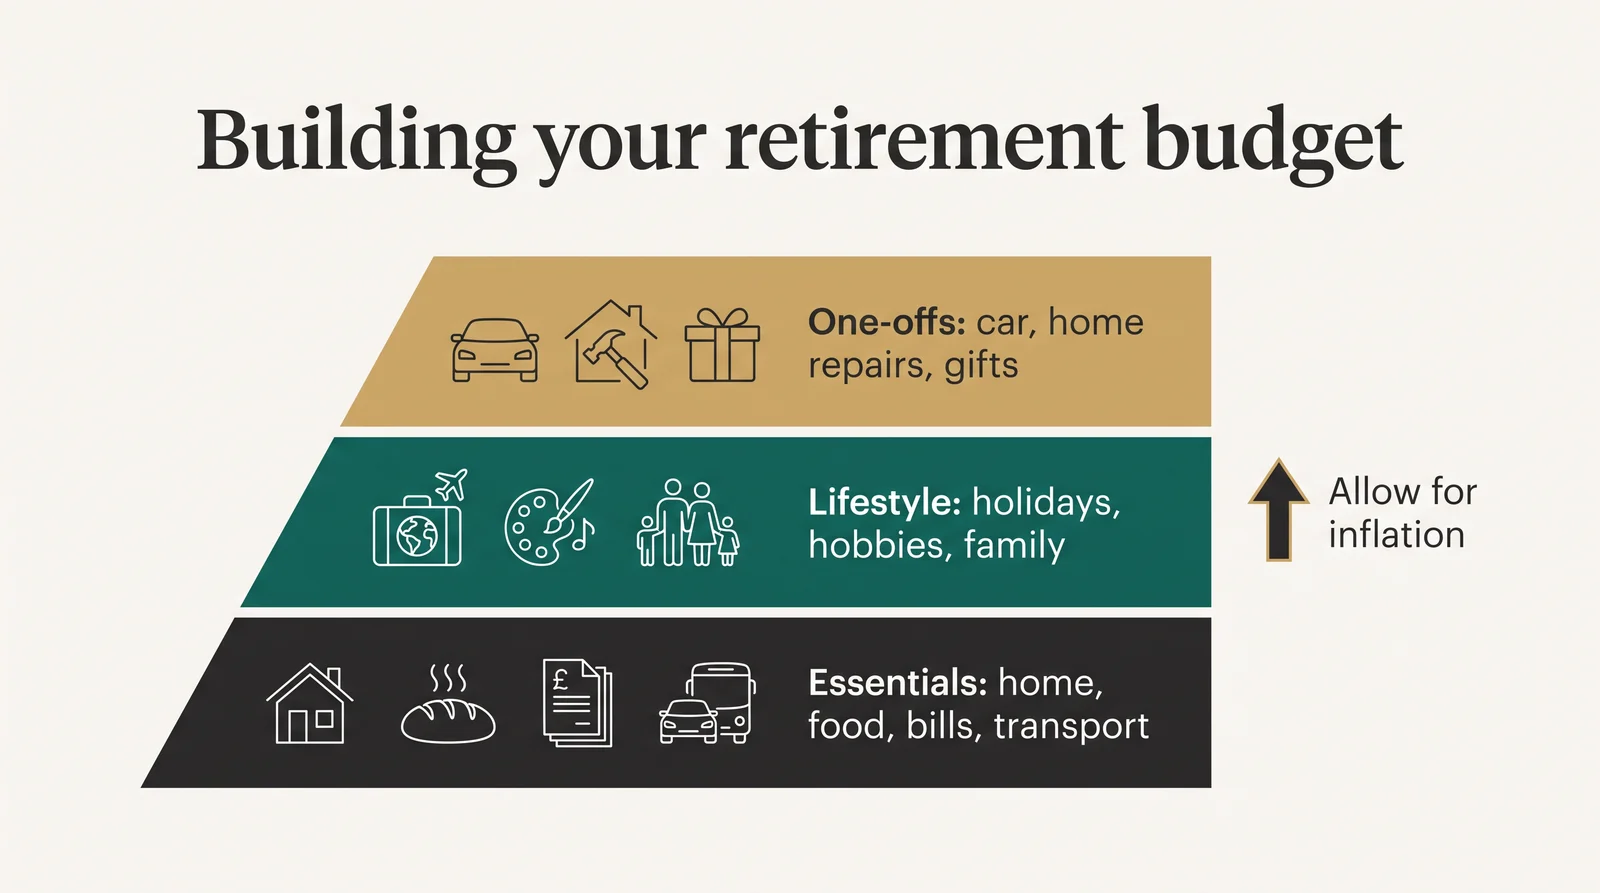
Retiring early means your money has to last longer, so start with an honest look at how much income you will need.
It can be hard to picture, but a useful trick is to imagine you are retiring tomorrow. Think about the debts you would have paid off, such as a mortgage or car finance. Think about costs that would fall away, such as commuting and lunches out. If your children have left home, some family costs may have dropped too.
Now think about what you would add. How many holidays would you like each year? Will you need to replace the car? Would you join a golf club or take up a new hobby?
Comparing your current budget with your expected retirement budget helps you spot any shortfall early. It also helps to split spending into essentials and "nice to haves", so you know which costs need a secure income and which could flex if markets fall.
A commonly quoted rule of thumb, known as the 4% rule, suggests taking about 4% of your savings each year. It comes from research based on historical market returns and is only a rough guide, especially for people retiring early, whose money may need to last 35 years or more. It is also important to plan for tax-efficient withdrawals and for health and care costs, which can rise as you get older.
Adjusting withdrawals in response to how your investments perform can make your plan more resilient. MoneyHelper has a free budget planner that can help you list your costs.
In the end, the aim is a detailed and realistic budget that takes account of all your income and spending, so you can make informed decisions and make the most of what you have.
Understanding your pension options
Planning for early retirement needs a clear understanding of the pensions you have and when each can be paid.
The State Pension
The State Pension is based on your National Insurance record. There are two systems: the basic State Pension, for people who reached State Pension age before 6 April 2016, and the new State Pension, for those reaching it on or after that date.
The full new State Pension is £241.30 a week in 2026/27. The amount you get depends on your National Insurance record: you normally need 35 qualifying years for the full amount and at least 10 to get anything.
State Pension age is 66, and it is rising to 67 for people born on or after 6 April 1960, with the change phasing in between 2026 and 2028. A further rise to 68 is set in law for later years and is under review. You cannot take your State Pension early, however early you stop work. You can check your State Pension age and get a forecast on gov.uk.
Workplace pensions
Workplace pensions, both defined benefit and defined contribution, are the second layer for most people.
Defined benefit schemes pay a guaranteed income in retirement, worked out from your salary and years of service. Each scheme has a normal retirement age, and taking the pension earlier usually means it is reduced. My defined benefit pension guide explains how they work.
Defined contribution schemes build up a pot from your contributions, your employer's contributions and investment growth. You can usually take money from them from the normal minimum pension age.
Personal pensions
Personal pensions, including SIPPs, are usually defined contribution plans that you set up yourself. They give you control over how much you pay in and how the money is invested.
Personal pensions also attract tax relief within limits, which makes them a valuable way to save. You can pay into more than one pension at the same time.
Putting it together
Knowing how your State Pension, workplace pensions and personal pensions fit together is the key to an early retirement plan. A common approach is to use savings and DC pensions to "bridge" the years before a DB pension and the State Pension start. The right approach depends on your circumstances.
Managing care costs
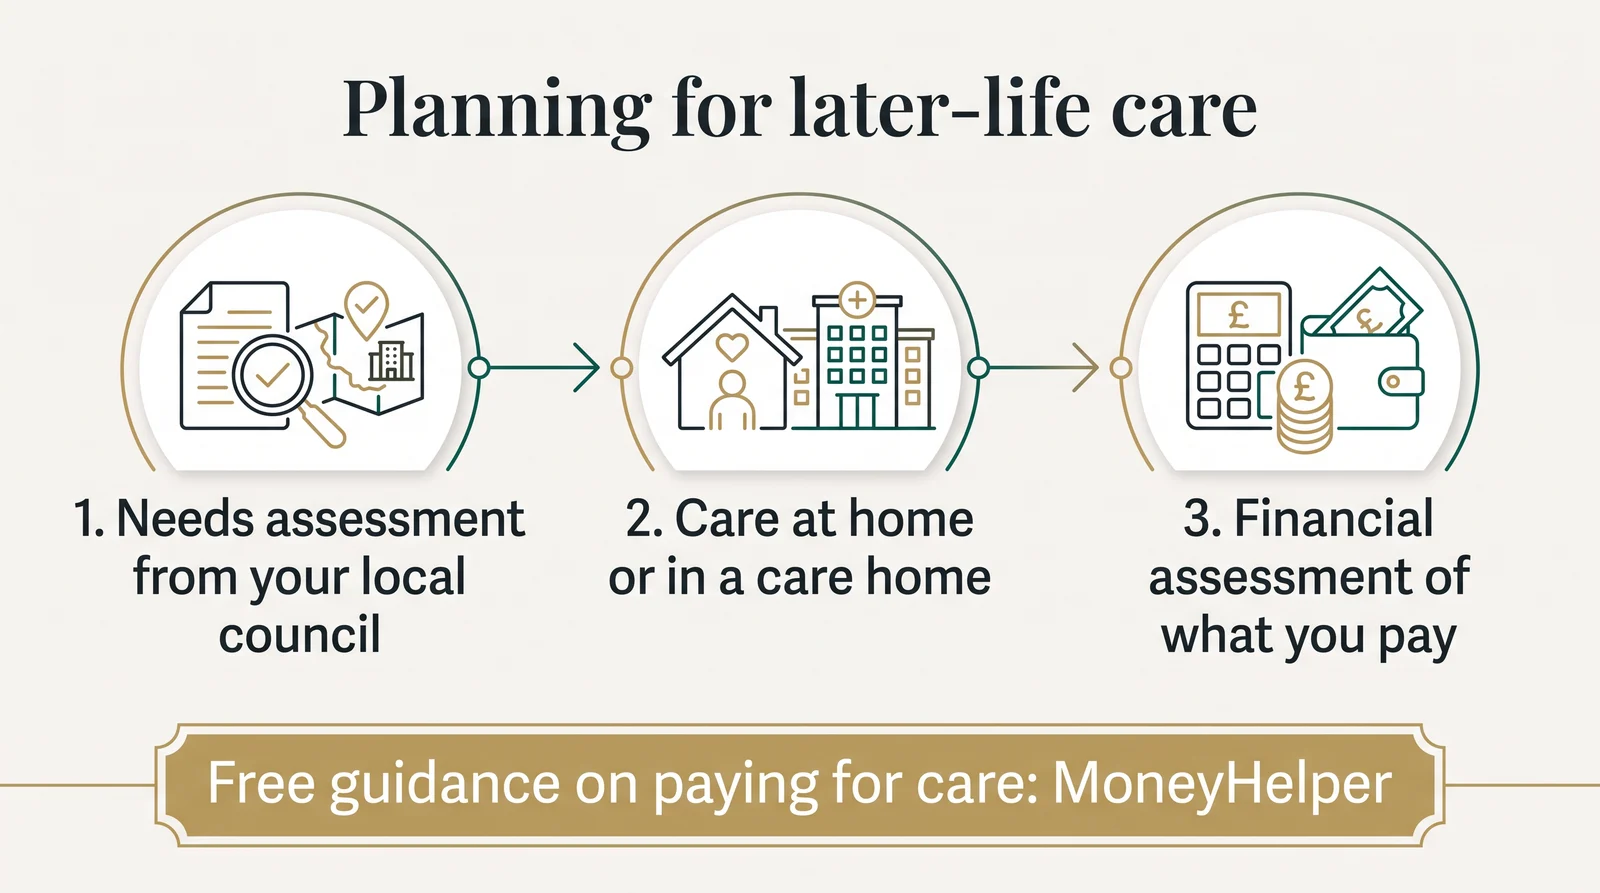
Care costs are a significant risk for many people in later life, and they deserve a place in any long-term retirement plan.
The cost of care varies widely depending on the type of care and where you live, and costs in some areas are much higher than in others. Rather than relying on an average, it is worth looking at local care home and home care costs if this is a concern for you.
In England, help from your local council is means-tested. If your capital is above the upper limit (currently £23,250 in England), you will usually be expected to pay for your own care. Different rules apply in Scotland, Wales and Northern Ireland. A plan to introduce a cap on care costs in England from October 2025 was cancelled in 2024, and the system remains under review. MoneyHelper's guide to care costs explains the current rules.
Planning ahead can help. Some people use immediate needs annuities, which pay a guaranteed income towards care fees for life in return for a lump sum. Others plan to use savings or property. Care homes often charge self-funding residents more than council-funded residents for the same care, which is worth knowing when you plan.
Keeping an emergency fund, understanding the difference between personal care costs and accommodation costs, and staying up to date with changes to the rules can all help. If care costs are a real concern, a regulated adviser who specialises in later-life planning can help you look at the options.
Navigating tax and benefits
Tax is a key part of planning for early retirement. Understanding how pension income is taxed helps you make your money go further.
The personal allowance is currently £12,570. Income above that is subject to income tax at 20%, 40% and 45%, with the higher rate starting at £50,270 and the additional rate at £125,140 in England, Wales and Northern Ireland. Scotland has different bands. Pension income counts towards these limits, but National Insurance is not charged on it.
When you take money from a DC pension, 25% is usually tax-free and the rest is taxed as income in the year you take it. Taking pension money before the normal minimum pension age is only allowed in limited cases, such as serious ill health or a protected pension age. Unauthorised payments, often linked to pension scams, can lead to tax charges of up to 55%.
The annual allowance limits how much you can pay into pensions each year with tax relief. It is £60,000 for most people, lower for some high earners, and falls to £10,000 for DC pensions (the money purchase annual allowance) once you have flexibly taken taxable income. This matters if you plan to take pension money early and keep paying in.
The Lifetime Allowance was abolished from 6 April 2024. It was replaced by the Lump Sum Allowance (£268,275), which limits the total tax-free cash you can take, and the Lump Sum and Death Benefit Allowance (£1,073,100).
From 6 April 2027, unused pension funds and most death benefits are due to come into the scope of inheritance tax. This may change how people with larger pension pots plan to use their savings.
Pension tax rules keep changing, so it is worth checking the latest position on gov.uk before making decisions.
Most personal and workplace pensions can be accessed from 55, rising to 57 on 6 April 2028. Some people have a protected pension age that lets them take benefits earlier. If you are planning to retire in your mid-fifties, it is important to check how the change affects you.
If you have a defined benefit pension
A defined benefit pension can be a strong foundation for early retirement, because it pays a guaranteed income for life. But if you take it before the scheme's normal retirement age, the income is usually reduced to reflect the longer time it will be paid.
Some people consider transferring a DB pension to get earlier or more flexible access to the money. This is a major decision. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people, and if your safeguarded benefits are worth over £30,000, the law requires regulated advice from an FCA-authorised firm with the pension transfer permission before you can transfer. Unfunded public sector schemes, such as the NHS, Teachers', Police, Firefighters', Civil Service and Armed Forces schemes, cannot be transferred to a DC pension at all. See my public sector pensions guide.
Be wary of anyone who contacts you out of the blue offering to help you release pension money early. Check the FCA ScamSmart site before acting.
If you would like a free chat about how DB transfers and the advice process work, you can get in touch. The chat gives general information, not advice. If you then want regulated advice on a transfer value of £50,000 or more, I can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client.
Summary
When planning for early retirement, look carefully at your finances to make sure you have enough to last. That means a realistic budget covering both essential and discretionary spending.
Understanding your pensions is just as important: when you can take your State Pension, and how and when you can use your workplace and private pensions, including the tax that applies.
Planning for the long term, thinking about care costs and understanding the tax rules are all part of a sound plan. Free guidance from MoneyHelper and Pension Wise can help, and a regulated adviser can give you a personal recommendation.
It also makes sense to use tax-efficient savings such as ISAs and pensions while you are working, and to review your budget regularly so your plans keep up with changes in your life.
Taking these steps gives you the best chance of an early retirement that is both enjoyable and financially secure.
Frequently asked questions
At what age can I access my pension for early retirement in the UK?
The normal minimum pension age is 55 and rises to 57 on 6 April 2028. Some people have a protected pension age. State Pension age is 66, rising to 67 for people born on or after 6 April 1960. A defined benefit scheme has its own normal retirement age, and taking benefits earlier usually means a reduced pension. Taking pension money before the minimum pension age is generally only possible in cases such as serious ill health.
How much money do I need to retire early in the UK?
It depends on your lifestyle and when you plan to retire. A rough rule of thumb is to multiply your expected yearly spending by 25 (the reverse of the "4% rule"). For example, £30,000 a year would suggest about £750,000. This is only a starting point, and it does not account for your State Pension, any DB pension or other income. A regulated adviser can help you work out a personal target.
What happens to my defined benefit pension if I retire early?
If you take a DB pension before the scheme's normal retirement age, it is usually reduced to reflect the longer period it will be paid. The reduction varies by scheme and is often a few per cent for each year taken early. Your scheme booklet or administrator can tell you the early retirement factors. Transferring a DB pension is a separate, regulated decision that needs advice from a firm with the pension transfer permission.
How does early retirement affect the State Pension?
If you stop work before you have 35 qualifying years, you may not get the full new State Pension (£241.30 a week in 2026/27). Each qualifying year is worth roughly one thirty-fifth of the full amount. You may be able to fill gaps with voluntary National Insurance contributions, and some people get National Insurance credits, for example while caring or claiming certain benefits. You cannot take the State Pension before State Pension age, whenever you stop work.
Should I transfer my pension to fund early retirement?
Transferring a defined benefit pension is a complex, regulated decision. DB pensions provide guaranteed income, inflation protection and spouse's benefits that are hard to replace. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people, and regulated advice from a firm with the pension transfer permission is legally required if your safeguarded benefits are worth over £30,000.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read