Guide
What is a pension transfer value (CETV)?

A pension transfer value is the amount your scheme would pay into another pension if you moved your benefits. For a defined contribution pot it is usually the current value of your investments, less any exit charges. For a defined benefit (final salary) pension it is a cash equivalent transfer value (CETV): the scheme's actuarial estimate of what your guaranteed income is worth today, which is usually guaranteed for three months.
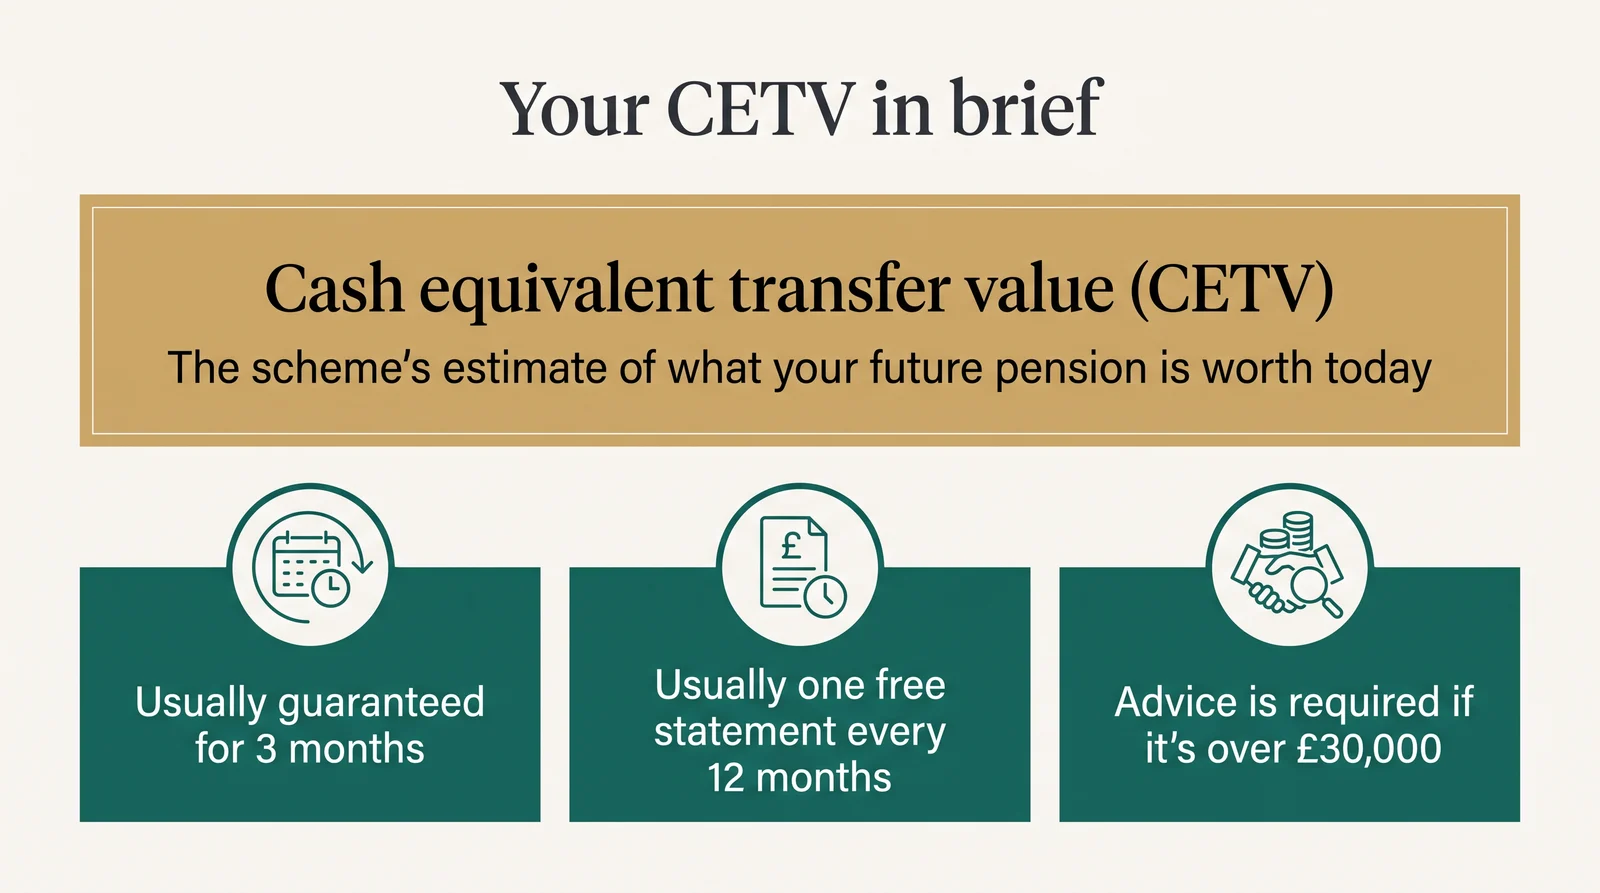
CETV meaning: CETV stands for cash equivalent transfer value. It is the lump sum a defined benefit pension scheme would pay into another pension if you gave up your promised benefits and transferred out. The scheme's trustees work it out on an actuarial basis, it is guaranteed for three months from its guarantee date, and it is paid to another pension, not to you as cash.
Understanding your transfer value
If you have received a transfer value, or are thinking about asking for one, it helps to understand what the figure means before you do anything with it.
A transfer value is the amount your pension scheme or provider would move to another pension on your behalf. It is not simply the total of your contributions. Depending on the type of pension, it can be affected by market conditions, the underlying investments, actuarial assumptions and the rules of your scheme. Some of these factors can make a big difference to the figure you are quoted.
Understanding how your transfer value is worked out will help you make an informed decision. Making the wrong decision without fully understanding your scheme could cost you a great deal, particularly with a defined benefit pension, where a transfer means giving up a guaranteed income for life.
How are the transfer value and fund value different?
The transfer value is the amount that would actually move to a new pension. The fund value is what your savings are worth now, before any exit charges or adjustments.
For defined contribution pensions, the fund value is fairly simple: your contributions plus or minus investment returns, less charges. The transfer value may be lower if the plan has exit charges or, for some with-profits funds, a market value reduction.
For defined benefit schemes there is no fund in your name. The CETV is an estimate of the present value of the future benefits you would be giving up. It is a complex calculation that takes into account your age, your accrued pension, the scheme rules and the actuary's assumptions.
What is a cash equivalent transfer value (CETV)?
If you have a defined benefit pension, the CETV is the sum the scheme would pay to another pension if you chose to transfer out. It represents the scheme's view of what your pension rights are worth in today's money. It is not fixed: it depends on factors such as your age, the scheme's own assumptions, gilt yields and life expectancy.
Key points about CETVs:
- It is a guaranteed figure for a limited time. A CETV is usually guaranteed for three months from its guarantee date. To keep that figure, you normally need to apply to transfer, in writing and with any required advice in place, before the guarantee runs out. After that, a new figure is needed and it could be higher or lower.
- You are usually entitled to one free statement every 12 months. Further statements in the same year may carry a charge.
- Asking for one does not commit you to anything. But once a transfer goes ahead, it cannot normally be reversed.
- Advice is legally required above £30,000. If your safeguarded benefits are worth more than £30,000, you must take regulated advice from an FCA-authorised adviser with the pension transfer permission before the scheme will let you transfer. Read more about what a pension transfer specialist is.
- Not every scheme can transfer to a defined contribution pension. Unfunded public-sector schemes, such as the NHS, Teachers', Police, Firefighters', Civil Service and Armed Forces schemes, have not been able to transfer to a defined contribution pension since April 2015. The Local Government Pension Scheme is funded and can. See our guide to public-sector pensions.
The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. A high CETV does not change that, because the figure mainly reflects how valuable the guaranteed income is.
Could my transfer value change after I decide to transfer?
For a defined contribution pension, yes. Your transfer value usually moves with the markets until your investments are sold and the money is transferred. A market value reduction can apply to some with-profits funds and reduce the amount transferred.
Values can change right up to the point of transfer. Transfers often take a few weeks from the point the paperwork is submitted, and markets can move a lot in that time. Some people ask their provider to switch to cash before a transfer to reduce that risk, but being out of the market also means missing any rises. Ask the provider how its process works.
For a defined benefit pension, the CETV is guaranteed for three months from the guarantee date, as long as you apply to transfer within that period. If the deadline is missed, the scheme will recalculate it.
How is a pension transfer value calculated?
How a transfer value is calculated depends on whether you have a defined contribution or a defined benefit pension.
For defined contribution pensions, the transfer value is usually the current value of your investments, less any exit charges.
For defined benefit schemes, the calculation is more complex and can change considerably over time. CETVs in 2020 and 2021 were unusually high because gilt yields were at historic lows. When yields rose sharply in 2022, many CETVs fell significantly. Our article on how gilt yields affect transfer values explains why.
Defined contribution pensions
Working out the transfer value of a defined contribution pension involves looking at the current fund value and whether any bonuses or charges apply.
Unlike a defined benefit scheme, your pot reflects the contributions made over time plus or minus investment returns.
When you transfer, the transfer value is usually the current value of your investments in the plan.
Some plans, such as with-profits funds, add bonuses on top of the fund value. Final bonuses are not usually guaranteed and can be reduced or withheld when market conditions are poor. Always check the actual transfer value rather than just the fund value.
Some older plans also have valuable guarantees, such as a guaranteed annuity rate or protected tax-free cash, which may be lost on a transfer. Check before you move anything.
Defined benefit pensions
With defined benefit schemes, the calculation is an assessment of a long-term promise rather than a sum of contributions and investment returns.
For a final salary or career average scheme, the transfer value is an estimate of the present value of the guaranteed income you are entitled to, including any increases and spouse's benefits. The scheme's actuary sets the basis, and the trustees use it to work out each member's CETV. Factors include your age, your expected retirement date, life expectancy, gilt yields, the scheme's investment strategy and, in some cases, its funding level.
Trustees can reduce CETVs if the scheme is underfunded, and some schemes have occasionally offered an enhanced transfer value to encourage members to leave. An enhancement does not mean a transfer is a good idea. What matters is whether the transfer value fairly reflects the security and benefits you would be giving up. The Pensions Regulator publishes guidance on incentive exercises.
If you take regulated advice, the adviser must give you a transfer value comparator (TVC). It shows roughly what it would cost to buy the same benefits on the open market, compared with the CETV offered. In many cases the cost of replacing the benefits is more than the CETV.
What a CETV statement usually shows
A CETV statement normally includes:
- The transfer value and its guarantee date.
- The date by which you must apply to transfer to keep the guaranteed figure.
- The pension you have built up and how it increases.
- Whether any reduction has been made because of the scheme's funding.
- Whether you need to take regulated advice before transferring.
Keep the statement alongside your latest benefit statement and scheme booklet. You will need all three if you decide to speak to an adviser.
How long does it take to transfer a pension?
A defined contribution transfer is mostly administration. A defined benefit transfer takes longer, because the law sets a sequence of deadlines: the scheme has up to three months to set your CETV's guarantee date, you have three months from that date to apply in writing, with any required advice in place, and the scheme must normally pay within six months of the guarantee date. Schemes also check for signs of a scam before releasing the money. Our guide to how long a DB pension transfer takes explains each stage and the common causes of delay.
Where is the best place to transfer a pension to?
There is no single "best place" to transfer a pension. Any receiving pension should be judged on its charges, service, investment choices, financial strength and how well it fits your plans for retirement.
It is not enough to choose a provider because you have heard it is good. You need to think about the long-term effect of its charges, the level of service and whether its investment options match the level of risk you are comfortable with.
For defined benefit pensions, the first question is not where to transfer to, but whether you should transfer at all. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. Be very wary of anyone who contacts you out of the blue about your pension or promises high returns. Check the FCA ScamSmart site and the FCA Register before dealing with any firm.
Getting help with a transfer value
A transfer value is only one part of the picture. When thinking about a transfer, it is not just a matter of comparing the fund value with the transfer value. You also need to understand any guarantees, incentives or charges, and the long-term effect on your retirement income.
For free, impartial guidance, contact MoneyHelper. If you have defined contribution pensions and are 50 or over, you can book a free Pension Wise appointment.
If you have a defined benefit pension and want regulated advice, it must come from an FCA-authorised adviser whose firm holds the pension transfer permission. Since 1 October 2020, firms generally cannot charge contingent fees for DB transfer advice, with limited exceptions for serious ill health and serious financial hardship.
If you would like to understand how DB transfers and the advice process work, you can book a free chat about how the process works. It is general information, not advice. Our defined benefit pension guide and how it works page explain more.
Frequently asked questions
What is the transfer value of a pension?
It is the amount your pension scheme or provider would pay into another pension if you moved your benefits. For a defined benefit pension it is called a cash equivalent transfer value (CETV). It is not simply your total contributions: for a DB pension it is based on your accrued benefits, life expectancy assumptions, gilt yields and the scheme rules.
What is the difference between transfer value and fund value?
The fund value is what your savings are worth now. The transfer value is what would actually move to a new pension. For defined contribution pensions these are often similar, but exit charges or market value reductions can make the transfer value lower. Defined benefit pensions have no individual fund; the CETV is an actuarial calculation of what your guaranteed income is worth today.
Is a pension transfer value the same as its cash value?
Not quite. For a defined contribution pension, the transfer value is usually close to the fund value, but exit charges or a market value reduction can make it lower. For a defined benefit pension, the CETV is a cash figure, but it is not money you can normally take yourself: the scheme pays it into another pension. If you then took money from that pension, usually 25% would be tax-free, up to the lump sum allowance, and the rest taxed as income, so what you would actually receive in cash is likely to be less than the CETV. You can't normally take money from a pension before the minimum pension age, which is 55 and rises to 57 on 6 April 2028, unless you have a protected pension age or are retiring early because of ill health.
How is a defined benefit pension transfer value calculated?
The scheme trustees calculate it using assumptions set with the scheme actuary. They estimate the present value of your promised pension, allowing for your age, life expectancy, gilt yields, the scheme's investments and its funding position. When gilt yields fall, transfer values usually rise, and when yields rise, transfer values usually fall.
How long is a CETV guaranteed for?
A CETV is usually guaranteed for three months from its guarantee date. If you do not apply to transfer in that time, the scheme will provide a new figure, which may be higher or lower. You are normally entitled to one free CETV statement every 12 months.
Should I transfer my pension based on the transfer value?
No, not on the transfer value alone. Your overall finances, other income, health, attitude to risk and retirement goals all matter. The FCA's starting assumption is that a defined benefit transfer is unlikely to be suitable for most people. If your safeguarded benefits are worth more than £30,000, you must take regulated advice from an FCA-authorised adviser with the pension transfer permission before you can transfer.
This article is general information, not financial advice. The value of investments can go down as well as up.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read