Guide
Understanding Defined Benefit Transfer Values

A defined benefit (DB) transfer value, or CETV, is the lump sum your scheme will pay if you give up your guaranteed pension and move it elsewhere. Transfer values depend heavily on long-term gilt yields: when yields are low, transfer values tend to be high, and when yields rise, transfer values fall. That is why many transfer values dropped sharply from 2022, after record highs during the pandemic, and why they have generally stayed below those peaks since.
This article was first written in mid-2022, when transfer values were starting to fall. It has been updated to explain what happened, where things stand in 2026, and what that means if you are thinking about your options.
What is a defined benefit transfer value?
A defined benefit transfer value, usually called a Cash Equivalent Transfer Value (CETV), is the amount your pension scheme will pay to another pension arrangement if you give up your right to a guaranteed DB income. It is the scheme's actuarial calculation of what your promised benefits are worth today. Our guide to the transfer value of a pension explains it in detail.
Some useful points:
- you can usually ask for a CETV if you haven't started taking your pension
- the scheme has up to three months to provide a guaranteed statement
- a CETV is guaranteed for three months from its guarantee date
- you are usually entitled to one free statement every 12 months
Why transfer values fell from 2022
For several years before 2022, DB transfer values rose year after year. Gilt yields fell to record lows during the pandemic, and transfer values reached record highs. Some people put off looking at their options in the hope the trend would continue.
That changed in 2022. A gilt is a loan to the UK government that pays a fixed rate of interest. When inflation rose well above the Bank of England's 2% target, the Bank, like many other central banks, began raising interest rates. Gilt yields rose too, sharply at times, including during the market turmoil that followed the September 2022 "mini-budget".
Rising gilt yields reduce transfer values. Schemes use gilt yields, along with other assumptions, to work out today's value of the pension they have promised to pay in future. When yields are higher, the scheme assumes the money it holds can earn more, so it needs less today to pay the same future pension, and the transfer value falls. Our article on how gilt yields affect transfer values explains this in more depth.
People who asked for a new transfer value in 2022, shortly after an earlier quote had expired, often saw a noticeably lower figure. Over the following year or two, many transfer values fell much further than that from their peak.
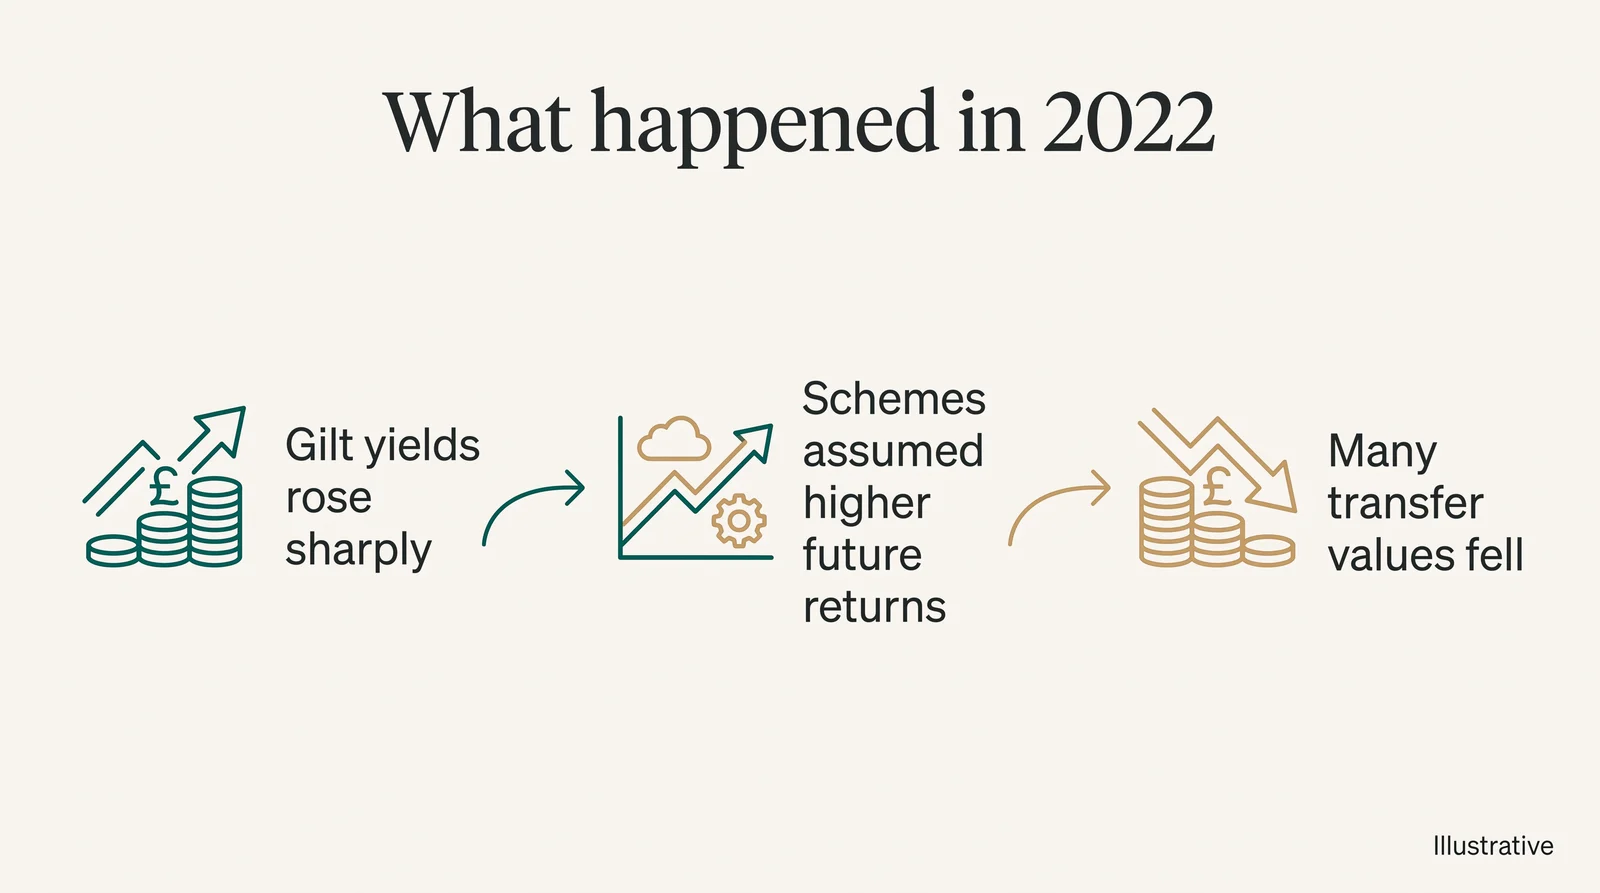
The chart above dates from 2022, when this article was first written. It shows how rising long-term gilt yields went hand in hand with falling transfer values at that time.
Where things stand in 2026
Gilt yields have remained well above the very low levels of 2020 and 2021, so transfer values for most people are still lower than they were at the peak. They do still move, sometimes noticeably, from one quote to the next as markets change.
Trying to predict where transfer values will go next is very difficult. Gilt yields respond to interest rates, inflation, government borrowing and global markets, and none of these can be forecast reliably. The timing of any decision should be based on your own circumstances and needs, not on trying to catch the market.
A lower transfer value also doesn't mean your pension is worth less to you. Your guaranteed income from the scheme is the same as it was. What has changed is the lump sum the scheme will offer in exchange for giving it up.
Inflation and DB pensions
When inflation rose sharply in 2022, some members looked at their "inflation-proofed" schemes and assumed they were fully protected. In practice, most schemes cap the yearly increases they pay. Pensions in payment often rise by inflation up to a limit such as 2.5% or 5% a year, depending on the scheme rules and when the pension was built up. When inflation peaked at over 10% in late 2022, those caps meant many pensions rose by less than prices.
That said, a DB pension still gives a guaranteed income for life that rises each year within those limits, without you taking any investment risk. That protection is very hard and expensive to replicate elsewhere.
Other factors that affect transfer values
Gilt yields are a major driver, but they're not the only one. Other factors include:
- your age and how far you are from the scheme's normal pension age
- the scheme's normal pension age and early retirement terms
- the scheme's increases, both before retirement (revaluation) and once the pension is in payment
- spouse's and dependants' pensions the scheme would pay
- life expectancy assumptions the scheme uses
- the scheme's funding level and investment strategy, and the basis its trustees set for calculating transfer values
Our article on what affects defined benefit transfer values covers these in more detail.
Fewer people transferring, and fewer firms advising
The number of DB transfers has fallen a long way since the late 2010s. Lower transfer values are part of the reason. Another is that many advice firms stopped advising on DB transfers after the FCA tightened its rules, banned contingent charging from 1 October 2020 (apart from limited exceptions for serious ill health or serious financial hardship), and took action over unsuitable advice given in the past. The number of firms with the pension transfer permission has fallen sharply since 2018.
The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. For some people, in particular circumstances, it can be, which is why the advice process exists. If your safeguarded benefits are worth more than £30,000, the law requires you to take advice from an FCA-authorised adviser with the pension transfer permission before you can transfer. You can read more on the FCA's pension transfer pages.
Getting guidance and help
It can feel frustrating to see a transfer value fall by thousands of pounds. But the transfer value is only one side of the comparison. The other is the guaranteed, inflation-linked income for life you would be giving up, and that hasn't changed.
Free, impartial guidance is available from MoneyHelper, and if you're 50 or over you can book a Pension Wise appointment about your DC pensions. Be wary of anyone who contacts you about your pension out of the blue, especially if they tell you to act before transfer values fall further. Check the FCA's ScamSmart pages first.
I don't give pension transfer advice. If it would help, you can book a free, no-obligation chat about how DB transfers and the advice process work. It's general information, not advice. If you then want regulated advice, I can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client. Introductions are for UK residents with a transfer value of £50,000 or more.
Frequently asked questions
Why did defined benefit transfer values fall?
Mainly because gilt yields rose. Schemes use gilt yields as part of the rate they use to work out today's value of your future pension. When yields rise, that present value falls, so the Cash Equivalent Transfer Value (CETV) falls too. Rising inflation and higher Bank of England interest rates pushed gilt yields up from 2022, which brought transfer values down from their pandemic-era highs.
What is a defined benefit transfer value?
A defined benefit transfer value, also called a Cash Equivalent Transfer Value (CETV), is the amount your pension scheme offers in exchange for giving up your right to a future guaranteed pension. It is an actuarial calculation of what your promised benefits are worth today, and it can change significantly with market conditions, particularly gilt yields.
How do gilt yields affect defined benefit transfer values?
They move in opposite directions. When gilt yields rise, transfer values tend to fall, and when gilt yields fall, transfer values tend to rise. During the period of very low gilt yields around the pandemic, transfer values reached record highs. As yields rose from 2022, many transfer values fell significantly.
Will defined benefit transfer values recover?
That depends on what happens to gilt yields and interest rates, which nobody can predict reliably. If yields fall, transfer values would be expected to rise, and if they rise, values would be expected to fall. Any decision about transferring should be based on your circumstances and goals, and on regulated advice where the law requires it, not on trying to time the market. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people.
How do I find out my defined benefit transfer value?
Ask your pension scheme administrator for a Cash Equivalent Transfer Value (CETV). You are usually entitled to one free statement every 12 months, and the scheme has up to three months to provide it. A CETV is guaranteed for three months from its guarantee date. Transferring out of a DB scheme is a significant and usually irreversible decision, and if your safeguarded benefits are worth more than £30,000 you must take regulated advice from an adviser with the pension transfer permission before you can transfer.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read