Guide
Pension Tax-Free Lump Sum: Has It Been Scrapped? (2026 Guide)

No, the pension tax-free lump sum has not been scrapped. You can still usually take up to 25% of your pension tax-free, up to a lifetime limit called the Lump Sum Allowance, which is £268,275 for most people. The rules changed in April 2024 when the Lifetime Allowance was abolished, but the right to tax-free cash itself remains.
Update: this article was first written in 2023, when there was speculation, prompted partly by a report from the Institute for Fiscal Studies (IFS), that the 25% tax-free lump sum could be scrapped or cut. It has been rewritten as a guide to how tax-free cash works today. Tax rules can change at any Budget, so always check the latest position on gov.uk or MoneyHelper.
Key Points
- Pension tax-free cash has not been scrapped. As at October 2026, you can usually take 25% of your pension tax-free.
- Since 6 April 2024, the total tax-free cash most people can take across all their pensions is capped by the Lump Sum Allowance (LSA) of £268,275.
- You can usually take tax-free cash from age 55. This rises to 57 on 6 April 2028, unless you have a protected pension age.
- With a DC pension you can take it all at once or in stages. With a DB pension you usually give up some yearly pension in exchange for a lump sum.
- Speculation before Budgets is common. Taking tax-free cash early because of rumours can cause problems of its own.
What Is Pension Tax-Free Cash?
Pension tax-free cash, formally called a pension commencement lump sum (PCLS), is a lump sum you can take from your pension without paying income tax on it. It's normally taken when you start drawing benefits, which is known as "crystallising" your pension.
For most people, the tax-free amount is up to 25% of the pension being crystallised. The rest of your pension is then used to provide a taxable income, or is taxed as income when you withdraw it.
Tax-free cash is often one of the most valued parts of a pension. People use it to pay off a mortgage or other debts, help family, pay for home improvements or travel, or keep a cash reserve for later in retirement.
How Much Tax-Free Cash Can I Take?
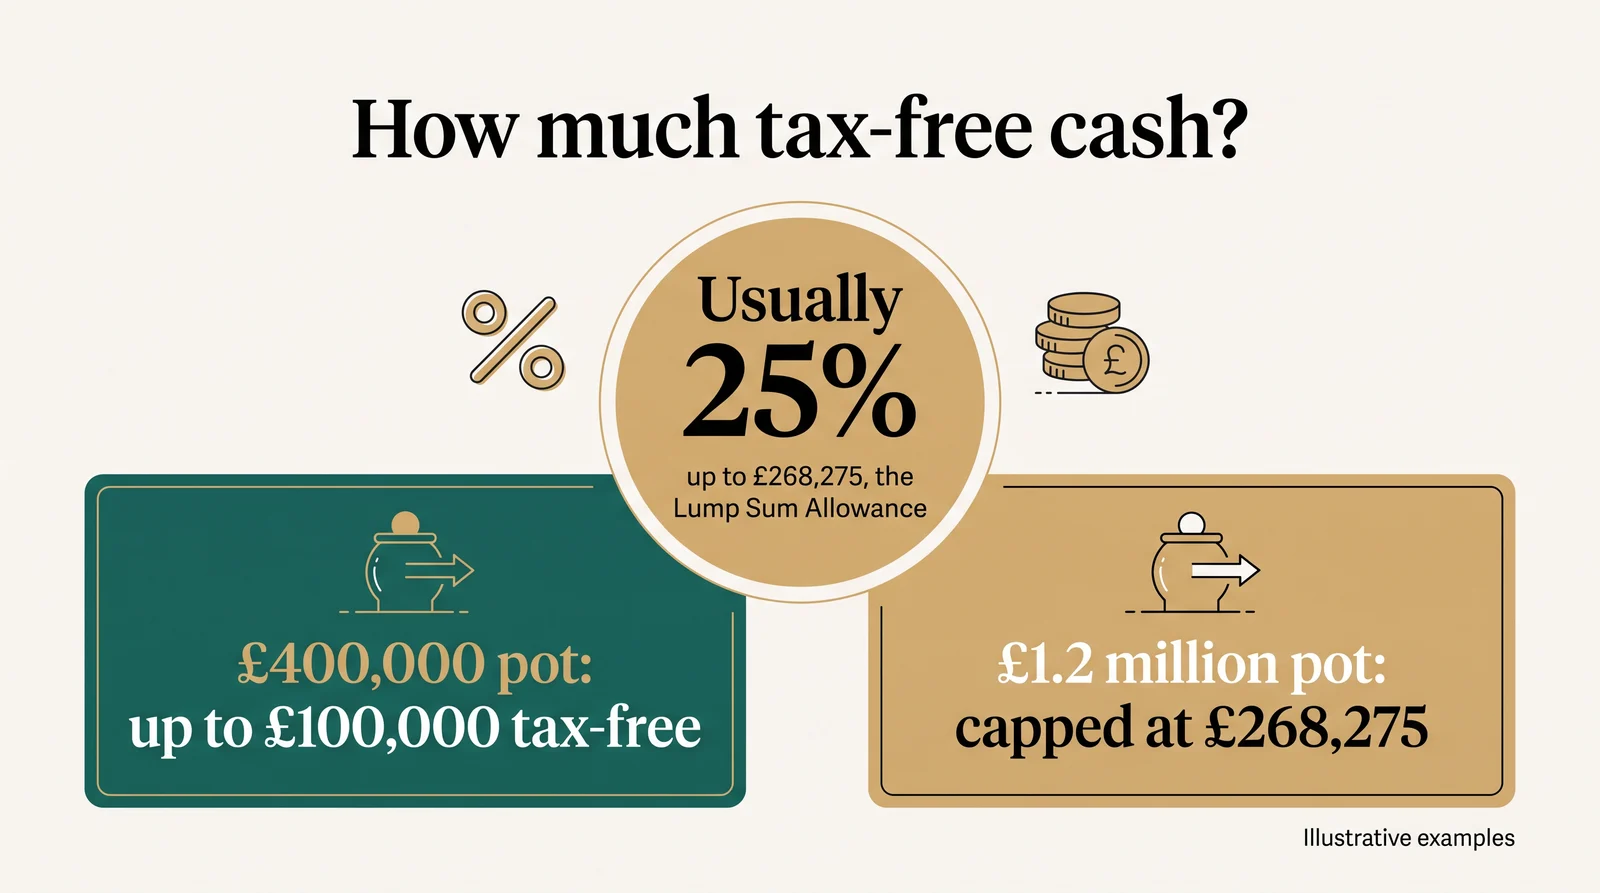
The general rule is 25% of the value of the pension you crystallise, subject to the Lump Sum Allowance.
The Lump Sum Allowance (LSA)
The Lifetime Allowance was abolished on 6 April 2024. It was replaced by two allowances:
- Lump Sum Allowance (LSA): £268,275. This is the total tax-free cash most people can take from all their pensions in their lifetime. It equals 25% of the old Lifetime Allowance of £1,073,100.
- Lump Sum and Death Benefit Allowance (LSDBA): £1,073,100. This limits the total of tax-free lump sums paid in your lifetime and on death before 75.
In practice, if your total pension savings are worth up to about £1,073,100, you can usually take 25% of them tax-free. Above that, your tax-free cash is capped at £268,275 unless you have a protection.
If you took tax-free cash before 6 April 2024, part of your LSA will already have been used up. Your pension provider can tell you how much you have left, and in some cases a transitional tax-free amount certificate can give a more accurate figure.
Higher Limits for Some People
Some people have a higher LSA because they hold one of the old Lifetime Allowance protections, such as fixed protection or individual protection. Some older pension schemes also have scheme-specific protected tax-free cash above 25%. If you think this applies to you, check with your provider before you take any benefits, as protected rights can be lost if a pension is transferred in the wrong way. gov.uk explains the main allowances.
Tax-Free Cash From a DC Pension
If you have a defined contribution (DC) pension, such as a personal pension, SIPP or workplace pension pot, there are several ways to take your tax-free cash.
All at Once
You can crystallise your whole pot, take 25% as a tax-free lump sum, and move the rest into drawdown or use it to buy an annuity. The income you take afterwards is taxed.
In Stages (Phased Drawdown)
You don't have to take all your tax-free cash in one go. You can crystallise part of your pot at a time. Each time, up to 25% of the part you crystallise can be paid tax-free and the rest moves into drawdown. This can spread your tax-free cash over several years, which some people use to top up their income while keeping their taxable income low.
Uncrystallised Funds Pension Lump Sum (UFPLS)
Instead of a single tax-free lump sum, you can take lump sums directly from your pot. Each time, 25% of the payment is tax-free and 75% is taxed as income. The UFPLS route is simple, but you can't use it if you have certain protections, and the taxable part counts as income in the tax year you take it.
Watch out for the Money Purchase Annual Allowance (MPAA). Taking only your tax-free cash and moving the rest into drawdown doesn't trigger the MPAA. But taking taxable income flexibly, including through a UFPLS, does. Once triggered, you can only pay £10,000 a year into DC pensions with tax relief.
Tax-Free Cash From a DB Pension
Defined benefit (DB), or final salary, pensions work differently. Most DB schemes let you give up part of your yearly pension in exchange for a tax-free lump sum. This is called commutation.
- Each scheme sets a commutation factor: the amount of lump sum you get for each £1 of yearly pension you give up. For example, the Local Government Pension Scheme uses £12 for each £1 of pension. Private sector schemes set their own factors, which vary.
- HMRC rules limit the maximum tax-free cash from a DB pension, broadly so it is no more than 25% of the total value of the benefits, using HMRC's valuation method. The scheme will tell you the maximum it can pay.
- Some public sector schemes, and older sections of others, pay an automatic lump sum as well as a pension.
- Taking the maximum lump sum reduces your guaranteed income for the rest of your life, and often any spouse's pension too. Whether that trade is worth it depends on the scheme's factor and your needs.
Some people wonder whether transferring a DB pension to a DC pension would give them more tax-free cash. Sometimes it would, but it means giving up a guaranteed, inflation-linked income for life. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. If your safeguarded benefits are worth more than £30,000, the law requires you to take advice from an FCA-authorised adviser with the pension transfer permission before you can transfer. Our guide to defined benefit pensions explains what you would be giving up.
If your pension has a guaranteed annuity rate, taking tax-free cash can affect the value of that guarantee. Our page on guaranteed annuity rates explains more.
At What Age Can I Take Tax-Free Cash?
You can usually take your pension, including your tax-free cash, from the normal minimum pension age, which is currently 55.
- The normal minimum pension age rises from 55 to 57 on 6 April 2028.
- If you were born on or after 6 April 1973, you won't reach 55 before the change, so you will generally need to wait until 57.
- Some people have a protected pension age under their scheme's rules, which can allow earlier access. Ask your scheme whether this applies to you.
- If you are too ill to work, you may be able to take your pension early on ill-health grounds.
Be very wary of anyone offering to help you get at your pension before the minimum age. That is a common sign of a scam, and unauthorised payments can lead to tax charges of 55% or more. Check the FCA's ScamSmart pages if anyone approaches you.
Do I Need to Take All My Tax-Free Cash at Once?
No. With a DC pension, you can take it in stages through phased drawdown or UFPLS, as described above. This lets you:
- Take cash only when you need it, leaving the rest invested
- Manage the income tax on your taxable withdrawals
- Keep flexibility for later in retirement
With a DB pension, you usually have to decide how much lump sum to take when the pension starts. You can't normally come back for more tax-free cash later.
What Happens to Tax-Free Cash After Age 75?
Since 6 April 2024, the tax-free cash rules are based on your remaining Lump Sum Allowance rather than a test at age 75. Many providers allow you to take tax-free cash after 75, but not all do, so check with your provider.
If you die before 75, your beneficiaries can usually receive lump sums from your pension free of income tax, within your remaining LSDBA. If you die at 75 or over, anything they take is usually taxed as their income. From 6 April 2027, unused pension funds and most pension death benefits are also due to come into the scope of inheritance tax. Our article on the 2027 pension IHT overhaul explains the change.
Will Tax-Free Cash Be Scrapped?
There has been speculation about tax-free cash before many recent Budgets. As at October 2026, the 25% tax-free lump sum and the Lump Sum Allowance remain in place.
What the IFS Proposed
In February 2023, the Institute for Fiscal Studies published A Blueprint for a Better Tax Treatment of Pensions, which you can read on the IFS website. Among other reforms, it argued that:
- the current tax-free lump sum mostly benefits people with larger pensions, who are often higher earners
- the tax-free lump sum could be capped, for example at 25% of the first £400,000 of pension wealth, so a maximum of £100,000, to spread the tax support more evenly
- any change should be introduced in a way that protects existing expectations
The report also looked at income tax relief on contributions, National Insurance on employer contributions and the tax treatment of pensions on death. It was a proposal from an independent research body, not government policy.
Why a Sudden Change Would Be Difficult
In my experience, tax-free cash is one of the questions people ask about most, and many people have it earmarked for something specific, such as clearing a mortgage. People often plan how they will use it at least five years before they retire.
Because it affects so many people, from basic-rate to higher-rate taxpayers, abolishing tax-free cash outright would be a very significant step for any government. A more likely type of change, if one ever came, would be a reduction in the limit or a change that applies only to future savings. No one can rule out changes at a future Budget, but it's worth keeping speculation in proportion.
Don't Act in a Hurry on Rumours
Before recent Budgets, some people took their tax-free cash early as a precaution. That can have downsides:
- Money taken out of a pension usually counts towards your estate for inheritance tax.
- Cash held outside the pension may earn less than it would if it stayed invested, and interest on it may be taxable.
- Once taken, tax-free cash usually can't be put back into a pension with fresh tax relief. HMRC's "recycling" rules can apply a tax charge if you take tax-free cash and use it to make significantly larger pension contributions.
- Taking benefits from a DB pension early usually means a reduced pension for life.
If you're thinking about taking tax-free cash, base the decision on your own needs and plans, and take guidance or advice first.
Getting Help
Free, impartial guidance on taking your pension is available from MoneyHelper, and if you're 50 or over you can book a free Pension Wise appointment about your DC pensions. Be wary of anyone who contacts you out of the blue about your pension, and check the FCA's ScamSmart pages first.
I don't give pension transfer advice. If you have a DB pension and want to understand how transfers and the advice process work, you can book a free, no-obligation chat. It's general information, not advice. If you then want regulated advice, I can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client. Introductions are for UK residents with a transfer value of £50,000 or more. Below that, MoneyHelper is a good place to start. You can read more about how it works.
This article is general information, not tax or financial advice. Please read our important information.
Frequently asked questions
Has the pension tax-free lump sum been scrapped?
No. As at October 2026, you can still usually take up to 25% of your pension tax-free. Since 6 April 2024, the total most people can take across all their pensions is capped by the Lump Sum Allowance of £268,275. Tax rules can change at future Budgets, so check gov.uk for the latest position.
What is pension tax-free cash?
Pension tax-free cash, also called a pension commencement lump sum (PCLS), is a lump sum you can take from your pension without paying income tax. It's usually up to 25% of the pension you crystallise, subject to the Lump Sum Allowance. The rest of your pension is taxed as income when you take it.
How much tax-free cash can I take from my pension?
Usually up to 25% of your pension, subject to the Lump Sum Allowance of £268,275 for most people. In practice, that means 25% of pension savings up to about £1,073,100. Some people have a higher allowance because of earlier protections. DB schemes usually provide tax-free cash by letting you give up some yearly pension in exchange for a lump sum, using the scheme's commutation factors.
Can I take tax-free cash after age 75?
Since 6 April 2024, the limits on tax-free cash are based on your remaining Lump Sum Allowance rather than a test at 75. Many providers let you take tax-free cash after 75, but not all, so check with yours. If you die at 75 or over, lump sums paid to your beneficiaries are usually taxed as their income.
Should I take my pension tax-free cash all at once?
It depends on your needs, tax position and plans. With a DC pension, you can take it all at once or in stages, through phased drawdown or UFPLS. Taking it in stages can help manage tax and keep money invested. With a DB pension, you usually choose your lump sum when the pension starts. MoneyHelper and Pension Wise can help you understand your options, and a regulated financial adviser can advise on your own situation.
When can I take my tax-free cash?
Usually from 55, rising to 57 on 6 April 2028. If you were born on or after 6 April 1973, you will generally need to wait until 57, unless your scheme gives you a protected pension age. You may be able to take your pension earlier if you are too ill to work.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read