Guide
Final salary pension transfer advice

Final salary pension transfer advice is regulated advice from an FCA-authorised firm with the pension transfer permission, and the law requires it before you can transfer safeguarded benefits worth more than £30,000. Since 1 October 2020, firms have not been allowed to charge only if the transfer goes ahead, so you should expect to pay for the advice whatever it concludes. I don't give this advice myself, but this guide explains how it works and how it is typically charged.
What is final salary pension transfer advice?
If you want to transfer a final salary (defined benefit) pension, you usually need advice from an FCA-authorised firm that holds the pension transfer permission. The advice must be given or checked by a qualified pension transfer specialist. You can read more about the role in What is a pension transfer specialist?
The adviser's job is to give you a personal recommendation on whether a transfer is in your best interests. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people, so many recommendations are to keep the final salary pension.
To start the process, you normally need a Cash Equivalent Transfer Value (CETV) from your scheme. See our guide to the transfer value of a pension.
How do I know if I have a final salary pension?
Final salary and other defined benefit pensions promise a guaranteed income in retirement. In pension law they are called safeguarded benefits. They are different from defined contribution pensions, where your retirement income depends on how much is in your pot and how it is invested.
A final salary pension builds up based on your years of service and your earnings. In a final salary scheme, your pension is based on your salary at or near retirement or leaving; in a career average scheme, it is based on your average earnings over your membership.
If you are an active member, you may pay contributions from your salary, but it is the employer's responsibility to make sure there is enough money in the scheme to pay everyone's benefits. The investment risk sits with the scheme and employer, not with you, which is the reverse of a defined contribution pension.
Your scheme should send you regular statements showing your expected pension at the scheme's normal pension age. This is often 60 or 65. A few schemes allow some members to take benefits earlier under a protected pension age. The normal minimum pension age for most people is 55 now and is due to rise to 57 on 6 April 2028, unless you have a protected pension age.
If you are still an active member, your pension keeps building up. If you are a deferred member (you have left the scheme but not yet taken your pension), your pension is usually increased each year between leaving and retirement in line with the scheme's revaluation rules.
Unfunded public-sector schemes, such as the NHS, Teachers', Police, Firefighters', Civil Service and Armed Forces schemes, cannot be transferred to a defined contribution pension, and haven't been able to since April 2015. See our guide to public sector pensions.
Why do people consider a final salary pension transfer?
The Pension Schemes Act 2015 introduced the requirement to take advice before transferring safeguarded benefits worth more than £30,000, alongside the pension freedoms that gave people more ways to use defined contribution pots. In the years that followed, many people transferred out of final salary schemes.
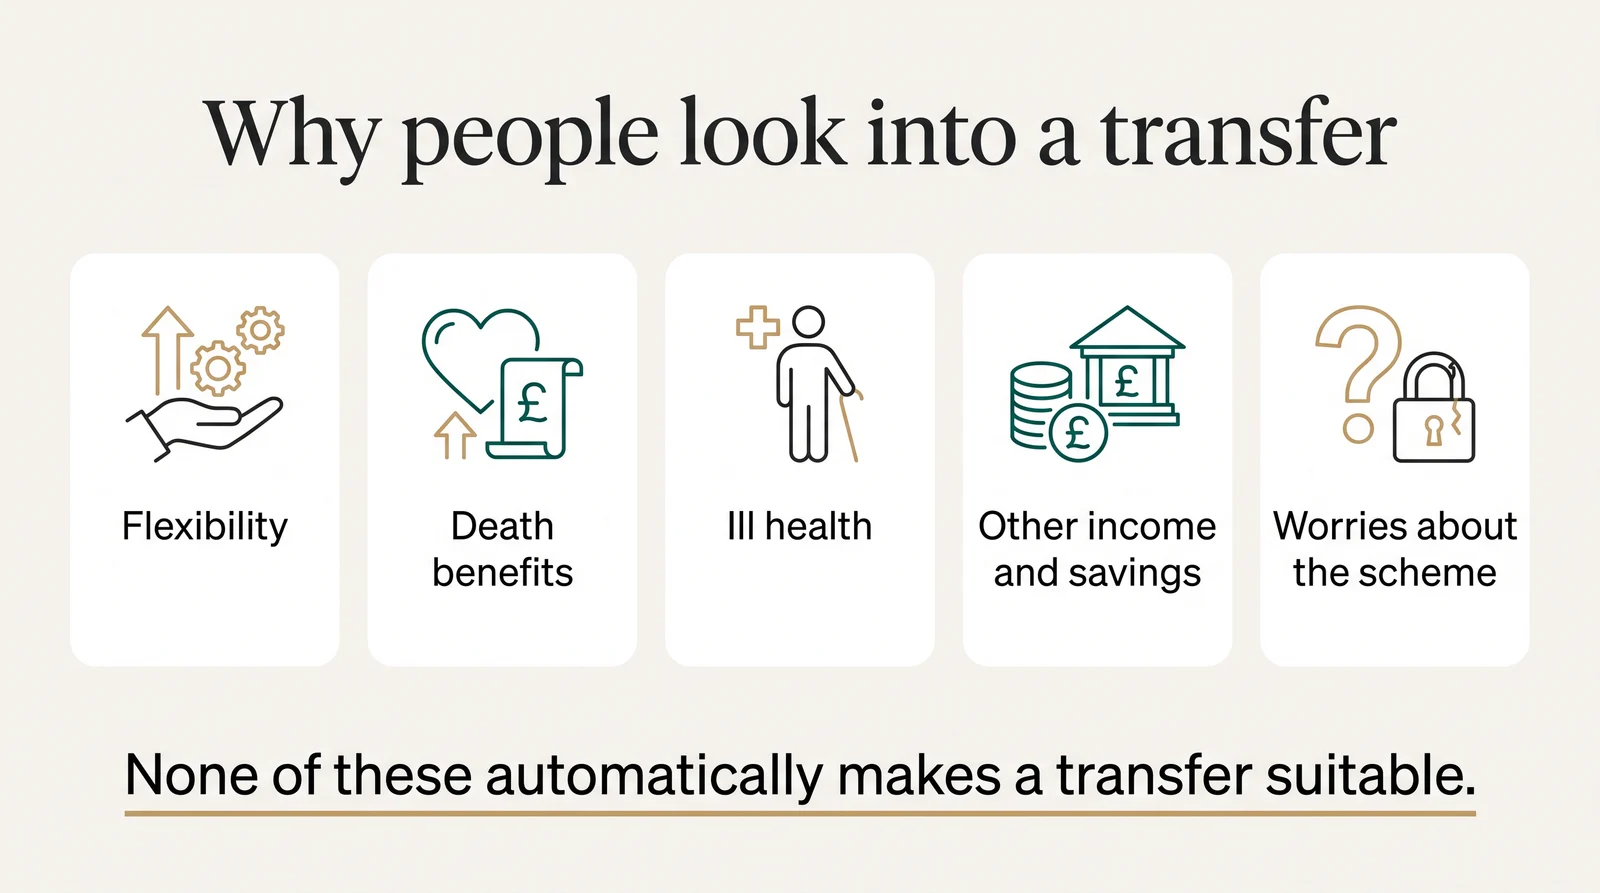
Final salary pensions are a very good source of retirement income for the vast majority of members. The reasons below are ones people often raise. None of them automatically makes a transfer suitable, and an adviser has to look at whether your goals could be met without giving up your guarantees.
Common reasons people raise
Income they may not need
Some people have several pensions by the time they retire and feel they won't need the income from one of their final salary schemes.
If retirement spending can be met from other pensions and the State Pension, extra income from another scheme may push someone into a higher income tax band, such as from 20% to 40%.
In the past, people also pointed to inheritance tax, because unused defined contribution pension funds were usually outside the estate. From 6 April 2027, unused pension funds and most death benefits are due to come into the scope of inheritance tax, so this argument is much weaker than it was. See our 2027 pension IHT guide.
Having other savings or investments
Some people have large savings in ISAs, cash or other investments, or income from property or dividends, and feel they don't need their final salary income. An adviser will look at the whole picture, including whether a secure, inflation-linked income is still valuable as a foundation.
Ill health
Someone whose life expectancy has been shortened by serious illness may want to use their pension differently, or leave more to their family. This is one of the situations where a regulated adviser may find a transfer worth looking at closely. Many schemes also offer ill-health or serious ill-health options, which should be checked first. There are also tax rules that can apply when someone in serious ill health transfers a pension and dies within two years, so specialist advice on the current position is essential.
Flexibility
Flexibility is one of the most common reasons people give. To recommend a transfer on this basis, an adviser would need to understand exactly what flexibility you need:
- What does flexibility mean for you?
- How much do you need, and when?
- Could the final salary scheme, perhaps with other savings, meet those needs? If so, a transfer is unlikely to be suitable.
People often say they want flexibility without being sure how flexible their income needs to be, or why.
Worries about the scheme
Many final salary schemes have had funding deficits at some point, and employers pay extra contributions to close the gap. Scheme funding has improved for many schemes since gilt yields rose in 2022, but it varies.
If a scheme's sponsoring employer fails and the scheme can't pay full benefits, the Pension Protection Fund (PPF) generally steps in. It usually pays 100% of the pension for members who have reached the scheme's normal pension age, and 90% for those who have not, with its own rules on future increases. For most people, PPF protection means worry about the employer alone is not a strong reason to transfer. See What happens to your DB pension if your employer goes bust?
The benefits of a final salary pension
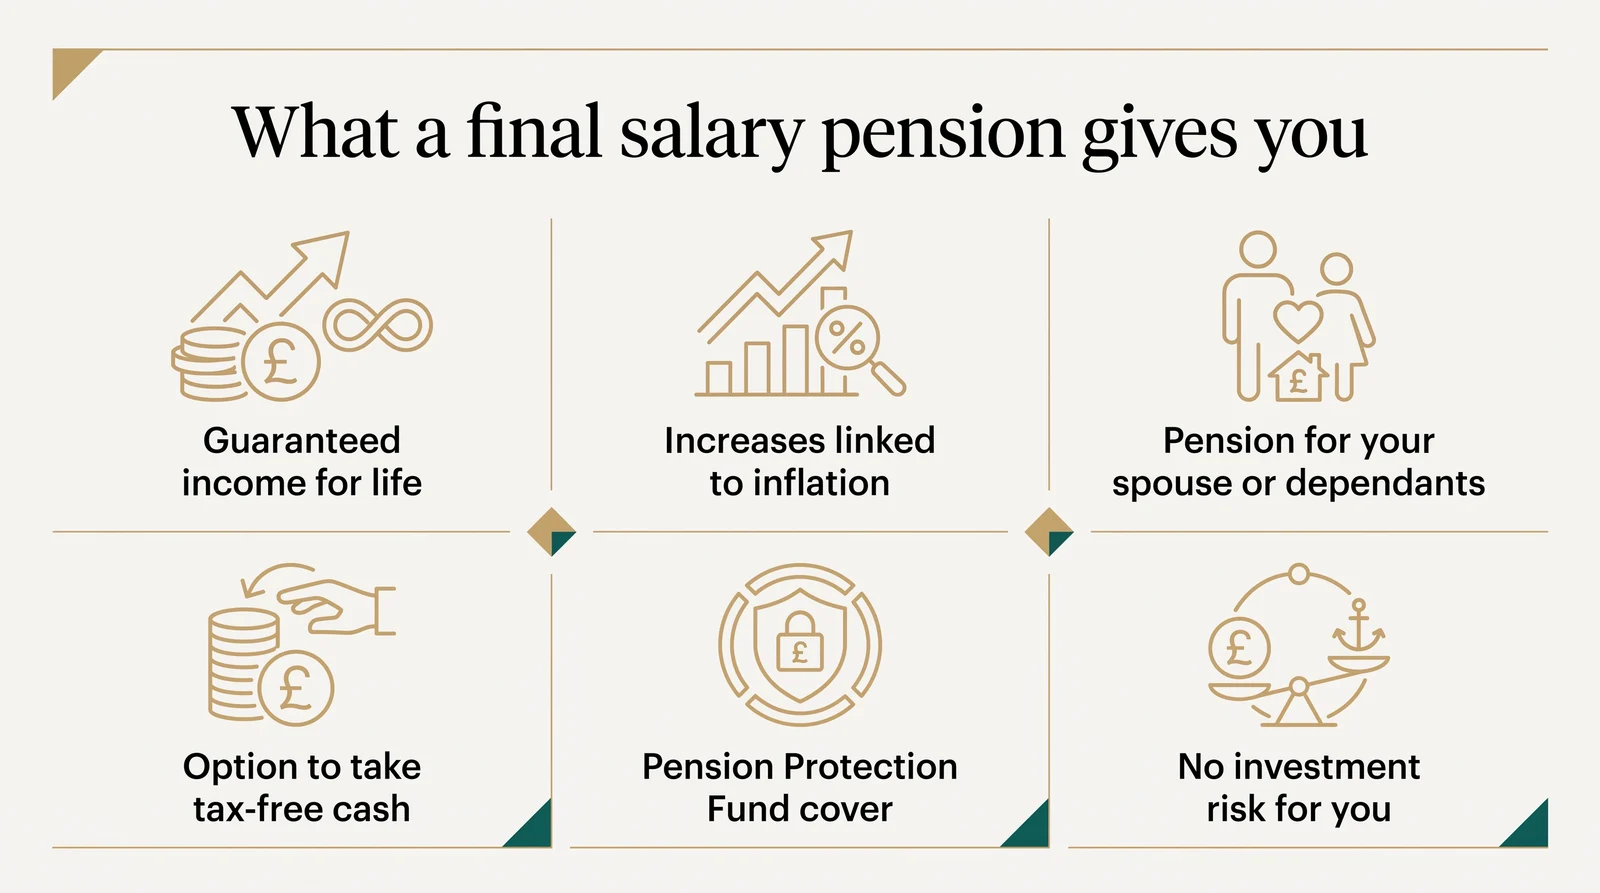
A final salary pension has many benefits that are easy to overlook when thinking about a transfer.
Your retirement income is based on your years in the scheme and your earnings, not on stock market performance. The investment risk is taken by the employer and scheme, not by you.
Most final salary schemes also include increases linked to inflation, which help your income keep its spending power as you get older.
Schemes have different forms of inflation protection. Some parts of your pension may increase by a fixed rate, and others with inflation up to a cap such as 5% or 2.5%. Different parts of your pension, built up at different times, may increase at different rates.
Death benefits are also valuable. If you die before or after retirement, your spouse, civil partner or dependants may receive a pension, often linked to the pension you were entitled to.
A common arrangement is a spouse's pension of 50% of your pension. If you were receiving £10,000 a year when you died, your spouse might receive £5,000 a year, usually with inflation increases, for the rest of their life. Some schemes also pay children's pensions while they are in full-time education, or for life if they have a qualifying disability.
Most schemes have a normal pension age, but you can usually take your pension early if you accept a reduction. The reduction reflects the fact that the pension will be paid for longer.
At retirement, schemes usually quote two main options:
- Full pension
- Tax-free cash and a reduced pension
The full pension option gives the highest lifetime income.
The tax-free cash option means giving up some pension in return for a lump sum. The quoted figure is usually the maximum, but you can normally choose any amount up to it. Tax-free cash is generally limited to 25%, up to the Lump Sum Allowance of £268,275, following the abolition of the Lifetime Allowance from 6 April 2024.
The risks of transferring a final salary pension
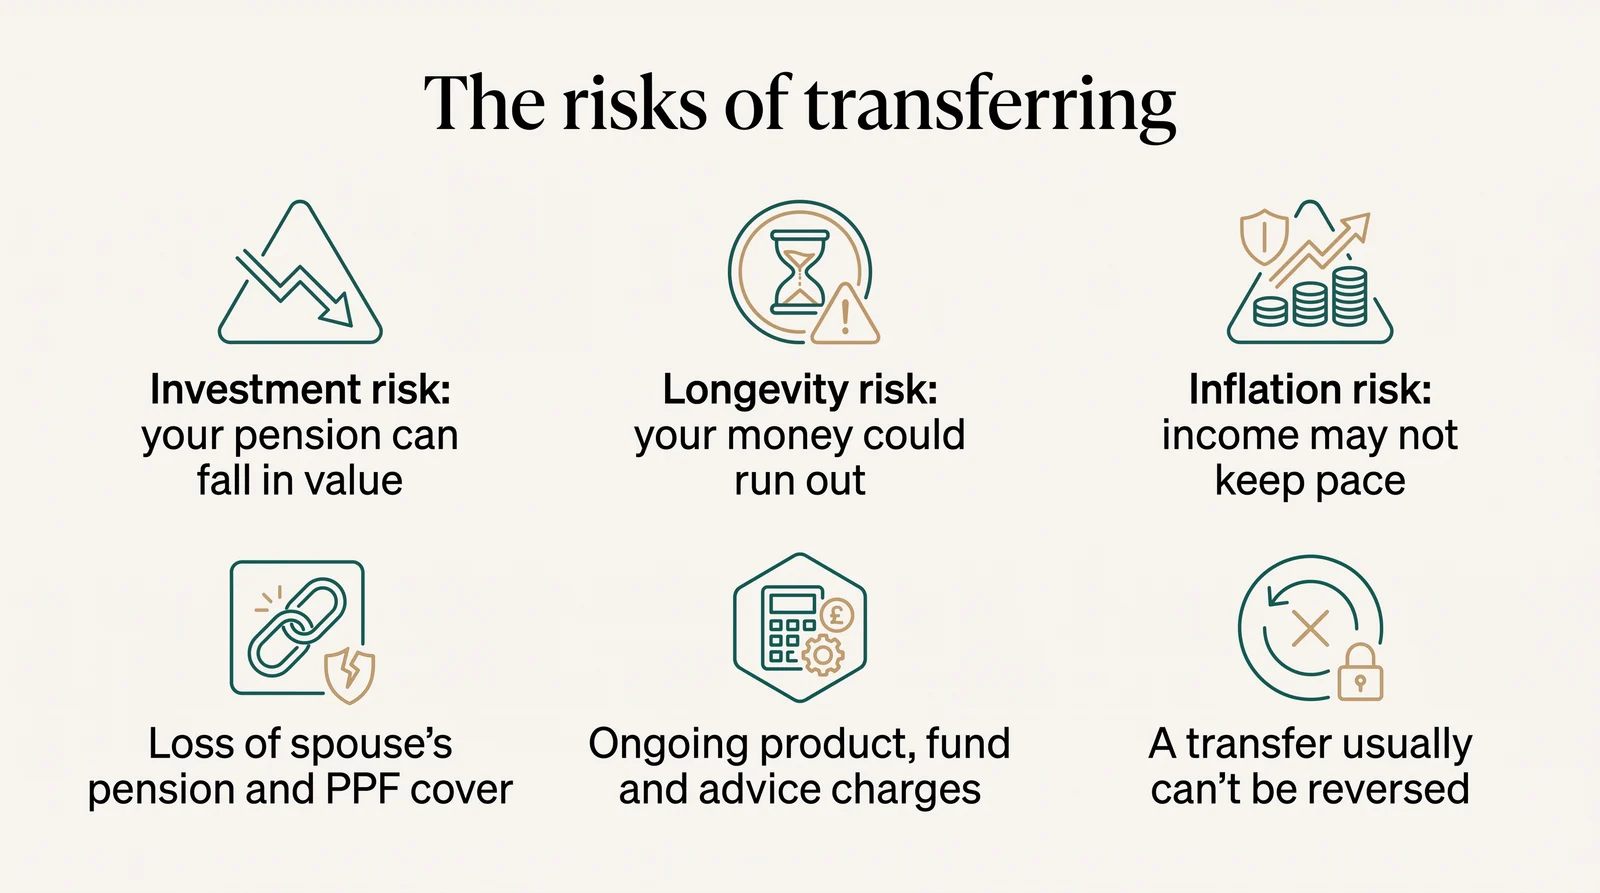
Transferring a final salary pension comes with risks that should be considered carefully before giving up these benefits.
Investment risk
In a final salary scheme, the investment risk sits with the scheme. It is for the trustees and the employer to make sure there is enough money to pay everyone's pension for life. Once you transfer, the investment risk moves to you. If investments perform poorly, or money is withdrawn too quickly, you could run out of money in later life. There is no safety net.
Longevity risk
A final salary pension pays an income for life, whether you live to 75 or 105, usually with inflation increases. That removes the risk of running out of money.
Once a pension is transferred, it has to be managed for the rest of your life. If too much is spent in the early years, there is a risk of running short later, which could affect your standard of living or how you pay for care.
Few people can spend their last pound the day before they die. Some hold back too much and leave more than they expected; others draw too much. A final salary pension removes the worry of managing a pot of money to the end.
Loss of other benefits
You would also give up any spouse's and dependants' pensions, PPF protection and any other scheme-specific benefits, and you would pay ongoing product, fund and possibly advice charges.
How is final salary pension transfer advice charged?
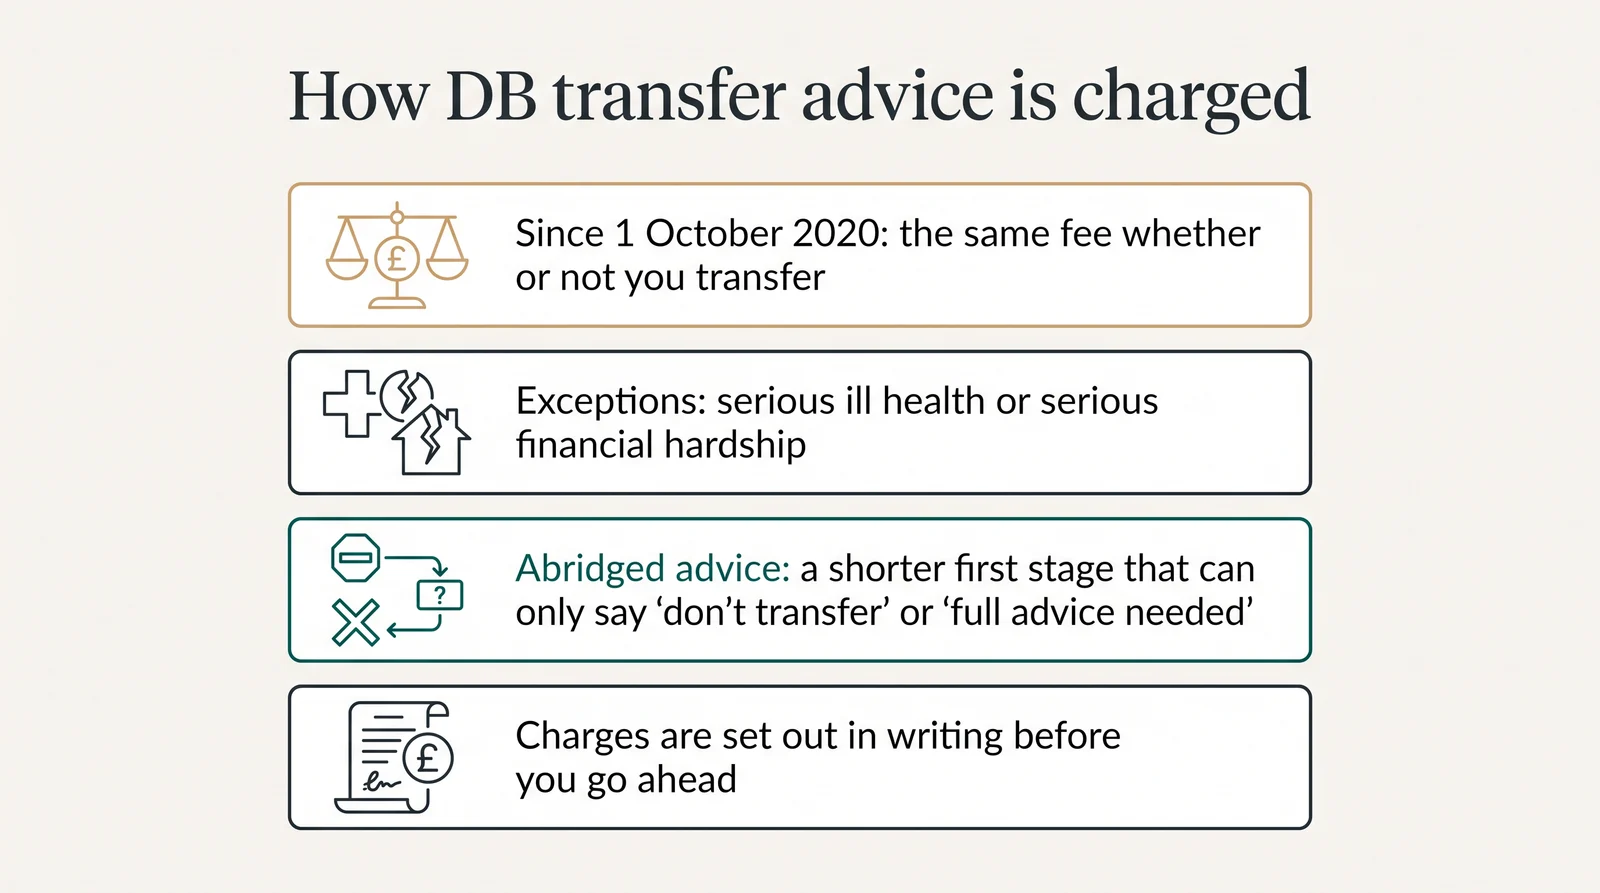
This section explains, in general terms, how firms with the pension transfer permission typically charge for advice. We don't give this advice, and charges vary between firms, so always ask for a written explanation of costs before you agree to anything.
The ban on contingent charging
Before October 2020, some firms only charged if a transfer went ahead, often taking the fee from the new pension. The FCA was concerned this created a conflict of interest, because the adviser was only paid if they recommended a transfer.
From 1 October 2020, the FCA banned contingent charging for DB transfer advice. Firms must charge the same amount for the advice whether the recommendation is to transfer or to stay. There are limited carve-outs for people in serious ill health or serious financial hardship, where a firm may still charge on a contingent basis if strict conditions are met. You can read more about the rules on the FCA website.
In practice, this means you should expect to pay for full advice even if the adviser recommends keeping your final salary pension. Ask the firm how the fee must be paid, as it may need to come from your own money rather than from a pension.
Abridged advice
The FCA also introduced abridged advice, a shorter first stage of advice. Abridged advice can only conclude that you should not transfer, or that it is unclear and full advice is needed. It cannot recommend a transfer. Some firms offer it at a lower cost than full advice, and some offer it free of charge. We don't provide abridged advice.
Fixed fees and percentage fees
Firms with the pension transfer permission use different charging structures. Common approaches include:
- A fixed fee for the advice, agreed in advance
- A fee based on a percentage of the transfer value, sometimes with a minimum and maximum
- A combination, such as a fixed fee for the initial analysis and report plus a further amount if more work is needed
- Hourly rates for some or all of the work
Whatever the structure, the fee for full advice must not depend on whether you transfer. Ask what is included, such as obtaining scheme information, the Appropriate Pension Transfer Analysis (APTA), the Transfer Value Comparator (TVC) and the suitability report.
Ongoing costs if you transfer
If you go ahead with a transfer, there are usually further costs: product or platform charges, fund charges and often an ongoing advice charge. Ask for these in writing, in pounds as well as percentages, and ask how they compare with keeping your final salary pension, which has no investment charges for you to pay. The adviser must also consider whether your existing workplace pension could be a suitable place to receive a transfer.
Questions to ask about fees
- How much will advice cost, and is that the same whatever you recommend?
- Do you offer abridged advice, and how much does it cost?
- How and when must the fee be paid?
- What are the ongoing charges if I transfer, in pounds each year?
- Do I qualify for any of the carve-outs, and how would they work?
MoneyHelper has general information on paying for financial advice at moneyhelper.org.uk.
How long could a final salary pension transfer take?
Moving from a final salary scheme to a defined contribution pension isn't quick. When you receive a CETV, it is guaranteed for three months from the guarantee date. You are usually entitled to one free statement every 12 months.
The adviser has to understand your circumstances, goals, finances and plans, as well as your scheme. When the adviser asks your scheme for information, it can take several weeks to reply, which uses up part of the three-month guarantee period.
A common misunderstanding is that the money must move within three months. In general, what matters is that your application to transfer, with the required evidence of advice, reaches the scheme within the guarantee period. Trustees then generally have up to six months from the guarantee date to pay the transfer, although many act sooner. Schemes also carry out checks to help protect members from scams, which can add time.
From first contacting an adviser to the money arriving in a new pension commonly takes a few months, though it can be quicker or slower.
What went wrong with pension transfer advice in the past?
Most advisers act properly, but there have been serious problems. Before the contingent charging ban, some advisers were only paid if a transfer went ahead, which created a conflict of interest.
The best-known example involved members of the British Steel Pension Scheme (BSPS). During the scheme's restructuring in 2017, members were asked to choose between moving to a new scheme, entering the PPF or transferring out. Some members were given unsuitable advice to transfer, sometimes after hard-selling. The FCA later introduced a consumer redress scheme in 2023 for affected BSPS members. You can read more in our article on the FCA review of redress for unsuitable transfer advice.
Transferring a final salary pension shouldn't be a quick decision, and it should never be pushed on you. If you don't understand your scheme benefits or what you would be giving up, that is a clear sign to slow down.
Decisions made under pressure can't be reversed, and compensation rarely puts things fully right.
The FCA has tightened its rules considerably since then. It is still worth being careful:
- Check that any firm holds the pension transfer permission on the FCA Register
- Never respond to cold calls about your pension
- Take your time, and don't invest in anything that sounds too good to be true or that you don't understand
- Read the FCA's ScamSmart guidance
Getting help
MoneyHelper offers free, impartial guidance on pensions, and Pension Wise offers free appointments about defined contribution pension options for people aged 50 or over.
I don't give pension transfer advice, and Arthur Browns does not hold the pension transfer permission. I offer a free, no-obligation chat that gives general information about how DB transfers and the advice process work, including how advice is usually charged. If you want regulated advice, I can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client. Introductions are for transfer values of £50,000 or more; below that, MoneyHelper is a good place to start. You can book a free chat about how the process works or read how it works.
Frequently asked questions
What is final salary pension transfer advice?
It is regulated financial advice from an FCA-authorised firm with the pension transfer permission, given or checked by a qualified pension transfer specialist. It looks at whether transferring your final salary pension is in your best interests. The law requires it before you can transfer safeguarded benefits worth more than £30,000.
How much does pension transfer advice cost?
Charges vary between firms. Common structures are a fixed fee, a percentage of the transfer value, or a combination. Since 1 October 2020, firms must charge the same for advice whether or not they recommend a transfer, except in limited cases of serious ill health or serious financial hardship. Always ask for costs in writing before you start.
What is contingent charging?
Contingent charging means only charging for advice if the transfer goes ahead. The FCA banned it for DB transfer advice from 1 October 2020, with carve-outs for serious ill health and serious financial hardship, because it created a conflict of interest.
What is abridged advice?
Abridged advice is a shorter first stage of advice. It can only conclude that you should not transfer or that full advice is needed. It cannot recommend a transfer. We don't provide it.
Why might someone consider a final salary pension transfer?
Reasons people raise include having income they may not need, wanting flexibility, ill health, death benefits or concerns about the employer. None of these automatically makes a transfer suitable, and the FCA's starting assumption is that a transfer is unlikely to be suitable for most people.
What are the risks of transferring a final salary pension?
Key risks include investment risk, longevity risk (running out of money), and losing a guaranteed income, inflation increases, spouse's pension and PPF protection. A transfer cannot be reversed.
How long does a final salary pension transfer take?
It commonly takes a few months from start to finish. A CETV is guaranteed for three months from the guarantee date, and trustees generally have up to six months from that date to pay the transfer. Advice, scheme information requests and scam checks can all add time.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read