Guide
Can I retire at 55?

The short answer: You can usually take money from a private pension at 55 today, but the minimum age rises to 57 on 6 April 2028 unless you have a protected pension age. Whether you can afford to stop work at 55 depends on your savings, the income you need and your scheme's own rules.
Yes, you can usually take money from a personal or workplace pension from age 55, but the normal minimum pension age rises to 57 on 6 April 2028. Whether you can actually afford to stop work at 55 depends on how much you have saved, what income you need, how long it has to last and, if you have a final salary pension, what your scheme's own rules allow.
Can I retire at 55?
Many people work towards stopping at 55, well before State Pension age. Retiring early is possible, but it needs careful planning and an honest look at your finances. Your pensions and savings may need to support you for 30 years or more, and the decisions you make now about saving, investing and spending will shape those years.
This guide explains when you can draw your pension, how the rise to 57 works, what a protected pension age is, how defined benefit (final salary) pensions fit in, and the main things to think about before you set a date.
Key takeaways
- You can currently access most private pensions from 55. The normal minimum pension age (NMPA) rises to 57 on 6 April 2028.
- Some people have a protected pension age, which lets them keep an earlier access age. It depends on your scheme's rules and can be lost on a transfer.
- Defined benefit (final salary) schemes have their own retirement age. You can often take the pension early, but it will usually be reduced.
- Drawing a pension early has tax consequences and longevity risk, so it is worth looking at options such as deferring, phasing your retirement or working part-time.
- Work out the income you need for the lifestyle you want, allowing for inflation and any other income or savings.
- Free, impartial guidance is available from MoneyHelper and, if you are 50 or over with a defined contribution pension, from Pension Wise.
Can I draw my pension at 55?
Yes. At the moment you can usually access your pension from 55, but this rises to 57 from 6 April 2028.
If you have a defined contribution pension (a pension pot), you can take just the tax-free cash if you wish, or combine it with a taxable income or lump sums. If you have a defined benefit pension, you may be able to take it early, but the income will usually be reduced to reflect that it is being paid for longer, and you normally take the income and any tax-free cash at the same time.
To avoid a shortfall later in life, it is worth exploring every option, such as deferring your pension, phasing it in, or continuing to work part-time.
What is the normal minimum pension age (NMPA)?
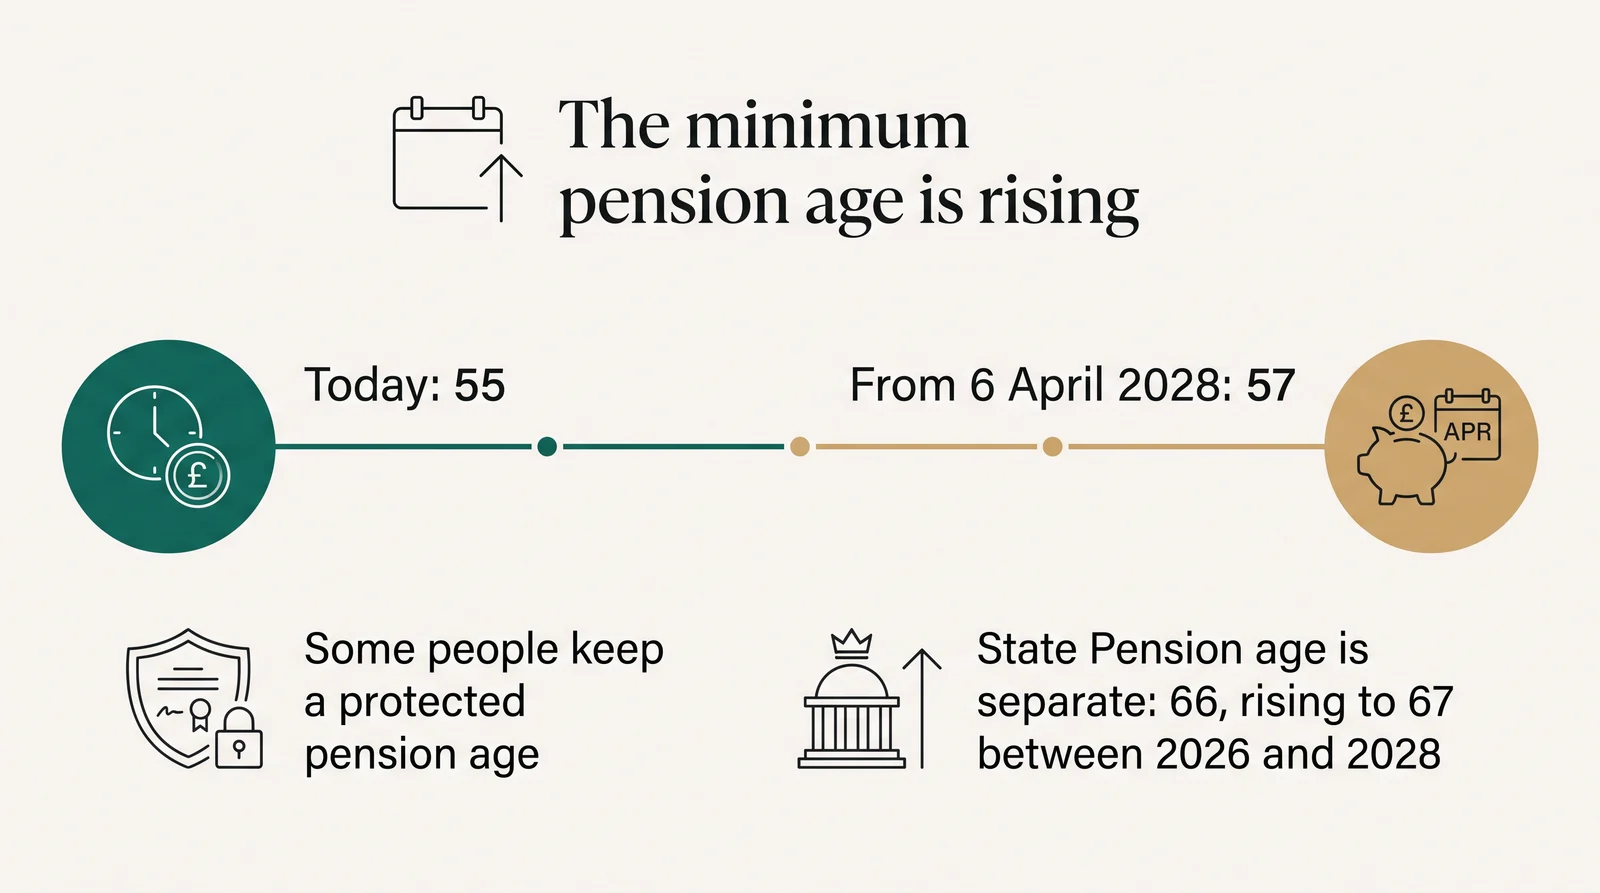
The NMPA is the earliest age at which most people can take money out of a private pension, as a lump sum or as income, without facing an unauthorised payment tax charge. It is currently 55.
The NMPA is not fixed. It is set by legislation and has been raised before, from 50 to 55 in 2010. The rise to 57 was legislated in the Finance Act 2022 and takes effect on 6 April 2028. You can read the government's explanation in its policy paper on increasing the normal minimum pension age.
When will it change to 57?
From 6 April 2028 the NMPA rises from 55 to 57. If you have not reached 55 by then, you will generally have to wait until 57 to access your pension savings, unless you have a protected pension age.
The change applies to personal pensions, self-invested personal pensions (SIPPs) and defined contribution workplace pensions. It also applies to defined benefit schemes where the scheme's earliest payment age is linked to the NMPA, although each scheme's own rules still set its normal retirement age.
How the change works by date of birth
| Date of birth | Earliest access before 6 April 2028 | Earliest access from 6 April 2028 | What it means |
|---|---|---|---|
| Before 6 April 1971 | 55 | Not affected | You will already be 57 or older by 6 April 2028. |
| 6 April 1971 to 5 April 1973 | 55 | 57, unless you have a protected pension age | You can access your pension from 55 up to 5 April 2028. If you have not reached 57 by 6 April 2028, access may pause until you do. |
| On or after 6 April 1973 | Not applicable | 57 | You reach 55 on or after 6 April 2028, so your earliest access age is 57. |
If you were born between 6 April 1971 and 5 April 1973, check carefully with your provider how the change affects you, particularly if you have not yet started taking benefits.
The government has also said in the past that it intends the minimum pension age to stay around ten years below State Pension age. No further change has been legislated, but it is worth bearing in mind if you are in your forties.
Who will be affected most?
- People aged 54 or younger today who planned to take pension money at 55 or 56. If you reach 55 on or after 6 April 2028, you will generally need to wait until 57.
- Anyone planning to stop work in their mid-50s, who may need other savings to bridge a gap of up to two years.
- Members of defined benefit schemes thinking about a transfer. Money transferred into a SIPP or personal pension is subject to the NMPA. A transfer could also mean losing a protected pension age, or an early retirement right, that your scheme gives you.
Protected pension age
Some people have a protected pension age that is lower than 57. This usually applies if, before 11 February 2021, you were a member of a scheme whose rules gave you an unqualified right to take benefits before 57. There are also older protections for some occupations that had a pension age as low as 50.
Protection is usually tied to the scheme it came from. Whether it survives a transfer to another pension depends on detailed rules and on how the transfer is made, so it can be lost. Always check your scheme rules and ask the scheme administrator in writing before you make any decision.
This matters most for people considering a defined benefit transfer. Losing a protected pension age could mean waiting several extra years to reach your money, which could upset your retirement plans and cash flow.
How the change affects different types of pension
Defined contribution pensions and SIPPs
For most defined contribution pensions and SIPPs, the rise means a straightforward two-year delay if you do not reach 55 before 6 April 2028. That can disrupt plans to retire early, especially if you do not have other money to bridge the gap.
Defined benefit (final salary) pensions
Defined benefit schemes have a normal retirement age set out in their rules, often 60 or 65. You can usually take your pension from that age, or earlier with an actuarial reduction, from the scheme's earliest permitted age. Each scheme's rules set the details, so ask your administrator what is possible and how big the reduction would be.
Transferring a DB pension and the NMPA. If you transfer a defined benefit pension to a SIPP or personal pension, the money becomes subject to the NMPA. A transfer does not automatically give earlier access, and it could delay it. It would also mean giving up a guaranteed income for life. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. If your safeguarded benefits are worth more than £30,000, you must take regulated advice from an FCA-authorised adviser with the pension transfer permission before the scheme will let you transfer.
You can read more in our defined benefit pension guide and our explainer on transfer values.
Can I take my pension earlier than 55?
You have to follow the minimum pension age, but there are some exceptions.
- Ill health. You may be able to take your pension early if you meet the ill-health condition, which broadly means you are no longer able to carry on your occupation because of ill health, supported by medical evidence. If you are expected to live less than a year, you may be able to take your whole pension as a lump sum. Ask your scheme what it offers.
- A protected pension age. As above, some people have a right to take benefits earlier because of their scheme's rules or their occupation.
Taking money out of a pension before you are allowed to is an unauthorised payment. HMRC charges 40% tax on it, and a further 15% surcharge can apply, so the total can reach 55%, and the scheme may face charges too. Offers to "unlock" your pension before 55 are a classic sign of a scam. Check the FCA's ScamSmart site before you deal with anyone.
Teachers and other public-sector schemes
Public-sector pensions are defined benefit schemes with their own retirement rules, so the answer to "can I retire at 55?" depends on your scheme. Most let you take your pension from 55, but it is usually reduced if you take it before the scheme's normal pension age.
- Teachers. In the Teachers' Pension Scheme, the earliest age benefits can usually be paid is 55, unless you retire because of ill health. If you take them before your normal pension age, your pension and lump sum are reduced for life. Normal pension age is 60 or 65 for final salary benefits, depending on when you joined, and your State Pension age, or 65 if later, for career average benefits. So you can usually retire from teaching at 55, but on a smaller pension than if you waited.
- Local Government Pension Scheme (LGPS). In England and Wales you can take your LGPS pension from 55, normally with a reduction before your normal pension age. Some longer-serving members are protected by the 85-year rule. The scheme says the earliest age will rise to 57 from 6 April 2028, except for ill-health retirement. Our LGPS pension guide explains the details.
- NHS, Civil Service and other schemes. Each scheme has its own normal pension age and early retirement terms. Ask your scheme for an estimate at the age you have in mind, and ask whether the rise in the minimum pension age to 57 affects you.
Transferring is not a way round these rules. Unfunded public-sector schemes, such as the NHS, Teachers', Civil Service, Police, Firefighters' and Armed Forces schemes, cannot be transferred to a personal pension at all. The LGPS can be, but money in a personal pension is subject to the minimum pension age, and you would give up guaranteed benefits. Our guide to public-sector pensions explains which schemes can and can't transfer.
Planning for retirement at 55 or 57
Retiring early is not just a case of deciding you have had enough of work. You need a plan for the next 30 years or more. Think about your savings, your spending, big events such as moving house or helping children with university, and the effect of inflation.
It is also important to look at your partner's pension and when each of you will get your State Pension, so that the move into retirement is as smooth as possible.
Review your timeline
If you are 54 or younger and planned to take pension money at 55 or 56, look again at your dates. You may need other income for those years, such as ISA withdrawals, cash savings or part-time work.
Build other savings
ISAs and other investments you can reach at any age can act as a bridge between the date you stop work and the date you can draw your pension.
Understand your DB scheme rules
If you have a defined benefit pension, find out its normal retirement age, its earliest retirement age and how early retirement reductions work. Do not assume that a transfer to a SIPP will give you earlier access.
How much income will I need?
To retire comfortably at 55 or 57 you need to work out your income needs carefully. A common rule of thumb is to aim for around two-thirds to 70% of your pre-retirement earnings, but your own spending is what really counts.
Things to consider:
- Your income needs. Rules of thumb are a starting point only. Build your own budget.
- Your savings. Decide how much of your savings you will use to top up your income, and whether you want them to keep growing.
- Your lifestyle. Be realistic about the lifestyle you want. Do you want to cover the essentials, or have two holidays a year and change your car every few years?
The Pensions UK Retirement Living Standards give a useful guide to what minimum, moderate and comfortable retirements cost.
What is the average pension pot at 55?
There is no official figure for exactly age 55, but the Office for National Statistics publishes figures for the age group. In its Saving for retirement in Great Britain bulletin, covering April 2018 to March 2020, people aged 55 to 64 who had pensions not yet in payment had a median value of £107,300. Counting everyone aged 55 to State Pension age who had not yet retired, including people with no pension at all, the median was £37,600.
Treat these as background only. They are several years old, they include the estimated value of defined benefit pensions as well as pension pots, and the median hides a very wide range. Your own savings and spending are what matter.
A helpful exercise is to write down everything you spend now, then what it might look like if you retired tomorrow. It shows how much your income needs to change. It can be humbling, but it helps to set realistic expectations.
Will inflation affect my income?
Yes. Inflation reduces what your money will buy, so your plan needs to allow for it. Rising living costs can eat into your savings faster than you expect.
To afford to retire at 55 or 57, you may need to adjust your expectations and savings goals. Review your plan regularly so that you stay ahead of rising prices.
Recent years have shown what happens when inflation is ignored. When prices rose by double digits, pension income that had looked comfortable did not go as far as people had planned.
What other sources of income or investments can I use?
Having more than one source of income can make an early retirement more secure and reduce how much you rely on your pension. Ways to broaden your finances include:
- Pensions and investments
- Keep paying into a pension while you are working, to benefit from tax relief.
- Investments such as shares, bonds or funds, usually held in an ISA, can provide growth or income.
- Your retirement investment approach
- Balance risk and return in a way that suits how long you have until, and through, retirement.
- Consider whether an annuity could provide part of a steady income.
- Other income
- Rental income from a property.
- Part-time work or consultancy to top up your pension.
Does my spouse or partner have a pension?
When you plan to stop work early, look at both your pensions together. Your combined income, from workplace pensions, personal pensions and State Pensions, can make a big difference to whether an early retirement is affordable.
Use the MoneyHelper pension calculator to estimate the income you could each expect. It helps to clarify your joint outlook and to line up your saving.
When will I get my State Pension?
Your State Pension age depends on your date of birth, and the amount depends on your National Insurance record. State Pension age is currently 66 and is rising to 67 between 2026 and 2028.
The easiest way to check is on the gov.uk State Pension forecast service. It tells you when you will get your State Pension, roughly how much, and whether there are gaps in your National Insurance record.
Cash flow planning
Understanding your expected income and spending, and the effect inflation and investment growth will have on your pensions and savings, is a key part of planning an early retirement.
Arthur Browns Wealth Management: What is cashflow planning? from CashCalc
You need to look at your total income, including pensions and investments, and check it lines up with what you expect to spend, year by year.
How can I use my investments to provide an income?
Using your investments to produce a steady income is a key part of cash flow planning for an early retirement. To keep your lifestyle, you need to know how much you need and where it will come from.
- Know where your pension is invested and whether you are likely to need more.
- Dividends: shares or funds that pay dividends can provide regular income.
- Interest: bonds and savings accounts can provide interest.
- Rental property: an investment property can provide ongoing income, with its own costs and risks.
Review your approach regularly to keep up with markets and your changing needs. A regulated financial adviser can help you plan how to draw income from your pensions and investments.
What are my retirement options at 55 or 57?
If you want to retire at 55 or 57 with a defined contribution pension, the main choices are an annuity, pension drawdown, taking lump sums, or a mix of these. You also need to understand the tax rules.
An annuity gives a guaranteed income, usually for life, which can give financial security, although you give up access to the capital.
Pension drawdown gives more flexibility and the potential for growth, but needs careful management so that you do not run out of money too soon.
Annuities
An annuity turns some or all of your pension pot into a regular income. If you are aiming to retire early, it helps to understand how annuities work and how they fit with your State Pension.
- Types of annuity
- Level: pays the same amount each year.
- Escalating or index-linked: rises each year by a set rate or with inflation, starting lower.
- Benefits
- Security: a guaranteed income, usually for life.
- Simplicity: easy to manage once it is set up.
- Things to consider
- Rates: these change over time and are generally lower at younger ages, because the income is expected to be paid for longer.
- Pot size: check whether your pot will buy enough income.
- Health and lifestyle: providers take your health and habits, such as smoking, into account, and some conditions can mean a higher income.
Think carefully about whether an annuity suits your situation and goals, and shop around rather than taking your provider's first offer.
If you have an older pension with a guaranteed annuity rate, it may be worth far more as an annuity than the market rate. See our guide to guaranteed annuity rates.
Pension drawdown
Drawdown is a flexible alternative. You can usually take up to 25% of your pot tax-free and keep the rest invested, drawing an income as you need it.
To avoid running out of money, work out how much you need in your pot to retire comfortably. Allow for your fixed costs and for unexpected expenses such as health care.
Remember that the minimum pension age rises to 57 in April 2028, so plan ahead. Your drawdown pot remains invested and its value can go down as well as up.
What else do I need to consider?
Inflation can erode your buying power over time, so plan for rising costs. You also need to understand how income tax applies to money you take from your pension. Finally, think realistically about how long you and your partner might live, so your savings do not fall short.
Inflation
Inflation can significantly reduce the buying power of your pension over the years. If you plan to retire at 55, think about:
- How inflation affects how much you need to retire.
- How your pension is growing in real terms, after inflation.
- Ways of saving and investing that allow for inflation over the long term.
Inflation can erode your savings, so it pays to be methodical about protecting your lifestyle. Regulated financial advice can help you build a plan that copes with rising prices.
Income tax
How income tax applies to your pension makes a big difference to the income you actually receive.
If you stop work at 55 and have no other taxable income, you can use your personal allowance, £12,570 for 2026/27, before you pay any income tax. Combined with tax-free cash, that can provide an income with little or no tax. Once you reach State Pension age, a full new State Pension uses almost all of the personal allowance, so plan for that. You can check current rates on gov.uk.
Your tax-free cash is generally 25% of your pension, up to the Lump Sum Allowance of £268,275 for most people. The Lifetime Allowance was abolished from 6 April 2024. Taking a taxable payment from a pension pot can also trigger the money purchase annual allowance, which limits future tax-relieved contributions to defined contribution pensions to £10,000 a year.
Unused pension funds and most death benefits are due to come into the scope of inheritance tax from 6 April 2027. This could affect how you plan to use your pension and other savings.
How long might I and my partner live?
How long your retirement lasts makes a big difference to how much you need. Living longer than expected could put real pressure on your money. Think about:
- Life expectancy factors
- Your health and lifestyle.
- Your family history.
- Average life expectancy figures from the ONS.
These help you judge how much you need. An average pension pot may not be enough if you retire at 55 and live longer than average.
Planning for a long life can involve:
- Adjusting your savings targets.
- Refining how you invest.
- Looking for other sources of income.
Can I rely on the state if I run out of money?
Relying on the State Pension as a safety net can leave you financially vulnerable. It is an important foundation for most people, but it is designed to provide a basic income and is unlikely to cover everything. If you want to retire at 55 without running into money problems later, plan for income well beyond the State Pension.
Can I release equity from my home?
You might look at equity release to give yourself more flexibility in retirement. It can top up your income, but it is a big decision with long-term costs. It is generally only available from age 55.
- Types of equity release
- Lifetime mortgage: you borrow against your home and keep ownership. Interest usually rolls up and is repaid when the home is sold.
- Home reversion plan: you sell part or all of your home in return for a lump sum or regular payments and keep living there.
How much you can release
- Your age and the value of your home largely decide how much you can release.
- Generally, the older you are and the more valuable your home, the more you can access.
Points to weigh up
- It can give you money without having to move.
- It may reduce what you leave in your estate and affect means-tested benefits.
Before you release equity, weigh up the long-term effect on your estate and whether it fits your goals. Equity release requires regulated advice from a specialist adviser.
How will I manage my pension investments?
If you plan to retire early, review your investments regularly and adjust your approach as your goals and markets change.
Start by estimating your income needs. Rules of thumb such as replacing around 70% of your earlier income are a starting point, but your own budget matters more.
While you are still working, make the most of your pension contributions. Tax relief and employer contributions can give your savings a real boost. Choose investments that balance growth potential with risk, and remember the long-term effect of compounding.
Be aware of how inflation, income tax and the State Pension affect your retirement income. Whether you choose an annuity, drawdown or both, understand how each affects how long your money lasts.
A regulated financial adviser can give personal advice on managing your pension investments, your contributions and how much you are likely to need.
How can I save more before I retire?
If you want to retire at 55, look at your savings now. A few changes can make a real difference to how your pension grows.
- Use tools and guidance
- Use a pension calculator to estimate how much you need.
- Use the free, impartial guidance from MoneyHelper and Pension Wise.
- Understand how income tax applies to your pension income.
- Budgeting and spending
- Separate essential from non-essential spending to see how much you really need.
- Work out your fixed costs and how your regular spending might change.
- This shows how much you need to save to keep the lifestyle you want.
- Review how you invest as your goals change
- Understand how markets and compound growth affect your pension.
- Review your fund choices and charges regularly.
- Start early. The longer you wait, the more you need to save each month.
Retire at 55: questions to ask yourself
Before you set a date, it helps to check your plans. These questions are about retirement planning in general. They are not a test of whether you should transfer a pension.
- Your savings
- Have you saved enough for the income you want?
- Have you allowed for income tax on what you take out?
- Is your saving on track for the lifestyle you want?
- Your pension options
- Have you allowed for inflation reducing what your pension will buy?
- Do you know when your State Pension starts and how much it will be?
- Do you understand the difference between an annuity and drawdown?
- If you have a defined benefit pension, do you know its normal and earliest retirement ages?
- Planning for the future
- Have you thought about how annuity rates and markets might change?
- Are you prepared for the unexpected, such as care costs or a fall in markets?
- Can you adjust your plans if your circumstances change?
Conclusion
Retiring at 55 can be achievable with careful planning and a clear idea of how much money you need. The rise in the minimum pension age to 57 in April 2028 is not just a technical change: it could directly affect your plans if you reach 55 after that date.
Look at your pension options, manage your investments carefully, build up other savings and check your plans regularly. If you have a defined benefit pension, find out what your scheme allows before you consider anything else, and remember that a transfer is unlikely to be in most people's best interests.
Talk it through
If you have a final salary pension and want to understand how transfers and the advice process work, you can book a free chat about how the process works. It is general information, not advice. For impartial guidance on your options, contact MoneyHelper.
Frequently asked questions
Can I access my pension at 55 in the UK?
At the moment the minimum pension age in the UK is 55, but it rises to 57 from 6 April 2028. If your scheme rules give you a protected pension age, you may keep the right to take your pension earlier. Check your scheme rules with your provider.
What is the normal minimum pension age (NMPA)?
The NMPA is the earliest age you can usually take money out of a private pension without paying a tax penalty. It applies to defined contribution pensions, including personal pensions and SIPPs, and to defined benefit schemes.
How much money do I need to retire at 55 in the UK?
It depends on the lifestyle you want and how long your money needs to last, which could be 30 years or more. The Retirement Living Standards give a useful guide to the cost of minimum, moderate and comfortable retirements. A regulated financial adviser can model your own circumstances.
When will the minimum pension age rise to 57?
The normal minimum pension age rises from 55 to 57 on 6 April 2028. Some members have a protected pension age that allows earlier access. This generally applies where scheme rules gave a right to take benefits before 57 before 11 February 2021.
How does the NMPA change affect defined benefit pensions?
Each DB scheme sets its own normal retirement age. If you transfer a DB pension to a SIPP, the money becomes subject to the NMPA, so it could not be accessed until 57 if you reach 55 on or after 6 April 2028, unless a protected pension age applies and is kept.
Can I take a tax-free lump sum when I retire at 55?
Usually yes. When you access your pension from 55 (rising to 57 in April 2028), you can generally take up to 25% tax-free, up to the Lump Sum Allowance of £268,275 for most people. The rest is taxed as income when you take it. A regulated financial adviser can help you plan withdrawals tax-efficiently.
Should I transfer my defined benefit pension to retire early at 55?
Transferring a defined benefit pension is a significant, irreversible decision. A DB pension pays a guaranteed income for life, which is valuable and hard to replace. Transferring means giving that up in exchange for a cash equivalent transfer value (CETV), and the money would then be subject to the NMPA. If your safeguarded benefits are worth more than £30,000, you must take regulated advice from an FCA-authorised adviser with the pension transfer permission. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people.
This article is general information, not financial advice. Pensions and tax rules can change. The value of investments can go down as well as up. Beware of pension scams: check the FCA ScamSmart site before dealing with any firm.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read