Guide
What affects defined benefit transfer values?

Defined benefit (DB) transfer values are mainly driven by long-term gilt yields and inflation expectations, together with your age, your scheme's benefits and the assumptions its trustees use. When gilt yields fall, transfer values usually rise, and when yields rise, as they did sharply in 2022, transfer values usually fall. Nobody can reliably predict where they will go next, so trying to time a transfer is rarely a sound basis for a decision.
Should I transfer now or wait for the value to go up?
People often ask whether they should wait for their transfer value to rise. The honest answer is that nobody knows which way transfer values will move. What we do know is that many factors affect a DB transfer value, and several of them are specific to each scheme.
For background on how values have moved in recent years, see our article on defined benefit transfer values since 2022, and our main guide to the transfer value of a pension.
Schemes don't usually publish exactly how they calculate their transfer values, because the method depends on the scheme's own assumptions. That means you can't work out a scheme's transfer value yourself.
We can, however, look at the factors many schemes use, which helps explain why values can change quickly from month to month and year to year. Transfer values don't simply rise over time, and they don't move in line with stock markets in the way a defined contribution (DC) pension does.
What a defined benefit scheme promises
A DB scheme is a promise to pay a set level of income in the future, usually with increases linked to inflation so that the pension keeps its spending power over time.
In simple terms, the scheme collects contributions from members and the employer, invests them and aims to have enough to pay every member's pension for the rest of their life, and their spouse's or partner's life where the rules provide for it.
The investment risk is therefore borne by the scheme and the employer, not by the member. In a DC scheme, the member bears that risk.
Since the 2015 pension freedoms, some members have looked for more flexibility and asked about swapping their guaranteed DB income for a lump sum, the Cash Equivalent Transfer Value (CETV). Requests and values both rose sharply in the years up to 2021, when gilt yields were very low. Since gilt yields rose in 2022, transfer values have generally been lower.
How is a DB transfer value calculated?
A DB transfer value, or cash equivalent transfer value (CETV), is the scheme's estimate of the amount it would need today to provide the pension you have built up. The rules are set out in the Occupational Pension Schemes (Transfer Values) Regulations 1996. The trustees decide the assumptions, having taken the advice of the scheme actuary, and taken together those assumptions should lead to a "best estimate" of the transfer value. That set of assumptions is often called the scheme's transfer value basis.
In broad terms, the calculation works through four steps.
- Start with the pension you have built up. This is the yearly pension shown on your benefit statement, based on your service and salary (or career average earnings) when you left. The scheme also allows for other benefits and options you have, such as a spouse's or partner's pension, tax-free cash and early retirement terms.
- Roll it forward to your normal pension age (revaluation). A deferred pension is increased each year between leaving and retirement. How it is increased depends on your scheme's rules and the minimum the law requires for each period of service, usually linked to inflation and often with a cap. The higher the expected revaluation, the bigger the pension at retirement and the higher the transfer value.
- Estimate the payments over your lifetime. The actuary projects the pension you would be paid each year from normal pension age, with the increases it would get once in payment, and for how long, using life expectancy assumptions for people like you. A spouse's or partner's pension after your death is included where the rules provide one.
- Discount those payments back to today. Money due in future is worth less than money today, because money held now can be invested and grow. The scheme uses a discount rate, which is an assumed rate of investment return, to work out how much it would need today to pay each future amount. Adding these together gives the transfer value.
The discount rate has the biggest effect. Many schemes base it on long-term gilt yields, sometimes with an addition for the expected return on the scheme's other investments, and the regulations say trustees must have regard to the scheme's investment strategy when setting it. A lower discount rate means the scheme assumes it will earn less, so it needs more money today, and the transfer value goes up. A higher discount rate does the opposite. That is why the link between gilt yields and transfer values is so strong. Our guide to how gilt yields affect defined benefit transfer values explains it in more detail.
Finally, if the scheme doesn't have enough money to cover all its members' benefits, the trustees may in some circumstances reduce transfer values, based on a report from the actuary (regulation 7D). Your CETV statement should say whether a reduction has been made.
Illustrative example: Imagine a deferred member aged 55 with a pension of £10,000 a year payable from age 65. Suppose the scheme's basis, using its discount rate, revaluation, increases and life expectancy assumptions, gives a transfer value of £200,000, which is 20 times the yearly pension. Now suppose gilt yields fall and the trustees lower their discount rate. Nothing about the member's pension has changed, but the scheme now assumes it will earn less on the money it holds, so the same £10,000 a year might be valued at, say, £230,000. If yields rose instead, the figure might fall to, say, £170,000. These figures are round, hypothetical numbers chosen to show the direction of the effect. They are not based on any real scheme, and they are not a guide to what any scheme would pay.
Only your scheme can give you a guaranteed figure
Every scheme sets its own basis and doesn't usually publish it in full, so you can't work out your own CETV accurately from the outside. There is no calculator on this site, and online estimates can be very different from what a scheme would actually pay. Only your scheme can give you a guaranteed CETV.
To get one, ask the scheme in writing for a statement of your cash equivalent transfer value. The figure on it is guaranteed for three months from its guarantee date, and you are usually entitled to one free statement every 12 months. Our guide to the transfer value of a pension (CETV) explains what the statement shows, and our guide to how long a DB pension transfer takes covers the deadlines that follow.
A higher CETV doesn't make a transfer more suitable. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people, and advice from an FCA-authorised adviser with the pension transfer permission is legally required if your safeguarded benefits are worth more than £30,000.
Gilt yields: one of the biggest factors
One of the main factors affecting most transfer values is long-term gilt yields. A gilt is a bond issued by the UK government. You lend the government money, and it promises to pay a fixed income (or one linked to inflation) for a set period and then repay the loan.
The "yield" is the return an investor gets from a gilt at its current price. Gilt yields move with interest rates, inflation expectations and demand for government debt. For several years after the 2008 financial crisis and during the pandemic, the Bank of England bought large amounts of gilts through quantitative easing, which helped push yields to very low levels. Since 2022, rising interest rates and the Bank of England reducing its gilt holdings have contributed to much higher yields.
What does this have to do with DB transfer values?
As a general rule, the lower the gilt yield, the higher the CETV.
When yields are low, a scheme assumes it will earn less on the money it sets aside, so it needs to hold more money today to pay the same future pension. A transfer value reflects that, so the scheme offers more to members who want to leave.
In simple terms: if it took £100 to produce £1 a year of income when yields were 1%, and yields fell to 0.5%, it would take £200 to produce the same £1 a year.
The opposite is also true. When yields rise, the scheme needs less money today to pay the same future pension, so transfer values tend to fall. This is why many people saw their CETVs fall noticeably after gilt yields rose in 2022.
Looking at long-term gilt yields over recent years shows how volatile they have been, and why transfer values rose quickly during the pandemic and fell back afterwards.
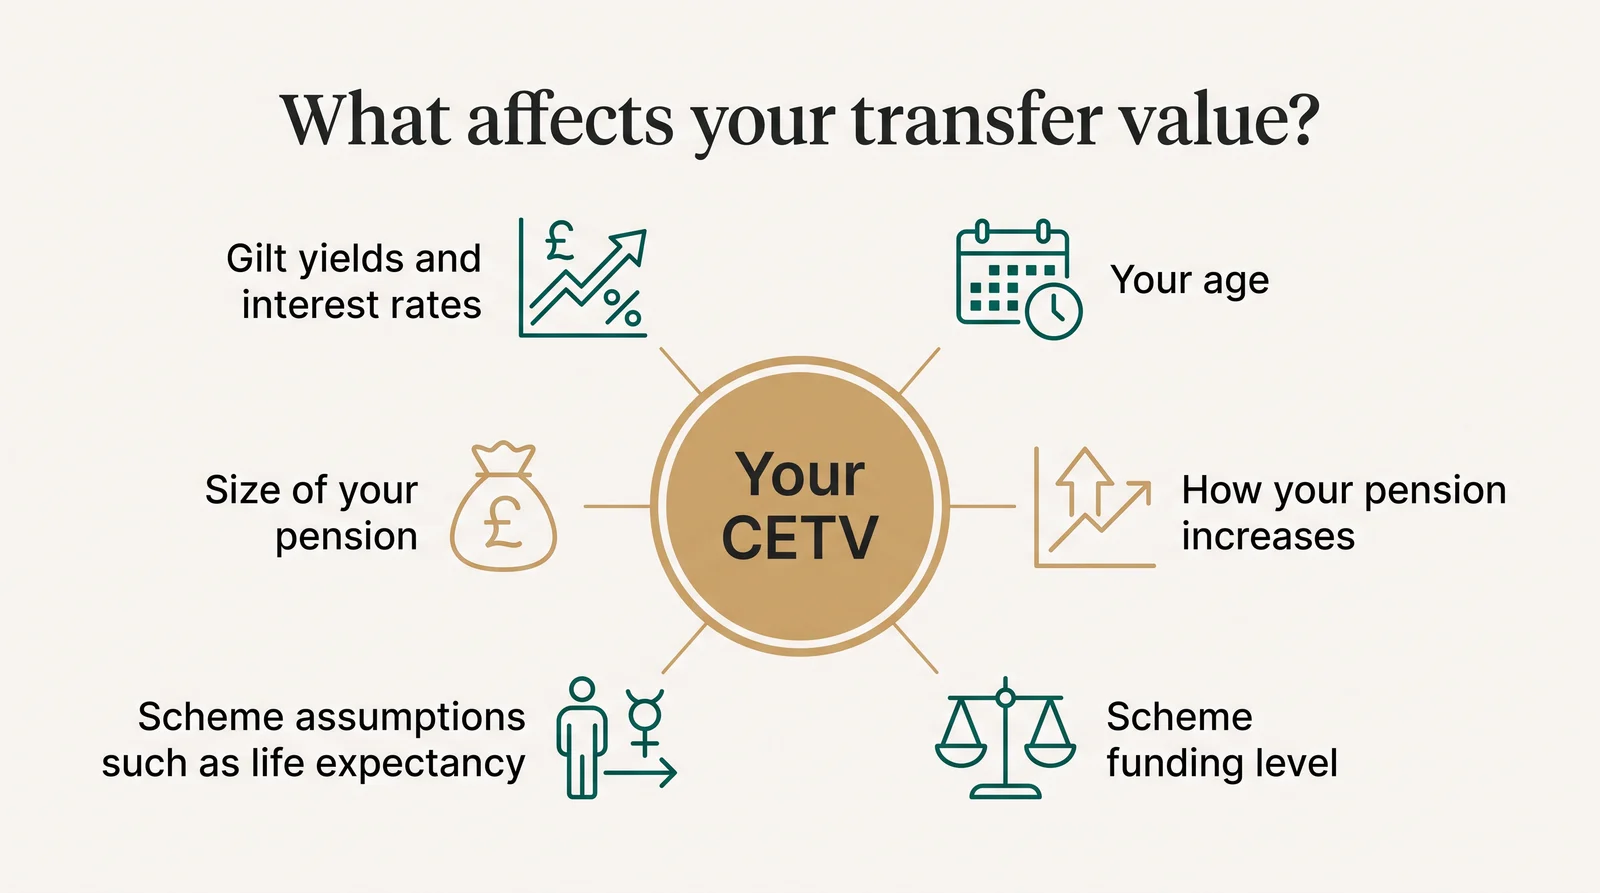
This is a simplified example. Gilt yields are only one of many factors used to calculate a CETV. You can read more in our guide: How do gilt yields affect defined benefit transfer values?
Other factors that affect transfer values
Other factors depend on the scheme and on you:
- Inflation expectations: if future inflation is expected to be higher, the cost of providing inflation-linked increases rises, which can increase transfer values.
- Your scheme's benefits: generous increases, spouse's pensions or early retirement terms can mean a higher transfer value.
- Your age: your age and how far you are from the scheme's normal pension age affect the calculation.
- Life expectancy assumptions: if people are expected to live longer, the cost of paying a pension for life rises.
- Scheme funding: trustees can, in some circumstances, reduce transfer values when a scheme is underfunded, following an actuarial report.
- The trustees' assumptions: each scheme sets its own basis, after taking actuarial advice, and may review it from time to time.
- How the scheme invests: some schemes base their assumptions partly on the expected returns of their own investments.
Should you wait for a higher transfer value?
Whether to wait comes down to your circumstances, not a guess about where gilt yields will go.
Do you need access to the money? Many people don't need a lump sum or income from their pension yet. A transfer is irreversible, and if someone transfers now to have flexibility in a few years' time, markets could fall in the meantime and reduce the value of what they have. For most people, the decision is about whether a transfer is in their best interests at all, rather than when to do it.
"I think I can invest better than my scheme." Some people feel they could do better by investing the money themselves. That may happen if markets perform well, but the risk would then be borne 100% by you. While your pension stays in the scheme, the scheme bears the investment risk. If markets do badly, you still get the promised income, and it is the scheme that has to make up the difference.
Reasons people raise for considering a transfer
People who explore a transfer often mention reasons such as:
- wanting to leave money to family on death, though from 6 April 2027 unused pension funds and most death benefits are due to come into the scope of inheritance tax
- wanting more income earlier in retirement than the DB scheme provides
- having other pensions or assets, so they feel the DB income is not needed
- poor health, which may mean the pension is paid for a shorter time
- being single with no dependants who would benefit from a spouse's pension
None of these on its own makes a transfer suitable. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people, and only a regulated adviser, looking at your whole situation, can say otherwise. If your DB benefits are worth more than £30,000, the law requires you to take regulated advice from an FCA-authorised adviser with the pension transfer permission before you can transfer.
You may also want to read about abridged advice, a shorter first stage of advice that can only conclude "don't transfer" or "full advice needed". We don't provide abridged advice.
Want to talk about how DB transfers work?
I don't give pension transfer advice. I offer a free, no-obligation chat that gives general information about how DB transfers and the advice process work. If you want regulated advice, I can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client. Introductions are for transfer values of £50,000 or more; below that, MoneyHelper is a good place to start. You can book a free chat about how the process works.
MoneyHelper and Pension Wise offer free, impartial guidance. Be wary of anyone who contacts you out of the blue about your pension; the FCA's ScamSmart site explains the warning signs.
Frequently asked questions
How is a defined benefit transfer value calculated?
The scheme's trustees, on the advice of the scheme actuary, estimate the pension you have built up, roll it forward to your normal pension age with revaluation, project the payments over your lifetime and discount them back to today using a discount rate, often based on gilt yields. Each scheme sets its own basis, so only your scheme can give you a guaranteed CETV.
What factors affect a defined benefit transfer value?
The main factors are long-term gilt yields (lower yields generally mean higher transfer values), inflation expectations, your age, the benefits your scheme provides, life expectancy assumptions, the scheme's funding level and the assumptions set by the trustees. Many of these are specific to each scheme.
How do gilt yields affect DB pension transfer values?
Gilt yields and DB transfer values usually move in opposite directions. When yields fall, transfer values tend to rise, because the scheme assumes it needs more money today to pay the same future income. When yields rise, as they did sharply from 2022, transfer values tend to fall.
Should I transfer my DB pension now or wait for the value to go up?
Nobody can reliably predict whether transfer values will rise or fall. The more important question is whether a transfer is in your best interests at all, and the FCA's starting assumption is that for most people it is not. If your DB benefits are worth more than £30,000, you must take regulated advice from an FCA-authorised adviser with the pension transfer permission before transferring.
What is a Cash Equivalent Transfer Value (CETV)?
A CETV is the lump sum your DB scheme will pay if you give up your promised benefits and transfer them to another pension. It is the scheme's estimate, using its own assumptions, of the value today of those benefits. A CETV is guaranteed for three months from the guarantee date, and you are usually entitled to one free statement every 12 months.
Do I need a specialist adviser to transfer a defined benefit pension?
Yes, if your safeguarded benefits are worth more than £30,000. The law requires advice from an FCA-authorised firm with the pension transfer permission, checked by a qualified pension transfer specialist. The adviser will carry out an Appropriate Pension Transfer Analysis (APTA) and show you a Transfer Value Comparator (TVC) before giving a recommendation.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read