Guide
What is Abridged Advice?

Abridged advice is a shorter, optional first stage of regulated advice on a defined benefit pension transfer. It can only conclude either that you should not transfer, or that it is unclear and full advice is needed. It can never recommend a transfer. Some FCA-authorised firms with the pension transfer permission offer it; this website does not provide it.
How abridged advice works
Abridged advice was introduced by the FCA to help screen out cases where a pension transfer is unlikely to be suitable, without the member having to commit to the full cost of advice.
It gives a regulated firm a way to engage with someone who wants to explore a possible defined benefit transfer, without going straight into full advice and its full costs.
The adviser asks for a set of basic information about the person's circumstances, so that they can decide which of the two outcomes applies. Abridged advice is regulated advice, and it must be given or checked by a qualified pension transfer specialist at a firm with the pension transfer permission.
The two possible outcomes
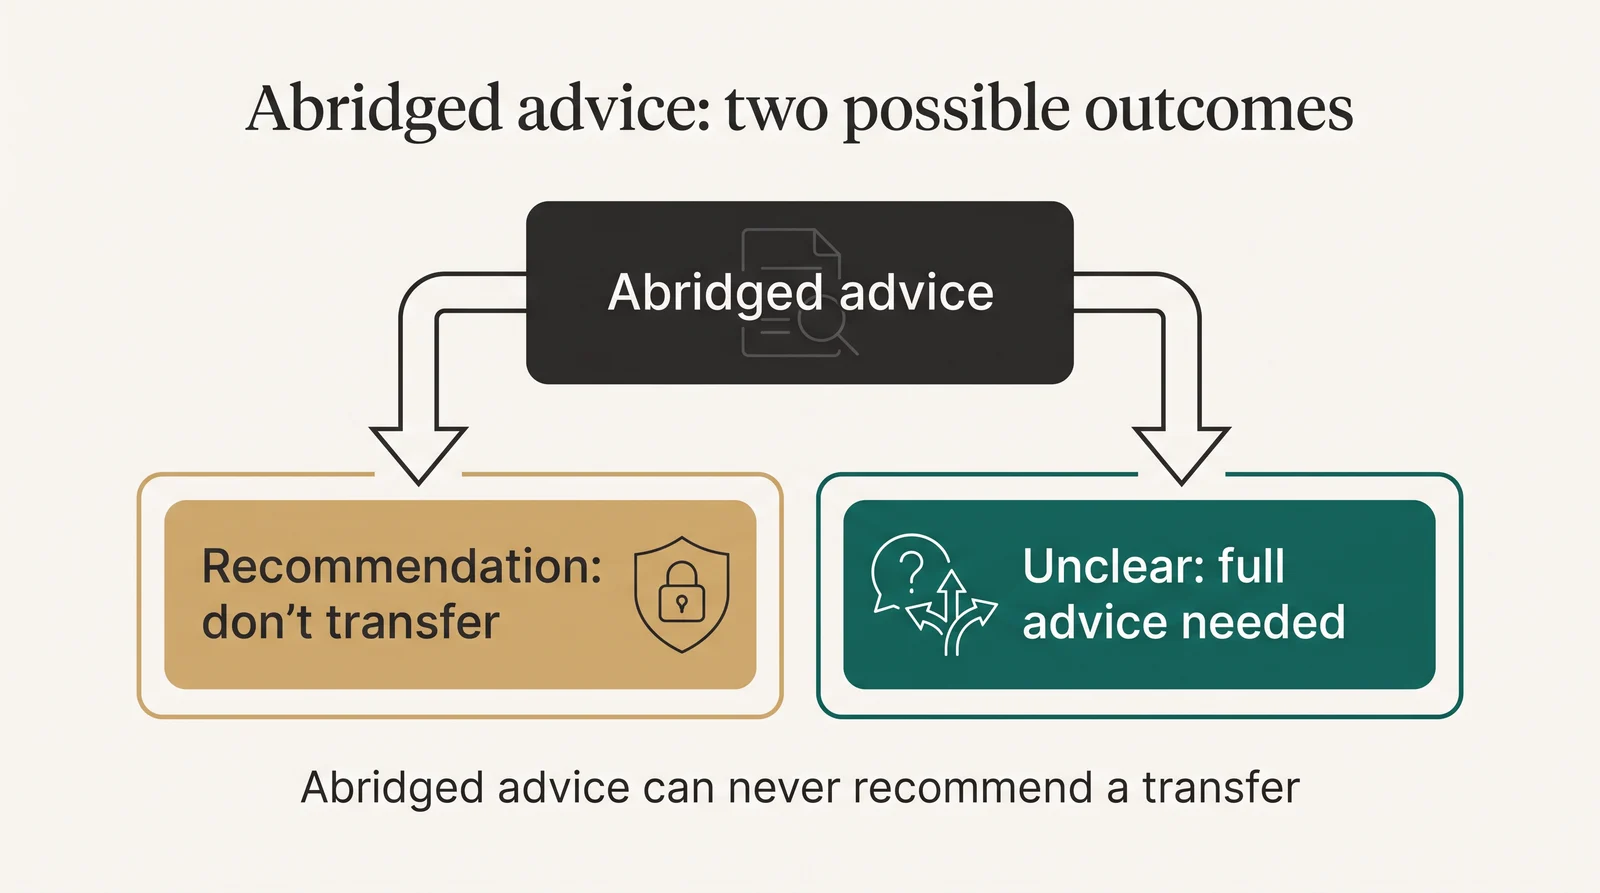
Abridged advice is an optional service that some firms offer as part of their process. It has two possible outcomes:
- A personal recommendation not to transfer or convert the pension. This is only possible if there is enough evidence from the limited information gathered to show that a transfer is not suitable.
- A conclusion that it is unclear whether a transfer would be in the person's interests, based on the limited information gathered. The firm can then offer full advice, where more information is collected to reach a firm recommendation either to transfer or to stay in the scheme.
The outcome of abridged advice can never be a recommendation to transfer. That is only possible after full advice.
The starting point
Advisers must start from the assumption that a pension transfer is unlikely to be suitable. This comes from the FCA's rules in the FCA Handbook (COBS 19.1). You can read the FCA's consumer guidance on its pension transfer page.
As part of the process, the adviser also looks at whether staying in the scheme carries its own risks, for example if the scheme is significantly underfunded. Even then, the Pension Protection Fund usually provides a safety net.
What does an adviser look at?
The areas an adviser typically considers in abridged advice include:
- When the person intends to start taking their pension.
- The risks of staying in the current scheme.
- The risks of moving from a guaranteed income to a flexible pension.
- How much the person needs a guaranteed income.
- Their experience, views and knowledge of investments, including whether they have managed their own investments before.
- Whether they have paid for financial advice before.
- How much income they need in retirement, how much of that comes from the pension being considered, and what the effect of losing that guaranteed income would be.
- Whether their objectives could be met in other ways, using other savings or income.
- Their attitude to investment risk.
How is abridged advice charged?
Firms can charge for abridged advice, and the cost must be made clear up front. If the outcome is unclear and the person goes on to full advice, firms should explain how the abridged advice fee relates to the cost of full advice. Some firms offset it, so that the person is not charged twice for the same work.
Abridged advice was introduced alongside the ban on contingent charging, which applies from 1 October 2020. Under the ban, firms generally cannot charge more for advice when a transfer goes ahead than when it does not, with limited exceptions for serious ill health and serious financial hardship. Abridged advice was designed to help more people get regulated advice in this area without necessarily paying the full advice fee.
How the industry has responded
Because it was a new form of advice, many advisers were cautious about offering it at first. Without experience of the pitfalls and possible risks to their business, some firms decided not to offer it at all, and not every firm offers it today.
In its first year, some advisers called for the format to be adjusted. Situations arose that may not have been foreseen when it was designed. For example, a pension tax issue such as the Annual Allowance might be relevant to the person but not to the transfer itself, and the scope of abridged advice limits what can be covered. FT Adviser reported on these calls in 2021: abridged advice needs to be tweaked, industry says.
As a concept, abridged advice can give people access to regulated advice at a lower cost than full advice, and a clear "don't transfer" answer where that is the right outcome. Like any process, it has its limits, and whether a firm offers it is up to that firm.
You may also want to read about what affects defined benefit transfer values and what a pension transfer specialist is.
Where to get help
This website does not provide abridged advice or full pension transfer advice. If your safeguarded benefits are worth more than £30,000, you must take regulated advice from an FCA-authorised adviser with the pension transfer permission before you can transfer. When you speak to a firm, it is reasonable to ask whether it offers abridged advice and how it charges.
For free, impartial guidance, contact MoneyHelper. Be wary of anyone who contacts you out of the blue about your pension, and check the FCA ScamSmart site before dealing with any firm.
If you would like to understand how DB transfers and the advice process work, you can book a free chat about how the process works. It is general information, not advice.
Frequently asked questions
What is abridged advice in pension transfers?
Abridged advice is an optional, shorter form of regulated advice that some firms offer on defined benefit pension transfers. It uses limited information to reach an early conclusion, without committing you to the full cost of advice. The outcome can only be a recommendation not to transfer, or a conclusion that it is unclear and full advice is needed. It can never result in a recommendation to transfer.
What are the possible outcomes of abridged advice?
There are two. The first is a personal recommendation not to transfer or convert your pension, which is only possible where there is enough evidence that a transfer is unsuitable. The second is a conclusion that it is unclear whether a transfer would be in your interests, in which case the firm may offer full advice to gather more information and make a firm recommendation.
What does an adviser assess during abridged advice?
They look at when you want to take your pension, the risks of staying in the scheme, the risks of moving from guaranteed to flexible benefits, how much you need a guaranteed income, your investment knowledge and experience, your attitude to risk, how much income you need in retirement, and whether your objectives could be met in other ways.
When did abridged advice come into effect?
Abridged advice came into effect on 1 October 2020, alongside the ban on contingent charging. The FCA introduced it as part of its rules on defined benefit pension transfers in COBS 19, to help more people get regulated advice without necessarily paying the full cost.
Can abridged advice result in a recommendation to transfer a pension?
No. Abridged advice can only recommend not transferring, or conclude that it is unclear and full advice is needed. A recommendation to transfer can only come from full advice, which involves a complete review of your circumstances. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people.
This article is general information, not financial advice.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read