Guide
7 Questions to Ask Before Transferring Your Pension Funds (2026 Guide)

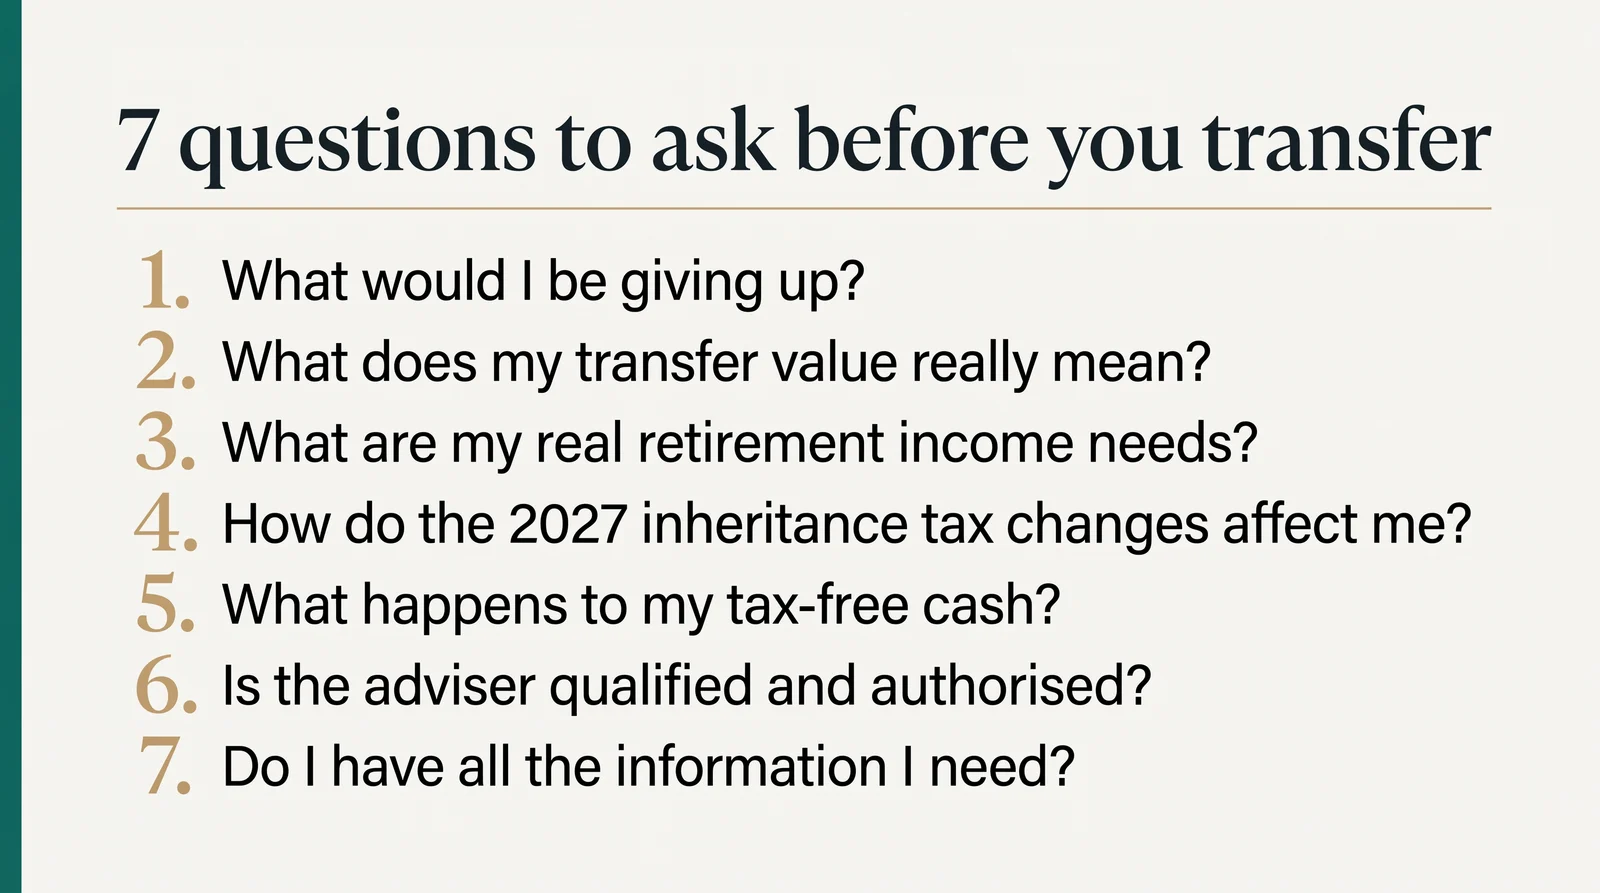
Before transferring a defined benefit (final salary) pension, ask what you would be giving up, what your transfer value really means, what income you need, how tax-free cash and the 2027 inheritance tax changes affect you, whether your adviser holds the pension transfer permission, and whether you have all the paperwork. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people, so these questions are about understanding the decision, not finding reasons to transfer.
Why these questions matter
If you are thinking about a defined benefit (DB) pension transfer, you are looking at one of the most important financial decisions of your life. Cash equivalent transfer values (CETVs) can run into hundreds of thousands of pounds, and a transfer cannot be undone.
The rules have changed a great deal in recent years. The Lifetime Allowance was abolished in April 2024, unused pension funds are due to come into the scope of inheritance tax from April 2027, and the FCA continues to scrutinise pension transfer advice closely. All of this makes the questions you ask, of yourself and of any adviser, more important than ever.
This guide sets out seven questions to work through before any decision about transferring your pension.
Question 1: What would I be giving up?
Before you think about what a transfer might offer, understand exactly what you would be giving up. A defined benefit pension, sometimes called a final salary or career average scheme, promises a guaranteed income in retirement, usually increasing each year, for the rest of your life.
The main benefits you lose if you transfer out usually include:
- A guaranteed income for life, however long you live and whatever happens to investment markets.
- Inflation protection. Many schemes increase payments each year in line with the Consumer Prices Index (CPI) or Retail Prices Index (RPI), often with a cap.
- A spouse's or dependant's pension. A proportion of your pension, often 50%, usually continues to your partner after your death.
- The Pension Protection Fund (PPF). If your employer becomes insolvent and the scheme cannot pay, the PPF usually pays compensation: generally 100% of your pension if you have reached the scheme's normal pension age, and 90% if you have not.
These are substantial, secure benefits. The question is whether the flexibility of a defined contribution pension really justifies giving them up in your circumstances. For most people, it does not.
Question 2: What does my cash equivalent transfer value really mean?
Your scheme will calculate a cash equivalent transfer value (CETV): the lump sum it would pay into a defined contribution pension if you left. CETVs can look impressive, sometimes 20 or 30 times your annual pension.
If you take advice, the adviser must give you a transfer value comparator (TVC). It shows roughly how much it would cost to buy the same guaranteed income on the open market. In many cases the cost of replacing your DB benefits is more than the CETV, sometimes by a wide margin. This is one reason the FCA's starting assumption is that a transfer is unlikely to be suitable for most people.
CETVs are affected by gilt yields and interest rates. When gilt yields rise, as they have in recent years, CETVs usually fall. When yields fall, CETVs usually rise. Timing can change the figure on offer, but it should never be the main reason for a transfer decision. A CETV is usually guaranteed for three months from its guarantee date, and you are normally entitled to one free statement every 12 months. Read more in our guide to transfer values.
Question 3: What are my real retirement income needs?
You need a clear picture of the income you will need in retirement. Think about:
- Your essential monthly spending in retirement: housing, food, utilities, insurance.
- The extra spending you want to keep: travel, hobbies, helping family.
- The State Pension you can expect. Check your forecast at gov.uk/check-state-pension.
- Any other pensions, savings or investment income you have.
- What your health and family history suggest about how long your income may need to last.
If your DB pension and State Pension together cover your essential spending, giving up the guaranteed part of that income adds risk where you can least afford it. A secure income for life is exactly what most people want in retirement.
Question 4: Have I considered the 2027 inheritance tax changes?
Unused pension funds and most death benefits are due to come into the scope of inheritance tax from 6 April 2027. Until then, pension funds can often be passed on outside your estate for inheritance tax.
This changes inheritance planning for many people and may affect how you think about drawing your pension compared with leaving it untouched.
The change is relevant to transfer decisions because:
- A DB pension mainly pays income to you and then any spouse or dependant. There is usually little left to inherit beyond a dependant's pension.
- A defined contribution fund can be left to adult children, but from April 2027 an unused balance is due to come into the scope of inheritance tax.
- Neither option escapes the new rules, and the planning available for each is different.
The final detail should be checked against the legislation and HMRC guidance. If inheritance is an important goal for you, ask a regulated adviser to model the effect on your estate before any decision.
Question 5: What happens to my tax-free cash?
Tax-free cash is one of the most misunderstood parts of a pension transfer, and the rules changed when the Lifetime Allowance was abolished from 6 April 2024.
The main allowances now are:
- Lump Sum Allowance (LSA): £268,275. The maximum most people can take as tax-free lump sums across all their pensions in their lifetime.
- Lump Sum and Death Benefit Allowance (LSDBA): £1,073,100. The overall limit on tax-free lump sums, including certain lump sums paid on death.
For most people, this means you can still take up to 25% of your pension tax-free, up to £268,275. If you hold one of the old Lifetime Allowance protections, such as enhanced or fixed protection, your allowance may be higher. Check this before any transfer.
DB schemes work out tax-free cash differently from defined contribution pensions, and the amount available can change on a transfer. Some older schemes also have protected tax-free cash above 25%, which could be lost. For some people the difference is tens of thousands of pounds, so it is worth getting the figures in writing.
Question 6: Is the adviser properly qualified and authorised?
An adviser who gives DB transfer advice must work for a firm that holds the FCA's pension transfer permission, and the advice must be given or checked by a qualified pension transfer specialist. Not every financial adviser can advise on DB transfers.
Questions to ask any adviser:
- Are you on the FCA Register? Check the adviser and the firm at register.fca.org.uk, and that the firm has permission to advise on pension transfers.
- Do you hold the pension transfer qualification? Confirm this is a recognised pension transfer specialist qualification, not just a general pensions qualification.
- Are you independent or restricted? Do you have links with particular product providers?
- What experience do you have? How many DB transfer cases have you handled?
- How do you charge? Ask for the full cost of the advice, and any ongoing charges for managing the money if you did transfer. Contingent charging (fees only payable if you transfer) has been banned for DB transfer advice since 1 October 2020, with limited exceptions for serious ill health and serious financial hardship.
- Do you offer abridged advice? Some firms offer a shorter first stage of advice that can only conclude "don't transfer" or "full advice needed".
The FCA has taken action against many advisers and firms over unsuitable pension transfer advice. Checking the Register takes minutes and could save you from a costly mistake.
Did you know?
Some pension scams pose as legitimate advisers and persuade people to transfer into high-risk or fraudulent investments. Always check credentials on the FCA Register, be wary of anyone who contacts you out of the blue about your pension, and visit the FCA ScamSmart site before you deal with anyone.
Question 7: Have I gathered all the information I need?
A well-informed decision needs proper groundwork. Before speaking to any adviser, gather:
- Your latest benefit statement, showing your expected pension at retirement.
- A CETV quotation from your scheme administrator. CETVs are usually guaranteed for three months.
- The scheme booklet, setting out how increases, death benefits and early retirement work.
- Your State Pension forecast from gov.uk/check-state-pension.
- Details of all your other pensions: defined contribution pots, other DB schemes and personal pensions.
- Your expression of wishes form for the current scheme, confirming who you would like benefits paid to.
If you have pensions from several employers, the government's free Pension Tracing Service can help you find them.
The FCA's position on DB pension transfers
The Financial Conduct Authority's starting assumption is that a transfer from a defined benefit pension is unlikely to be suitable for most people. The guarantees of a DB pension, including income for life, inflation protection and a spouse's pension, make it very valuable, especially when investment markets are uncertain. You can read the FCA's consumer guidance on its pension transfer page.
The FCA strengthened its rules after finding widespread poor practice, including conflicts of interest where advisers were only paid if a transfer went ahead. Advisers must now show that a transfer is in the individual's best interests, supported by a detailed analysis that includes the transfer value comparator.
The FCA does not ban transfers, and each person's situation is different, but for most people the guaranteed income is worth keeping. Only a full, regulated assessment of your circumstances can say otherwise.
If your safeguarded benefits are worth more than £30,000, the law requires you to take regulated advice from an FCA-authorised adviser with the pension transfer permission before you can transfer.
Getting help
The questions in this guide are a starting point. They cannot replace personal, regulated advice, because your health, income needs, family, other assets and goals all affect what is right for you.
If you are considering a defined benefit transfer, the most important step is to speak to an FCA-authorised adviser whose firm holds the pension transfer permission. They can assess your circumstances, explain your options and, if you go ahead with full advice, give you a written recommendation.
For free, impartial guidance, contact MoneyHelper. If you have defined contribution pensions and are 50 or over, you can also book a free Pension Wise appointment.
If you would like to understand how DB transfers and the advice process work before speaking to an adviser, you can book a free chat about how the process works. It is general information, not advice. Our defined benefit pension guide is a good place to start reading.
Frequently asked questions
What is a cash equivalent transfer value (CETV)?
A CETV is the lump sum your defined benefit scheme would pay into a defined contribution pension if you chose to leave. If you take advice, the adviser must give you a transfer value comparator (TVC) showing what it would cost to buy the same benefits on the open market. Often the cost of replacing DB benefits is more than the CETV, which is one reason the FCA's starting assumption is that a transfer is unlikely to be suitable for most people.
What happens to pensions and inheritance tax from 2027?
Unused pension funds and most death benefits are due to come into the scope of inheritance tax from 6 April 2027. Until then, pension pots can often be passed on outside your estate. The change affects DB and DC pensions differently, and the detail should be checked against the final rules. Take regulated advice before making decisions based on inheritance planning.
What is the Lump Sum Allowance (LSA)?
The Lifetime Allowance was abolished from 6 April 2024. The Lump Sum Allowance of £268,275 now sets the most tax-free cash most people can take across all their pensions. A separate Lump Sum and Death Benefit Allowance of £1,073,100 is the overall limit on tax-free lump sums, including certain death benefits. People with older Lifetime Allowance protections may have higher allowances.
Do I need a specialist adviser for a DB pension transfer?
Yes, if your safeguarded benefits are worth more than £30,000. The advice must come from a firm with the FCA's pension transfer permission and be given or checked by a qualified pension transfer specialist. Check any adviser and firm on the FCA Register at register.fca.org.uk before going ahead.
Is transferring out of a defined benefit pension usually suitable?
No. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. DB pensions provide a guaranteed income for life, inflation protection and a spouse's pension, which are hard to replace through investment. Any transfer must be assessed individually by an FCA-authorised adviser with the pension transfer permission.
How do I check if a pension adviser is authorised?
Search the FCA's Financial Services Register at register.fca.org.uk for the adviser and their firm. For DB transfer advice, check the firm has the pension transfer permission and that the adviser holds a pension transfer qualification. The FCA has taken action against many advisers over unsuitable transfer advice, so it is worth checking before you go ahead.
This article is general information, not financial advice. Pension and tax rules can change.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read