Guide
Beware of Pension Scams: Protecting Your Retirement Savings in the UK

The best protection against a pension scam is to ignore anyone who contacts you out of the blue about your pension, check every firm on the FCA Register, and never be rushed. Scammers typically promise high or guaranteed returns, early access before the minimum pension age or tax tricks, and they often target people with large defined benefit transfer values. If something feels wrong, stop and check the FCA's ScamSmart pages before doing anything.
A secure retirement usually represents a lifetime of hard work and careful planning. Sadly, that makes pension savings a prime target for organised and convincing fraudsters. In the UK, people lose life-changing sums each year to schemes that promise unrealistic returns, early access or tax advantages that don't exist. Knowing the warning signs, and how to protect yourself, is one of the most valuable things you can do for your financial future.
This guide explains the common tactics pension scammers use, the key warning signs, and practical steps to keep your savings safe. It also covers the protections in the UK, including the roles of the Financial Conduct Authority (FCA) and The Pensions Regulator (TPR).
How pension scammers operate: common tactics
Pension scams are often sophisticated and can be very convincing. Scammers usually aim to persuade you to move your pension into a high-risk, unregulated or non-existent investment. These are some of their most common approaches.
1. Unexpected contact: the cold call, text or email
One of the most persistent tactics is unsolicited contact: a cold call, text message, email, social media message or even a knock on the door. Since January 2019 it has been illegal for firms to cold call you about your pension unless you already have a relationship with them or have asked them to contact you. Treat unexpected texts and emails about your pension with the same suspicion. Any contact you didn't ask for should be an immediate red flag.
2. Pressure to act quickly
Scammers often use high-pressure tactics to rush you into a decision. They may say a "limited-time offer" or "once-in-a-lifetime opportunity" will disappear unless you decide straight away. The aim is to stop you taking guidance, getting advice or researching the investment, which is exactly what you should do.
3. Promises of high returns or early access
Be extremely wary of any investment promising guaranteed returns well above what mainstream investments offer, or any offer to unlock your pension early. You can normally only take money from a pension from the normal minimum pension age, which is 55 now and rises to 57 on 6 April 2028, unless you have a protected pension age or meet strict ill-health conditions. Offers of early access are a classic sign of a scam, and taking money out early can lead to tax charges of more than half of what is released, on top of the fees scammers take.
4. Complex, unregulated or overseas investments
Scammers often promote investments in unusual assets such as overseas property, hotels, forestry, storage units, green energy schemes or cryptocurrency. These are typically unregulated, which makes them much riskier and hard to check. Once money has been moved into such schemes, or sent abroad, it can be extremely difficult or impossible to get back.
5. Professional-looking websites and clone firms
Many scam operations create very professional websites and brochures, and use official-sounding names or logos. Some pretend to be real, authorised firms, which is known as clone firm fraud. They may use fake reviews or testimonials to build trust. Always check a firm's identity on the FCA Register, and contact it using the details shown there, not the ones you have been given.
Key point: people who fall victim to pension scams can lose large sums, and for some it is their entire retirement savings. Money taken in a scam is rarely recovered in full, so prevention matters far more than cure.
Why defined benefit members are targeted
People with defined benefit (final salary) pensions can have large transfer values, sometimes several hundred thousand pounds. That makes them an attractive target. Scammers may play down the value of a guaranteed income, or claim that a transfer will give you more control, higher returns or a bigger lump sum. Remember that a DB pension pays a guaranteed income for life, and the FCA's starting assumption is that a transfer is unlikely to be suitable for most people. Our guide to defined benefit pensions explains what you would be giving up.
Spotting the red flags
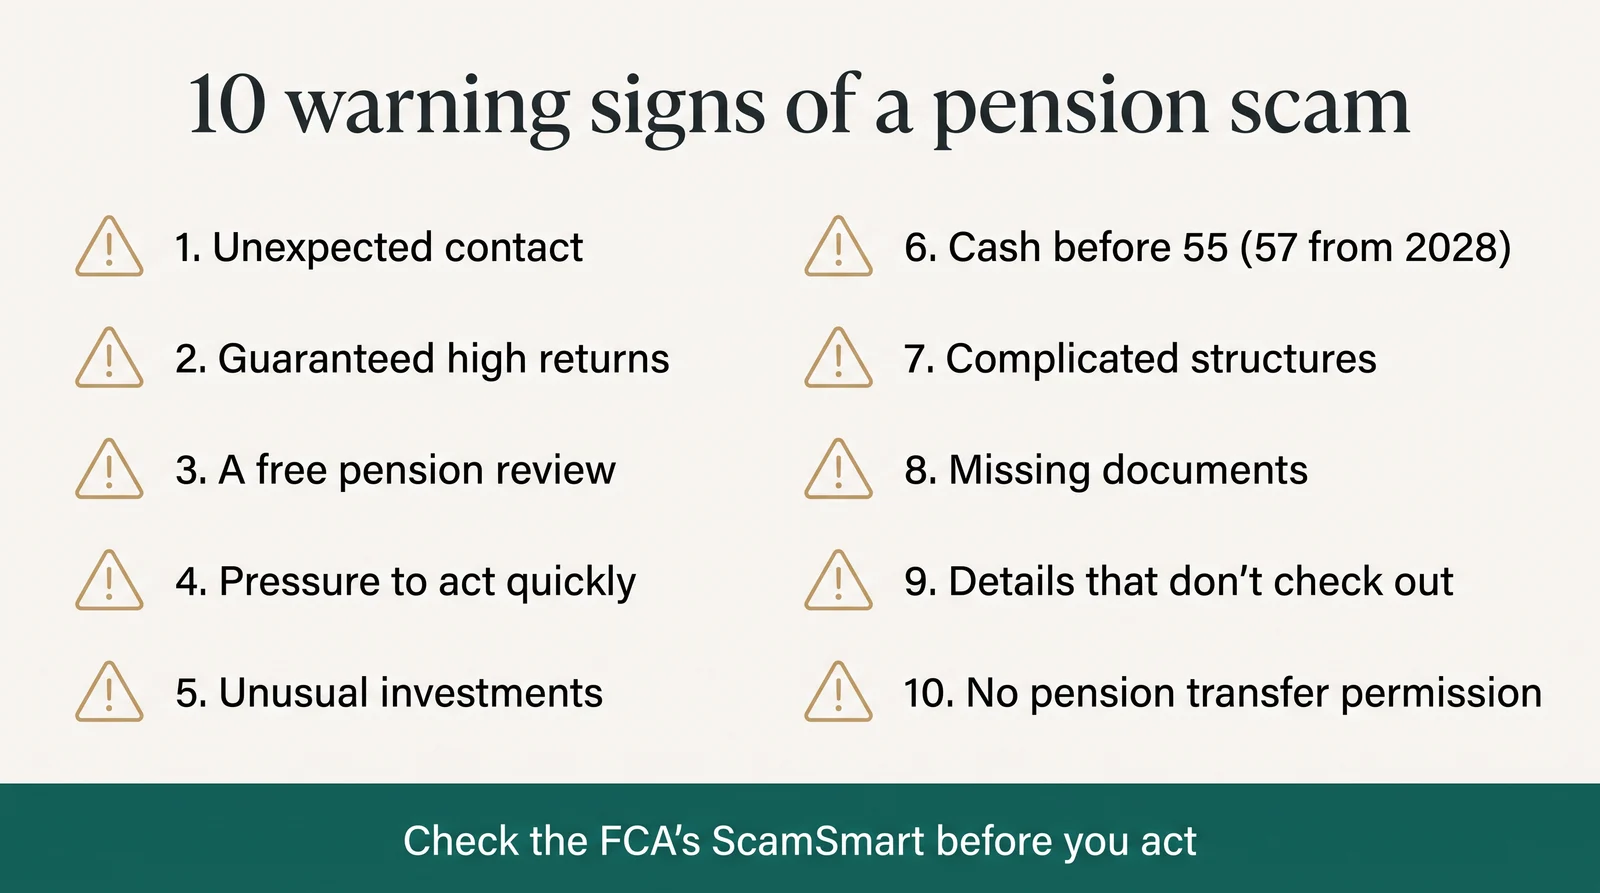
Recognising the danger signs early is your best protection. These are the main warning signs, many of which the FCA highlights through its ScamSmart campaign:
- Unexpected contact. A cold call, text, email or visit about your pension that you didn't ask for. Cold calling about pensions is illegal.
- Guaranteed high returns. Promises of returns of 8% a year or more, often described as "low risk" or "secure". If it sounds too good to be true, it almost certainly is.
- A free review of your pension from someone who contacted you. Offers of a free check or review from a firm that approached you are a common way for scammers to get your details. Genuine firms don't cold call, and they will be on the FCA Register.
- Pressure to act quickly. Deadlines, "limited-time" deals or demands for a quick decision. Scammers don't want you to stop and think.
- Unusual investments. Unconventional, unregulated assets such as overseas property, hotels, forestry, crypto or other alternative schemes.
- Access to your pension before the minimum age. Promises that you can get money out before 55 (57 from 6 April 2028). This is almost always a scam, or an unauthorised payment with heavy tax charges.
- Complicated structures. Moving money overseas or into several complex arrangements without a clear explanation.
- Missing information or documents. Incomplete paperwork, refusal to put things in writing, or documents with obvious errors.
- Company details that don't check out. The firm isn't on the FCA Register, or it claims to be authorised but uses different contact details from those on the Register.
- Advisers without the right permission. The person advising you on a DB transfer doesn't work for a firm with the FCA's pension transfer permission.
Important: pensions are complex. If someone approaches you about your pension out of the blue, especially about a transfer or early release, the safest thing to do is say no, end the conversation and report it.
Protecting yourself: practical steps
Being ScamSmart is about protecting yourself before anything goes wrong. These steps always make sense:
- Reject unexpected contact. Hang up on cold calls and don't reply to unexpected texts or emails about your pension. Don't click links in them.
- Check the FCA Register. Before dealing with any financial firm or adviser, check the FCA Register to make sure they are authorised and have the right permissions. If someone says they are from an authorised firm, contact the firm using the details on the Register.
- Get guidance and the right advice. MoneyHelper offers free, impartial guidance, and Pension Wise offers free appointments about DC pension options if you're 50 or over. If you're considering transferring a defined benefit pension, or any pension with safeguarded benefits, worth more than £30,000, the law requires you to take advice from an FCA-authorised firm with the pension transfer permission first.
- Read the Pensions Regulator's guidance. The Pensions Regulator has clear information on avoiding pension scams.
- Take your time. Never be rushed. A legitimate firm will give you time to think and to talk to family or other professionals.
- Report suspected scams. If you suspect a scam, report it to the FCA through its ScamSmart website and to Report Fraud (formerly Action Fraud), the national centre for reporting fraud and cyber crime.
- Talk to your scheme administrator. If you are thinking about a transfer, speak to your current scheme. Trustees and providers must carry out checks on transfers and may raise concerns.
Checks your pension scheme must make
Since November 2021, trustees and scheme managers have had stronger powers to stop suspicious transfers. Before a transfer goes ahead, they must check for warning signs:
- Red flags, such as evidence of an unsolicited approach, pressure to transfer quickly or incentives to transfer, allow the scheme to refuse the transfer.
- Amber flags, such as unusual or high-risk investments, high or unclear fees, or overseas investments, mean you must take specialist scam guidance from MoneyHelper before the transfer can go ahead.
These checks are there to protect you. If your scheme raises a concern, take it seriously. The Pensions Regulator has more detail on how the rules work.
Quick summary: key anti-scam steps
- Turn down all unsolicited pension approaches, including cold calls, texts and emails.
- Always check the FCA Register for firms and advisers.
- Get free guidance from MoneyHelper, and regulated advice where the law requires it.
- Never be pressured into a quick decision.
- Report suspected scams to the FCA and Report Fraud (formerly Action Fraud).
Getting help and advice
Protecting your retirement savings from scams takes vigilance. This article explains the warning signs, but for decisions about your own pensions, guidance from MoneyHelper and advice from a regulated financial adviser are the right places to turn.
If you have a defined benefit pension and want to understand how transfers and the advice process work, without any pressure, you can book a free, no-obligation chat with me. It's general information, not advice, and I'll never cold call you. I don't give pension transfer advice. If you then want regulated advice, I can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client. Introductions are for UK residents with a transfer value of £50,000 or more.
This article is for information only and is not financial advice. Pensions are complex. The value of investments can go down as well as up, and you may get back less than you invested. Tax rules can change. Please read our important information.
Frequently asked questions
Can I get early access to my pension in the UK?
Generally, no. You can usually only take money from a pension from age 55, rising to 57 on 6 April 2028, unless you have a protected pension age or meet strict ill-health conditions. Any offer to unlock your pension before then is very likely to be a scam, or an unauthorised payment that will lead to heavy tax charges.
What is a clone firm scam?
A clone firm scam is where fraudsters pretend to be a real, authorised financial firm. They use the firm's name, its firm reference number (FRN) and sometimes its logo, but give their own contact details. Always check contact details against the official FCA Register and use those to get in touch.
Who regulates pension transfers in the UK?
Financial advice, including advice on pension transfers, is regulated by the Financial Conduct Authority (FCA). Firms advising on transfers from defined benefit pensions must be authorised by the FCA and hold the specific pension transfer permission. Workplace pension schemes are regulated by The Pensions Regulator (TPR).
Should I accept a free review of my pension?
Be very wary of offers of a free review or check of your pension, especially from someone who contacted you first. It is a common way for scammers to get your details. If you want free, impartial help, go to MoneyHelper or Pension Wise, or contact a firm yourself after checking it on the FCA Register.
What should I do if I think I've been scammed?
Contact your pension provider straight away, then report the scam to the FCA through ScamSmart and to Report Fraud (formerly Action Fraud). The sooner you act, the better the chance of stopping a transfer or recovering some of your money.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read