Public-sector pensions: who can and can't transfer
If you work, or used to work, in the public sector, whether you can transfer depends on how your scheme is funded.
Unfunded schemes can't transfer to a personal pension
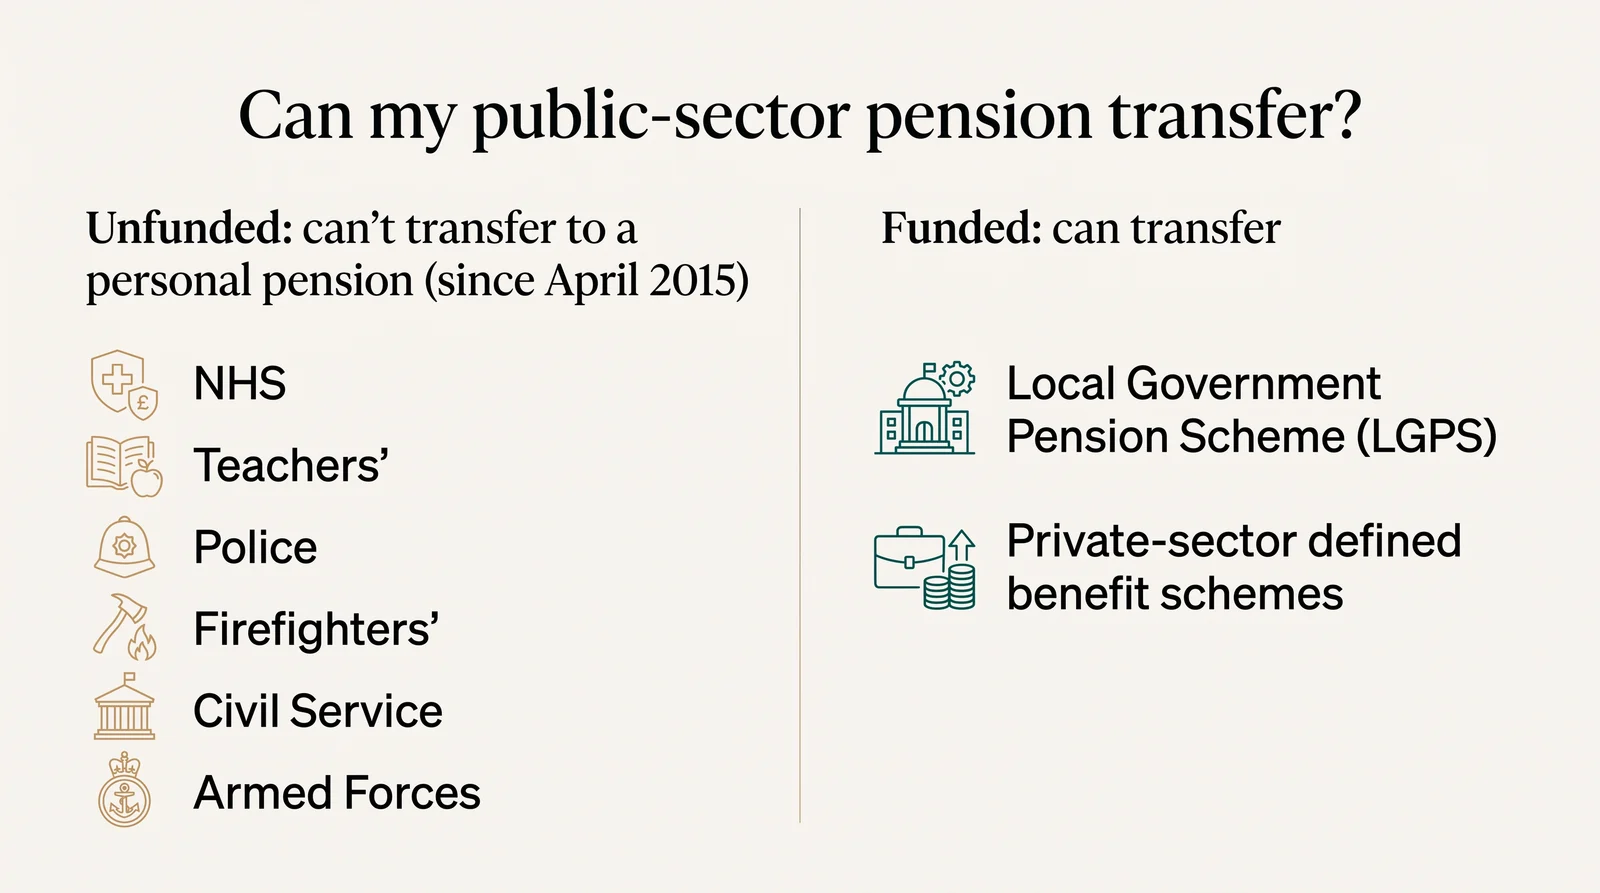
Most public-sector pension schemes are "unfunded". There is no pot of invested money behind them. Pensions are paid from current contributions and from general taxation.
Since 6 April 2015, the law has not allowed members of unfunded public-sector schemes to transfer to a defined contribution pension, such as a personal pension, SIPP or drawdown plan. This applies to the main schemes, including:
- the NHS Pension Scheme
- the Teachers' Pension Scheme
- the Police Pension Schemes
- the Firefighters' Pension Schemes
- the Civil Service Pension Scheme (including alpha and classic)
- the Armed Forces Pension Scheme
The same rules apply to the equivalent schemes in Scotland, Wales and Northern Ireland.
In some cases you may be able to move your benefits to another defined benefit scheme, for example under the Public Sector Transfer Club when you change public-sector jobs. Your scheme administrator can explain what's possible.
Because a transfer to a personal pension isn't possible, we're not able to help with a transfer from these schemes. If you would like to understand your options, MoneyHelper offers free, impartial guidance, and your scheme's own website will have information about your benefits.
The Local Government Pension Scheme is different
The Local Government Pension Scheme (LGPS) is a funded scheme. Contributions are invested in a fund managed by your local LGPS administering authority. This means LGPS members can usually ask for a transfer value and transfer to a defined contribution pension, as long as they haven't started taking the pension.
The same protections apply as for any other defined benefit pension:
- The FCA requires advisers to start by assuming that a transfer will not be suitable for you. For most people, keeping a defined benefit pension is the better option.
- If your safeguarded benefits are worth more than £30,000, the law requires you to take advice from an FCA-authorised firm with the pension transfer permission before you can transfer.
- The LGPS gives valuable guaranteed benefits, including inflation-linked increases and pensions for survivors, which you would give up.
If you're an LGPS member living in the UK with a transfer value of £50,000 or more, you're welcome to book a free chat about how transfers and the advice process work. We do not give defined benefit pension transfer advice, and we won't tell you whether a transfer is right for you.
Not sure what type of scheme you have?
Check your latest pension statement or your scheme's website, or ask your scheme administrator whether your scheme is funded or unfunded. You're welcome to get in touch and we'll explain the general rules.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Last reviewed 22 October 2026