Public-sector pensions: who can and can't transfer
If you work, or used to work, in the public sector, whether you can transfer depends on how your scheme is funded.
By Phillip Handley, Chartered Financial Adviser (LIBF), Adv DipFA
Most public-sector pensions, including the NHS, Teachers', Civil Service, Police, Firefighters' and Armed Forces schemes, are unfunded and cannot be transferred to a personal pension or other defined contribution pension. The Local Government Pension Scheme (LGPS) is the main exception: it is funded, so deferred members can usually transfer out, with regulated advice.
Unfunded schemes can't transfer to a personal pension
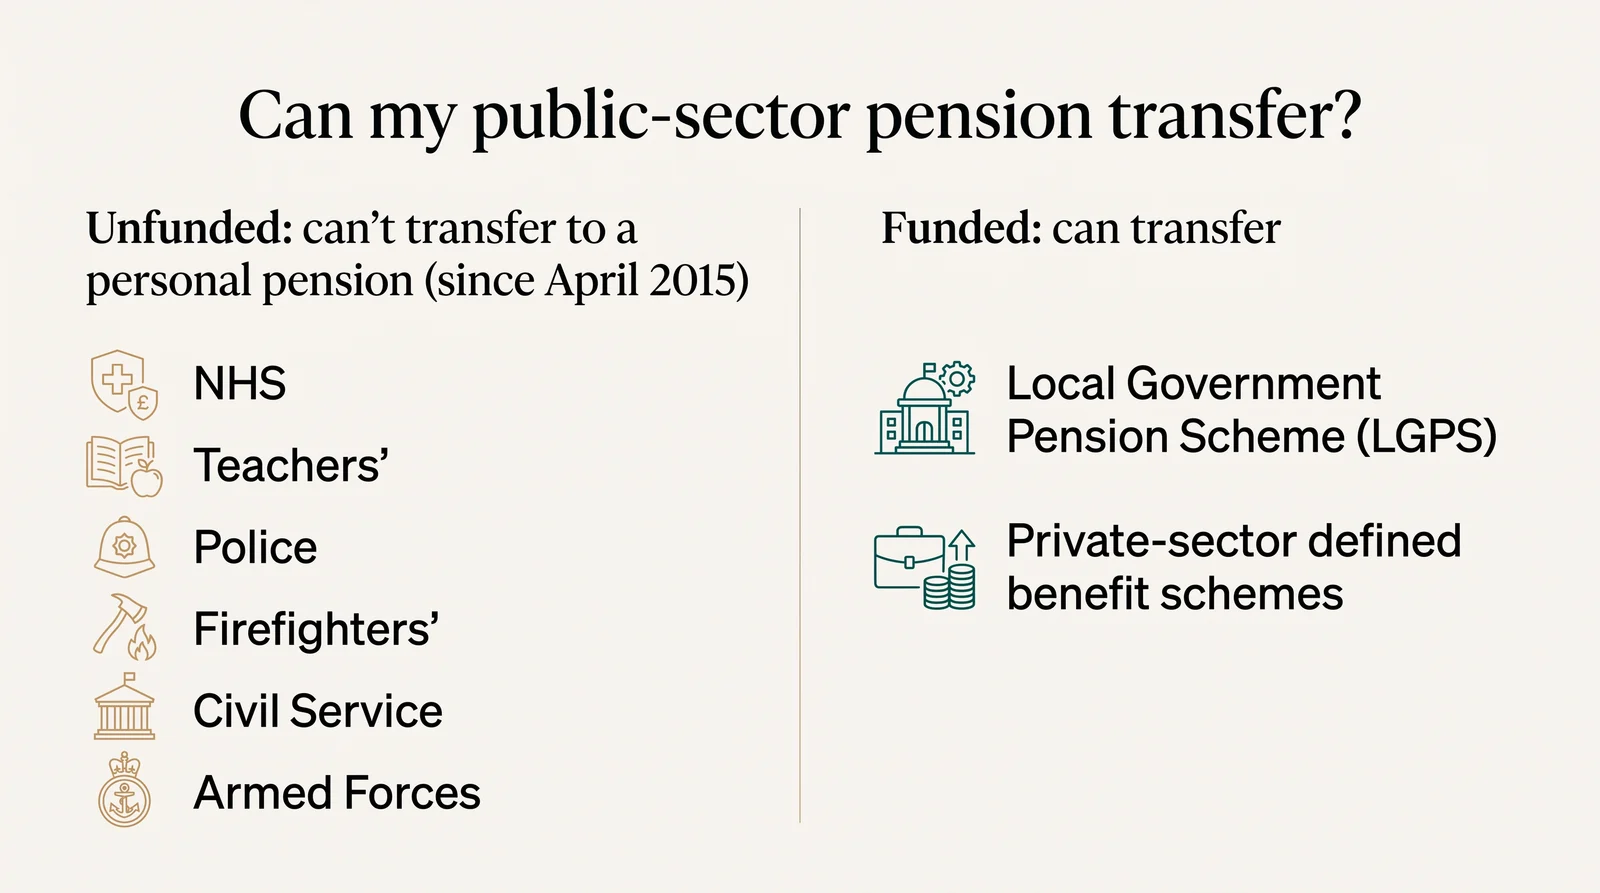
Most public-sector pension schemes are "unfunded". There is no pot of invested money behind them. Pensions are paid from current contributions and from general taxation.
Since 6 April 2015, the law has not allowed members of unfunded public-sector schemes to transfer to a defined contribution pension, such as a personal pension, SIPP or drawdown plan. The rule is in section 95 of the Pension Schemes Act 1993, as amended by section 68 of the Pension Schemes Act 2015, which came fully into force on 6 April 2015, the same day the pension freedoms began. Members of an unfunded public service defined benefit scheme can only take a transfer to another scheme that does not offer flexible benefits, such as another defined benefit scheme. This applies to the main schemes, including:
- the NHS Pension Scheme
- the Teachers' Pension Scheme
- the Police Pension Schemes
- the Firefighters' Pension Schemes
- the Civil Service Pension Scheme (including alpha and classic)
- the Armed Forces Pension Scheme
The same rules apply to the equivalent schemes in Scotland, Wales and Northern Ireland.
In some cases you may be able to move your benefits to another defined benefit scheme, for example under the Public Sector Transfer Club when you change public-sector jobs. Your scheme administrator can explain what's possible.
Because a transfer to a personal pension isn't possible, we're not able to help with a transfer from these schemes. If you would like to understand your options, MoneyHelper offers free, impartial guidance, and your scheme's own website will have information about your benefits.
What each unfunded scheme means for you
The short sections below explain the position for the largest schemes and what members can do instead. Each scheme's own rules decide the details, and limits can change from year to year, so check with your scheme before you act.
NHS Pension Scheme
The NHS Pension Scheme is unfunded, so you can't transfer it to a personal pension or SIPP. If you want more retirement income or flexibility, NHS Pensions lists several ways to increase your pension within the scheme and alongside it. These include buying additional pension, paying for an early retirement reduction buy out (ERRBO) so that your 2015 Scheme pension can be taken up to three years before your normal pension age, but not before 65, without a reduction, and money purchase additional voluntary contributions (MPAVCs), which build up a separate invested fund with an external provider.
Teachers' Pension Scheme
The Teachers' Pension Scheme is also unfunded, so a transfer to a defined contribution pension isn't possible. Teachers' Pensions explains the options within the scheme, such as buying Additional Pension, and you can also pay additional voluntary contributions into a separate money purchase arrangement. Many teachers ask whether they can retire at 55. Our guide Can I retire at 55? explains how early retirement and the rise in the minimum pension age to 57 in April 2028 work.
Civil Service Pension Scheme
The Civil Service Pension Scheme, including alpha and the older classic, premium and nuvos sections, is unfunded. Instead of a transfer, alpha members can increase their pension by buying added pension, or pay for an effective pension age option, so that the pension built up while they pay for it can be taken up to three years before normal pension age, but not before 65, without a reduction. Members can also pay additional voluntary contributions through the scheme's AVC arrangement.
Police Pension Schemes
The police pension schemes are unfunded, so they can't be transferred to a personal pension. Your benefits can usually only be transferred to another public service scheme or another defined benefit scheme. The police schemes have their own ways to increase benefits, such as buying added pension within limits, and your force's pension administrator can tell you what is available to you.
Armed Forces Pension Scheme
The Armed Forces Pension Scheme is unfunded too. Members of AFPS 15 can buy Added Pension through yearly contracts, for themselves or to increase dependants' benefits as well. Veterans UK administers the scheme and can explain your options.
Firefighters' Pension Schemes
The firefighters' schemes are unfunded and follow the same rule: no transfer to a defined contribution pension. Your fire and rescue authority's pension administrator can explain the options in your scheme.
Options open to most members of unfunded schemes
Whichever unfunded scheme you are in, the realistic options are usually:
- Take your benefits as normal, at your scheme's normal pension age, or earlier with a reduction if your scheme allows it.
- Use your scheme's own options to increase or reshape your benefits, such as added pension or early retirement buy-outs.
- Pay into a separate pension, such as additional voluntary contributions or a personal pension, if you want money you can access flexibly later.
- Move to another public service scheme under the Club transfer rules if you change public-sector jobs.
The Local Government Pension Scheme is different
The Local Government Pension Scheme (LGPS) is a funded scheme. Contributions are invested in a fund managed by your local LGPS administering authority. In England and Wales, the regulations require each administering authority to maintain a pension fund. This means LGPS members can usually ask for a transfer value and transfer to a defined contribution pension, as long as they haven't started taking the pension.
There are conditions. In England and Wales, lgpsmember.org explains that you must have stopped paying into the scheme, must not have taken any LGPS pension, and must elect to transfer at least one year before your normal pension age. If you have more than one deferred LGPS benefit in England and Wales, you must transfer all of them or none.
The same protections apply as for any other defined benefit pension:
- The FCA requires advisers to start by assuming that a transfer will not be suitable for you. For most people, keeping a defined benefit pension is the better option. The FCA explains this on its pension transfer page.
- If your safeguarded benefits are worth more than £30,000, the law requires you to take advice from an FCA-authorised firm with the pension transfer permission before you can transfer.
- The LGPS gives valuable guaranteed benefits, including inflation-linked increases, ill-health pensions, and pensions for survivors, which you would give up. Some members also have protections such as the 85-year rule or the McCloud underpin.
Our guide to the LGPS pension explains how LGPS benefits build up, the 85-year rule, early and ill-health retirement, and how to ask your fund for a transfer value. Our explainer on pension transfer values covers how a CETV is worked out, and our defined benefit pension guide covers what you would be giving up.
If you're an LGPS member living in the UK with a transfer value of £50,000 or more, you're welcome to book a free chat about how transfers and the advice process work. We do not give defined benefit pension transfer advice, and we won't tell you whether a transfer is right for you. If you then want regulated advice, we can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client. See how it works for more.
Be wary of anyone who contacts you out of the blue offering to move a public-sector pension, especially an unfunded one, because that should not be possible. Check firms on the FCA ScamSmart site.
Not sure what type of scheme you have?
Check your latest pension statement or your scheme's website, or ask your scheme administrator whether your scheme is funded or unfunded. If you have defined contribution pensions too and you are 50 or over, you can book a free Pension Wise appointment. You're welcome to get in touch and we'll explain the general rules.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Last reviewed 23 October 2026