Guide
What happens to your DB pension if your employer goes bust? The Pension Protection Fund explained

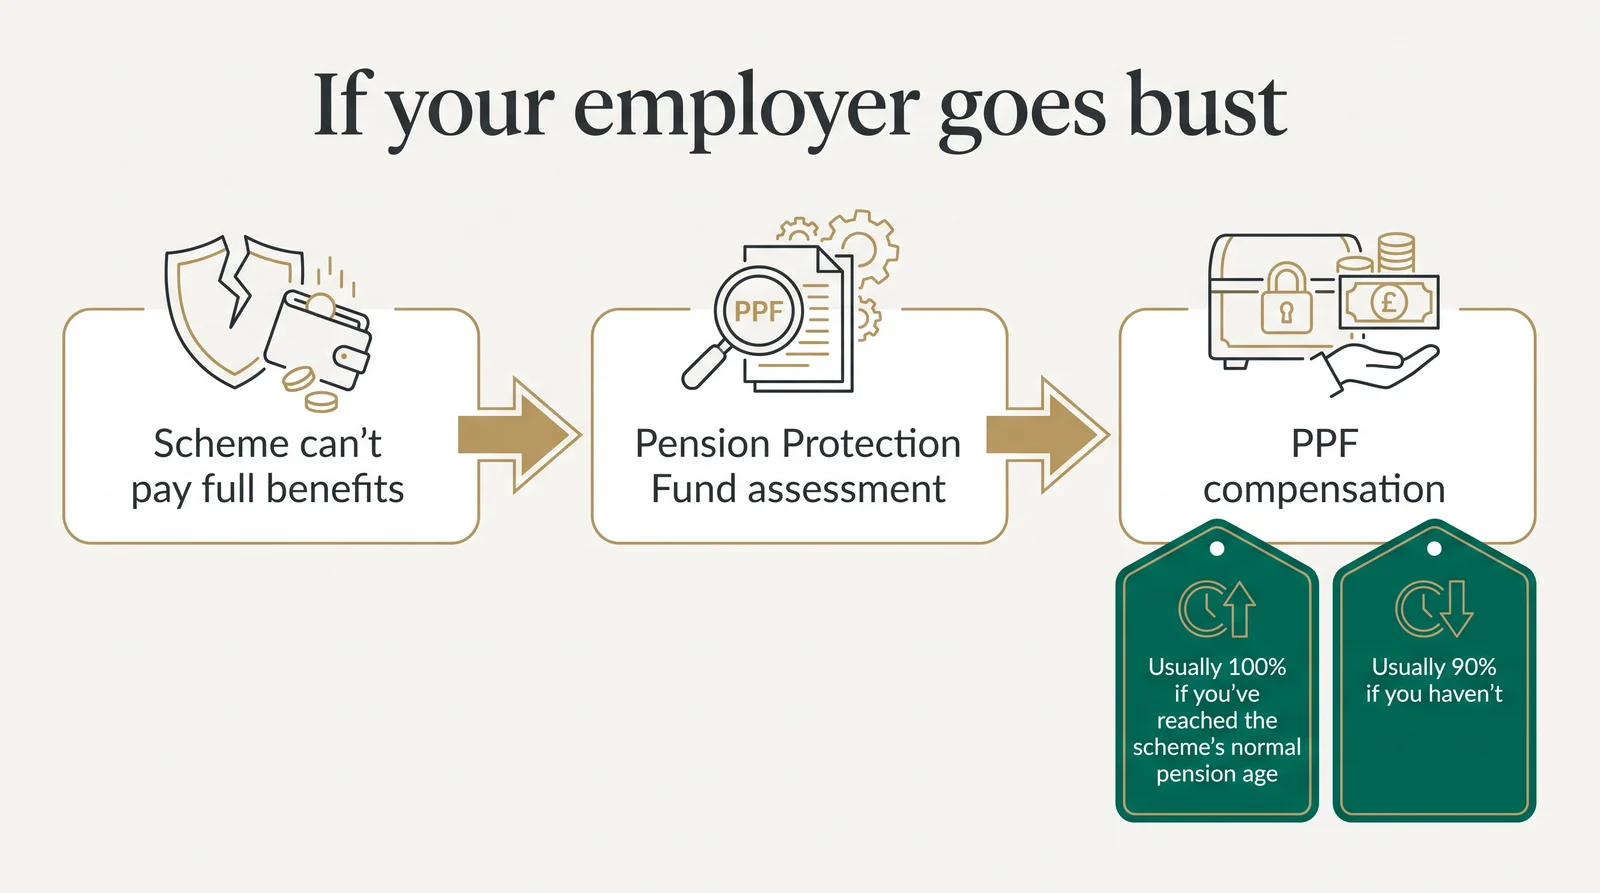
If your employer goes bust and its defined benefit scheme cannot afford the pensions it promised, the Pension Protection Fund (PPF) usually steps in. It generally pays 100% of your pension if you had reached the scheme's normal pension age, and 90% if you had not, with more limited yearly increases than many schemes provide. The scheme's assets stay separate from the employer's, and many schemes can still pay full benefits even after the employer fails.
Understanding defined benefit pensions and employer insolvency
Defined benefit (DB) pensions, often called final salary pensions, have long been seen as the "gold standard" of retirement income. They promise a secure, regular income for life, usually based on your salary and length of service. That promise is backed by your employer, so a natural worry is what happens if the employer runs into financial difficulty or goes out of business.
It is a fair question, and the UK has strong protections in place. Your pension scheme is run by trustees, and its assets are held separately from the employer's business. If the employer fails and the scheme cannot pay the promised benefits, the Pension Protection Fund is there as a safety net.
If you are wondering whether to transfer your pension, understanding these protections is an important part of your research. Questions about transferring often come down to comparing the security of a DB scheme with the flexibility of a personal pension, and the PPF is a big part of that security.
What is the Pension Protection Fund?
The PPF was set up by the Pensions Act 2004 to protect members of eligible defined benefit schemes. If an employer becomes insolvent and its scheme cannot afford to pay at least PPF levels of compensation, the PPF steps in and pays compensation to members instead.
The PPF is a public corporation, accountable to Parliament through the Department for Work and Pensions. It is not funded by the government or taxpayers. According to the PPF, its money comes from its investments, the assets of the schemes that transfer to it and recoveries from insolvent employers. It has also charged a levy on eligible DB schemes, although it set the conventional levy at zero for 2025/26 and 2026/27.
People in schemes whose employer became insolvent before the PPF started, in April 2005, may be covered by the separate Financial Assistance Scheme, which the PPF also runs.
How the PPF protects you
When an employer becomes insolvent, its DB scheme usually enters a PPF assessment period, which the PPF says usually lasts 18 to 24 months. The trustees stay responsible for running the scheme day to day, including paying pensioners. The PPF looks at the scheme's assets and liabilities. If the scheme can afford to pay more than PPF levels of benefits, it carries on outside the PPF, usually by buying out benefits with an insurer. If not, the scheme transfers to the PPF and its members become PPF members.
During the assessment period, benefits are generally paid at no more than PPF compensation levels, and members usually cannot transfer out.
PPF compensation levels
The level of compensation depends mainly on whether you had reached your scheme's normal pension age at the assessment date, which is when the employer became insolvent and the scheme entered assessment. The PPF's own guidance sets out the current levels:
| Your position at the assessment date | Compensation from the PPF |
|---|---|
| Over the scheme's normal pension age | 100% of the pension in payment |
| Receiving a spouse's, dependant's or ill-health pension | 100% of the pension in payment |
| Under the scheme's normal pension age, including early retirees | 90% of the pension you were promised |
The compensation cap no longer applies. There used to be a legal limit on compensation for people below normal pension age. Following a Court of Appeal ruling in July 2021, the PPF no longer applies the cap, and it has been increasing compensation for members who were previously capped.
Yearly increases
Yearly increases on PPF compensation are generally more limited than many schemes provide. The PPF's page on whether payments increase explains the current position:
- Compensation built up from 6 April 1997 rises each January in line with the Consumer Prices Index (CPI), up to a maximum of 2.5% a year. If CPI is negative, compensation is not reduced.
- Compensation built up before 6 April 1997 has historically not increased at all.
This is changing. The Pension Schemes Act 2026 allows the PPF to pay inflation increases of up to 2.5% a year on compensation built up before 6 April 1997, but only where the member's original scheme rules provided for those increases. The PPF's pre-97 indexation page says the first increases are expected to be payable from 1 January 2027 for most affected members, and from 1 January 2028 for members whose schemes only gave pre-1997 increases on their post-1988 Guaranteed Minimum Pension. The change applies to future payments only and is not backdated.
Some benefits, such as discretionary increases or generous early retirement terms, may not be carried over into PPF compensation. You can check the current rules on the PPF website.
The PPF and transfers
The PPF gives substantial peace of mind, and it is one of the things to understand when you look at a final salary pension and its transfer value. Some people compare the possibility of a 10% reduction in benefits if their employer fails with the cash equivalent transfer value (CETV) they could move to a personal pension. That comparison can be misleading: a transfer swaps a protected, guaranteed income for an investment pot that carries its own risks, with no PPF behind it.
Understanding the financial health of your employer and your scheme is useful. Your scheme's annual funding statement tells you how well funded it is, and trustees must tell members if the scheme enters a PPF assessment period. Every DB scheme carries some risk, even with the PPF behind it.
Once a scheme is in a PPF assessment period, the PPF says it is generally not possible, by law, to transfer your benefits out. If your scheme is not in assessment, you may still be able to transfer, and your scheme administrator can confirm the position.
Some well-funded schemes never go near the PPF because they insure members' pensions with an insurance company instead. Our guide to pension buy-ins and buy-outs explains how that works and how the protection changes.
An adviser with the pension transfer permission will usually look at the scheme's funding and the employer's strength as part of the analysis. The PPF does not copy every feature of a scheme's benefits, especially for people with complex benefit structures, so the details matter.
Is the risk of the employer going bust a reason to transfer?
For most people, no. The PPF provides a strong safety net, which greatly reduces the risk to DB members if their employer fails. For most members, even the 90% level of compensation is likely to be worth more, and be more secure, than they could achieve by giving up their guaranteed income and investing a transfer value themselves.
Concern about an employer's future should not, on its own, drive a decision to transfer. A transferred pension depends on investment returns and how much you withdraw, and it can run out. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people.
Whether to transfer a defined benefit pension is a complex decision. It involves a thorough look at your circumstances, goals, attitude to risk, health and family, and a detailed comparison of what the scheme provides with what a flexible pension might offer. The PPF is an important part of the security of DB pensions, and for most people it strengthens the case for keeping them.
Getting advice and guidance
If your safeguarded benefits are worth more than £30,000, the law requires you to take regulated advice from an FCA-authorised adviser whose firm holds the pension transfer permission before you can transfer. That advice must be given or checked by a pension transfer specialist. A regulated adviser can explain the consequences of a transfer, assess the long-term effects and risks, and help you make an informed decision.
An adviser can also help you explore alternatives, such as keeping your DB pension and using other savings for flexibility.
For free, impartial guidance, contact MoneyHelper, or book a free Pension Wise appointment if you are 50 or over and have a defined contribution pension. If your scheme is in difficulty, the PPF and The Pensions Regulator publish information for members. Fraudsters sometimes target members of schemes in the news, so be wary of anyone who contacts you out of the blue about your pension, and check the FCA ScamSmart site before dealing with any firm.
If you would like to understand how DB transfers and the advice process work, you can book a free chat about how the process works. It is general information, not advice. Our defined benefit pension guide and our guide to final salary pensions explain more about how DB schemes work.
Frequently asked questions
What happens to my defined benefit pension if my employer goes bust?
The scheme's assets are held separately from the employer. If the scheme cannot afford the promised benefits, the Pension Protection Fund (PPF) usually steps in. It generally pays 100% of your pension if you had reached the scheme's normal pension age, and 90% of your accrued pension if you had not.
What is the Pension Protection Fund (PPF)?
The PPF is a UK public corporation set up under the Pensions Act 2004 to protect members of eligible defined benefit schemes. It is not funded by taxpayers: its money comes from its investments, the assets of schemes that transfer to it and recoveries from insolvent employers, and it has also charged a levy on eligible schemes. If an employer becomes insolvent and its scheme cannot pay at least PPF levels of compensation, the PPF takes over and pays compensation to members.
Will I receive my full pension if the PPF takes over my scheme?
Not necessarily. People who had reached normal pension age generally receive 100% of their pension. People who had not usually receive 90% of their accrued pension. Yearly increases are generally more limited than many schemes provide, and some discretionary benefits may not be carried over. The PPF no longer applies the compensation cap that used to affect some members. Compensation built up from 6 April 1997 rises each year with CPI, capped at 2.5%. Compensation built up before then has historically not increased, but under the Pension Schemes Act 2026 the PPF expects to start paying increases of up to 2.5% a year on it from January 2027, where the original scheme rules provided for them.
Should I transfer my DB pension because my employer might go bust?
Transferring a defined benefit pension is a significant and irreversible decision, and it should not be based on speculation about the employer alone. The PPF offers substantial protection. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. A regulated adviser with the pension transfer permission can look at your circumstances, the employer's strength and the scheme's funding.
What is a cash equivalent transfer value (CETV)?
A CETV is the lump sum value your scheme places on your defined benefit pension: the amount it would pay into another pension if you transferred. CETVs change with gilt yields and actuarial assumptions and are usually guaranteed for three months. You are normally entitled to one free statement every 12 months. Read more in our guide to transfer values.
Do I need financial advice to transfer my defined benefit pension?
Yes, if your safeguarded benefits are worth more than £30,000. You must take regulated advice from an FCA-authorised adviser with the pension transfer permission before transferring. This is because DB transfers are complex and cannot be reversed.
This article is general information, not financial advice.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read