Guide
Complete Guide to Defined Benefit Pension Transfers 2026: Everything You Need to Know

A defined benefit (DB) pension transfer means giving up a guaranteed, usually inflation-linked income for life in exchange for a cash sum, the Cash Equivalent Transfer Value (CETV), which is moved into a defined contribution (DC) pension. The FCA's starting assumption is that a transfer is unlikely to be suitable for most people, and if your safeguarded benefits are worth more than £30,000 you must take regulated advice before you can transfer. This guide explains how transfers work, what you give up and the questions worth asking along the way.
In this guide:
- What is a defined benefit pension transfer?
- How the Cash Equivalent Transfer Value (CETV) works
- What you give up when you transfer
- Reasons some people consider transferring
- FCA rules and the advice requirement
- The transfer process step by step
- Tax implications
- Questions to discuss with a regulated adviser
- Alternatives to a full transfer
- How to find an adviser with the pension transfer permission
1. What is a defined benefit pension transfer?
A defined benefit (DB) pension, sometimes called a final salary pension, promises to pay you a specific income in retirement for the rest of your life, regardless of investment performance or how long you live. Your income is typically based on your salary and the number of years you were a member of the scheme.
When you transfer a DB pension, you give up this guaranteed income in exchange for a lump sum, known as the Cash Equivalent Transfer Value (CETV). The CETV is moved into a personal pension, such as a Self-Invested Personal Pension (SIPP), or another defined contribution (DC) arrangement.
Once transferred, your retirement income is no longer guaranteed. Instead, it depends on how your investments perform over time, the charges you pay and how you choose to draw an income in retirement. A transfer cannot be reversed.
Important: The FCA's starting assumption is that a transfer is unlikely to be suitable for most people. You can read more in the FCA's consumer information. A transfer should only be considered where a regulated adviser can show it is in your best interests.
Not every DB scheme can be transferred to a DC pension. Unfunded public-sector schemes, including the NHS, Teachers', Police, Firefighters', Civil Service and Armed Forces schemes, have not been able to transfer to a DC pension since April 2015. The Local Government Pension Scheme (LGPS) is funded, so members can still transfer. Our guide to public sector pensions explains more.
2. How the Cash Equivalent Transfer Value (CETV) works
The transfer value, or CETV, is the amount your pension scheme is prepared to pay to transfer your accrued benefits elsewhere. It is the scheme's estimate, based on actuarial assumptions set by the trustees, of the value today of the benefits it has promised you.
CETVs are often expressed as a multiple of the annual pension you have given up. That multiple varies a great deal from scheme to scheme and over time. Multiples were unusually high in 2020 and 2021, when gilt yields were very low, and have generally fallen since gilt yields rose sharply in 2022. Your own scheme's quotation is the only figure that matters for you.
What affects your CETV?
A range of factors influence how your CETV is calculated, including:
- Gilt yields: often the most significant factor. When gilt yields fall, CETVs tend to rise; when yields rise, CETVs tend to fall. This is because the scheme assumes lower future investment returns when yields are low, so more money is needed today to pay the same pension. Read more in our guide: How do gilt yields affect defined benefit transfer values.
- Your scheme's funding level: trustees can reduce transfer values in some circumstances if the scheme is underfunded.
- Your age: your age and how far you are from the scheme's normal pension age affect the calculation.
- Scheme-specific actuarial assumptions: different schemes use different assumptions about life expectancy and investment returns.
- Inflation assumptions and scheme benefits: schemes with more generous inflation increases or spouse's pensions may produce higher CETVs.
For more detail, see our article on what affects defined benefit transfer values.
A CETV is guaranteed for three months from its guarantee date. You are usually entitled to one free statement every 12 months; schemes may charge for extra quotations.
3. What you give up when you transfer
Before thinking about any possible advantages, it is essential to understand what you permanently give up the moment a DB transfer completes.
Guaranteed income for life
Your DB pension pays you a set income every month until you die. In a DC pension, you could run out of money if you live longer than expected or if investment returns disappoint.
Inflation protection
Most DB pensions increase each year in line with inflation, either fully or up to a cap (for example 5% or 2.5% a year, depending on when the benefits were built up). A DC pension relies on investment growth to keep pace with rising prices.
Spouse's and dependants' pensions
DB schemes typically pay a proportion of your pension, often 50%, to a surviving spouse or civil partner, and sometimes to dependent children. Under a DC pension, your dependants receive only what is left in the pot.
Pension Protection Fund safety net
If your employer becomes insolvent, DB pensions are generally protected by the Pension Protection Fund (PPF). Once you have transferred, PPF protection no longer applies to those benefits. See our guide: What happens to your DB pension if your employer goes bust.
You also take on investment risk, the cost of advice and ongoing product and fund charges, and the responsibility for making your money last.
4. Reasons some people consider transferring
Despite the significant risks, some people explore a transfer because of their personal circumstances. Whether any of these reasons outweighs what is given up can only be judged through regulated advice. Common reasons people raise include:
Greater flexibility in retirement
Since the 2015 pension freedoms, DC pensions offer flexibility over how and when you draw an income. You can take lump sums, use flexi-access drawdown, buy an annuity or combine these options. DB pensions usually pay a fixed income from a set age, with reductions if you take it early. Flexibility on its own is not usually enough to make a transfer suitable, and an adviser will look at whether your needs could be met in other ways.
Death benefits
A DB pension usually stops when you and any eligible dependant have died. A DC pot can often be passed on to a wider range of beneficiaries. However, from 6 April 2027, unused pension funds and most death benefits are due to be brought into the scope of inheritance tax, which reduces one of the traditional attractions of a transfer for estate planning. See our 2027 pension IHT guide and Transferring a final salary scheme to secure death benefits.
Early retirement
DB schemes often have a set normal pension age and reduce your pension if you take it early. Some people consider a DC pension for more flexibility over timing. Remember that the normal minimum pension age is due to rise from 55 to 57 on 6 April 2028, unless you have a protected pension age. See Can I retire at 55? and our guide to early retirement planning.
Ill health
People with serious health conditions may have a shorter life expectancy than the scheme actuary assumes. In some cases, a regulated adviser may conclude that a transfer could provide more value to the member and their family than the DB income would have done. This is a specialist area, and many schemes also offer ill-health or serious ill-health options worth checking first.
Concerns about the scheme
Some members worry about their employer or scheme funding. The PPF exists to protect members in that situation, so concern about the employer alone is rarely a strong reason to transfer.
Remember: Even where possible advantages exist, regulated advice is required before proceeding if your benefits are worth more than £30,000, and the advice may well conclude that keeping your DB pension is the better option.
5. FCA rules and the advice requirement
By law, if the value of your safeguarded benefits (such as a DB pension) is more than £30,000, you must take advice from an FCA-authorised adviser with the pension transfer permission before the scheme can let you transfer. The scheme will ask for confirmation of that advice. You can read more on MoneyHelper.
This rule exists because DB transfers are irreversible and the consequences of unsuitable advice can be serious for retirement security. The FCA has consistently stated that it expects most people to be better off keeping their DB pension. For background on the role, see What is a pension transfer specialist?
The advice process
A regulated adviser with the pension transfer permission will carry out a detailed suitability assessment, which usually includes:
- A full fact-find covering your personal and financial circumstances, goals and health
- An assessment of your attitude to risk and capacity for loss
- An Appropriate Pension Transfer Analysis (APTA), which the FCA requires, looking at your needs and whether a transfer meets them
- A Transfer Value Comparator (TVC), which shows how much it might cost to buy the same benefits in a DC arrangement
- Consideration of your overall retirement income needs and alternatives to transferring
The adviser must also consider whether you could meet your objectives through a workplace pension you already have, rather than a new personal pension.
Abridged and full advice
The FCA allows abridged advice as a shorter, first stage of advice. It can only conclude either that you should not transfer, or that it is unclear and full advice is needed. It cannot recommend a transfer. We don't provide abridged advice.
Charging
Since 1 October 2020, firms have been banned from contingent charging for DB transfer advice, meaning they cannot charge only if the transfer goes ahead. There are limited carve-outs for people in serious ill health or serious financial hardship. See our guide to final salary pension transfer advice for how charging typically works.
Check the FCA Register
Always check that a firm holds the permission to advise on pension transfers using the FCA Register. Not all financial advisers can advise on DB transfers: it requires a specific FCA permission and individual qualifications.
6. The transfer process step by step
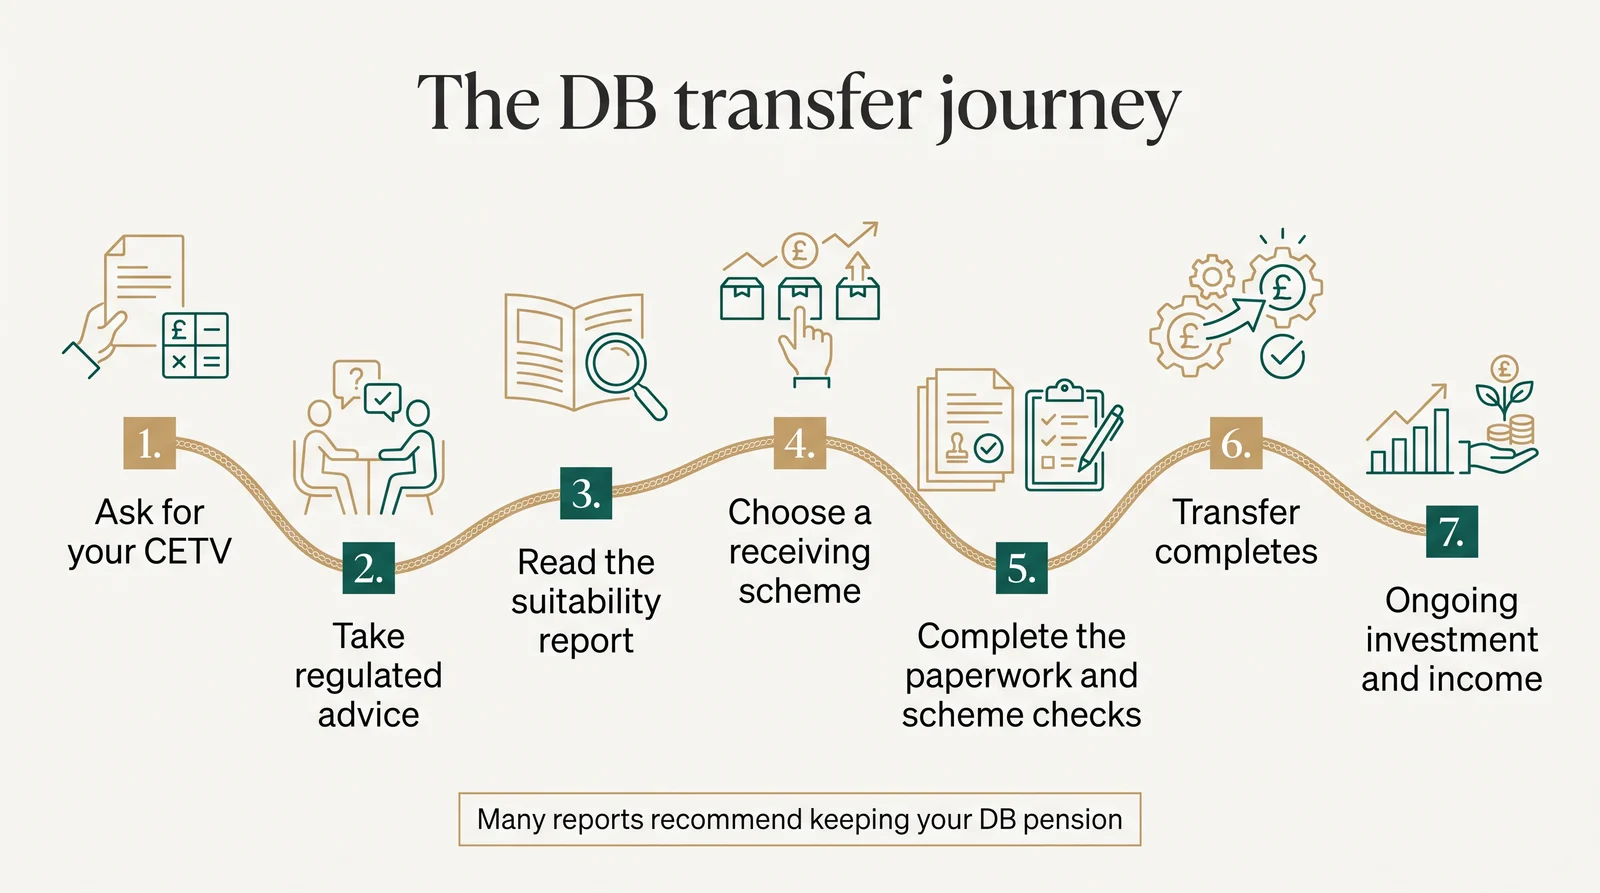
Understanding the practical steps can help set expectations. The whole process commonly takes a few months, depending on the scheme, the advice and the receiving provider.
- Request a CETV quotation: contact your scheme to request a CETV. You are usually entitled to one free statement every 12 months, and the figure is guaranteed for three months from the guarantee date.
- Take regulated advice: if your benefits are worth more than £30,000, you need advice from an FCA-authorised adviser with the pension transfer permission. You will provide detailed information about your income, assets, liabilities and retirement goals.
- Receive a suitability report: the adviser sets out their recommendation in writing. Many reports conclude that you should keep your DB pension.
- Choose a receiving scheme: if a transfer is recommended and you decide to go ahead, a DC pension is chosen to receive the CETV.
- Complete the paperwork: both schemes need signed forms and evidence that advice was taken. The sending scheme also carries out checks to help protect you from scams.
- Transfer completes: the CETV is paid to your DC pension. Trustees generally have six months from the guarantee date to pay a transfer.
- Ongoing investment and income: the money is invested and you, usually with ongoing advice, are responsible for how it is invested and drawn.
7. Tax implications of DB pension transfers
Understanding the tax rules is important when thinking about a DB transfer. HMRC's rules are summarised on gov.uk.
Tax-free cash
Under a DB scheme, you can usually take a tax-free lump sum (a pension commencement lump sum, or PCLS) by giving up some of your pension. The Lifetime Allowance was abolished from 6 April 2024. It was replaced by the Lump Sum Allowance (LSA) of £268,275 and the Lump Sum and Death Benefit Allowance (LSDBA) of £1,073,100.
In a DC pension, 25% of the fund is generally available as tax-free cash, up to the LSA. A DB scheme's commutation terms may give more or less tax-free cash than 25% of the CETV, so it is worth asking your scheme and your adviser to compare both. See our guide on pension tax-free lump sums.
Income tax
All pension income, whether from a DB pension or DC drawdown, is taxed as income in the year you receive it. Flexibility over the timing of DC withdrawals can help some people manage their income tax, but large withdrawals can also push you into a higher tax band.
Inheritance tax (2027 changes)
At present, unused DC pension pots are usually outside your estate for inheritance tax. From 6 April 2027, unused pension funds and most death benefits are due to come into the scope of inheritance tax. The detail depends on the final legislation and HMRC guidance, so check the latest position on gov.uk and with a regulated adviser. See our 2027 pension IHT guide for more.
8. Questions to discuss with a regulated adviser
There is no universal answer to whether a DB transfer is suitable, and it is not something you can decide from a checklist. A regulated adviser will explore your circumstances in depth. These are some of the topics they will cover and questions you may want to ask them:
- How will my other income, such as the State Pension or other DB pensions, be taken into account?
- How does my health and family history affect your analysis?
- What would my spouse, partner or dependants lose if I transferred?
- What do the APTA and TVC show, and what assumptions do they use?
- What would happen to my income if investment returns were poor, or if I lived to 95 or beyond?
- Could my goals be met without transferring, for example by using other savings or a partial transfer?
- How do you charge, what will ongoing advice cost, and how did you decide on that?
- What does my scheme's funding position and PPF protection mean for me?
For more, see our article Ask these questions before you transfer your pension funds.
9. Alternatives to a full DB transfer
A full transfer is not the only option, and an adviser must consider alternatives. Some worth knowing about include:
Partial transfer
Some schemes allow a partial defined benefit transfer, where you transfer part of your benefits and keep a guaranteed income from the rest. Not all schemes offer this.
Using other DC savings
If you already have DC pensions alongside your DB scheme, flexible drawdown from those pots may give you the flexibility you are looking for without giving up your DB guarantees. Some people find it helpful to understand how pension consolidation works for their DC pots, but DB benefits need much more care. See Should I consolidate my pensions?
Taking the DB pension at a different age
Many DB schemes reduce your pension if you take it early and increase it if you take it late. Looking at the scheme's early and late retirement terms can help you understand your options.
Scheme options at retirement
Your scheme may offer options such as taking more tax-free cash, a bridging pension until State Pension age, or a pension increase exchange. Ask your scheme what is available and get advice on the trade-offs.
10. How to find an adviser with the pension transfer permission
Only an FCA-authorised firm with the pension transfer permission can give the advice you need where your DB benefits are worth more than £30,000. When choosing an adviser, consider:
- FCA authorisation: check the firm's permissions on the FCA Register.
- Qualifications: the adviser who checks the advice must hold a recognised pension transfer qualification, such as AF7 (Pension Transfers) or the older G60, the LIBF Level 6 Award in Pension Transfers, or the CISI Level 6 pension transfer qualification.
- Charges: understand how they charge, whether a fixed fee or a percentage, what is included and what ongoing advice costs.
- Independence: ask whether they are independent or restricted.
- Experience: ask how long they have advised on DB transfers and how often they recommend keeping the DB pension.
A regulated adviser will always give you a written suitability report setting out their reasoning and recommendation.
How we can help
I don't give pension transfer advice, and Arthur Browns does not hold the pension transfer permission. I offer a free, no-obligation chat that gives general information about how DB transfers and the advice process work. If you then want regulated advice, I can introduce you to an FCA-authorised firm that holds the pension transfer permission. Arthur Browns may receive a fee from the firm we introduce you to if you become their client.
Introductions are for transfer values of £50,000 or more. If your transfer value is lower, MoneyHelper is a good place to start. You can book a free chat about how the process works or read more about how it works.
Free, impartial guidance and scam warnings
- MoneyHelper offers free, impartial guidance on pensions, backed by government.
- Pension Wise offers free guidance appointments about your DC pension options if you are 50 or over.
- The FCA's ScamSmart site explains how to spot pension scams. Be wary of cold calls, unexpected offers to review your pension, pressure to act quickly or promises of high returns.
Frequently asked questions
What is a defined benefit pension transfer?
A defined benefit pension transfer involves giving up your guaranteed, usually inflation-linked pension income in exchange for a Cash Equivalent Transfer Value (CETV), which is moved into a DC pension such as a SIPP. Once transferred, your retirement income depends on investment performance rather than being guaranteed for life.
Do I need financial advice to transfer my DB pension?
Yes, if your safeguarded benefits are worth more than £30,000. The law requires you to take advice from an FCA-authorised adviser with the pension transfer permission before the transfer can go ahead, because DB transfers are irreversible.
What is a CETV (Cash Equivalent Transfer Value)?
A CETV is the lump sum your DB scheme will pay to transfer your benefits to another pension. It is calculated using the scheme's actuarial assumptions and can change significantly over time, particularly with gilt yields. It is guaranteed for three months from the guarantee date.
What do you give up when transferring a DB pension?
You give up a guaranteed income for life regardless of investment returns, inflation-linked increases, any spouse's or dependants' pension, and the protection of the Pension Protection Fund if your employer later becomes insolvent.
Can I transfer my DB pension if I am already receiving it?
Generally not. Once your DB pension is in payment, you cannot usually transfer it. The right to transfer normally applies to deferred members who are not yet receiving their pension, and it usually ends a year before the scheme's normal pension age. Check your scheme's rules.
What is a Transfer Value Comparator?
A Transfer Value Comparator (TVC) is a figure the FCA requires advisers to show. It compares your CETV with an estimate of how much it would cost to buy the same income in a DC arrangement. If the estimated cost is higher than the CETV, it shows the scheme is offering you less than it would cost to replace the benefits. It replaced the older "critical yield" approach.
How long does a DB pension transfer take?
It commonly takes a few months from first requesting a CETV to the transfer completing, including time for advice and paperwork. Trustees generally have six months from the guarantee date to pay a transfer, and scam checks can add time.
What happens if my DC pension provider goes bust?
The Financial Services Compensation Scheme (FSCS) may provide protection, but the limits depend on the type of provider and investment. Check the FSCS website and ask your adviser how your pension would be protected.
Is it always wrong to transfer a DB pension?
No. While the FCA's starting assumption is that a transfer is unlikely to be suitable for most people, a regulated adviser may conclude that it is in some people's best interests, for example in some cases of serious ill health. This is why personalised, regulated advice is essential.
What is the tax-free cash allowance after the Lifetime Allowance was abolished?
Following the abolition of the Lifetime Allowance from 6 April 2024, the Lump Sum Allowance (LSA) is £268,275. This is the maximum tax-free cash most people can take across all their pensions in their lifetime, unless they have a protected higher amount. The Lump Sum and Death Benefit Allowance (LSDBA) is £1,073,100.
Important: Arthur Browns Wealth Management Ltd (FCA 825843) does not give defined benefit pension transfer advice. The FCA starts from the position that a transfer is unlikely to be suitable for most people, and a transfer cannot usually be reversed. See Important information.
Related reading
Deferred final salary pensions: what happens when you leave
What a deferred final salary pension is, how it grows until you retire, taking it early or late, tracing a lost one, and the rules if you consider a transfer.
Reviewed 23 October 2026 · 9 min read
Enhanced transfer values (ETVs): what they are and the rules
What an enhanced transfer value is, why employers offer one, the industry code's ban on cash incentives, who pays for advice and questions to ask.
Reviewed 23 October 2026 · 9 min read
How long does a DB pension transfer take?
How long a defined benefit pension transfer takes: the 3-month CETV deadlines, the advice stages, scam checks under the 2021 rules and the 6-month limit.
Reviewed 23 October 2026 · 9 min read